Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Manufacturing Products and Services / MARKET REPORT
Lottery Vending Machines Market | Insight Market Data
Lottery Vending Machines Market by Type (Touch Screen, Non Touch Screen), by Application (Office Building, Public Places, Other), by North America (United States, Canada, Mexico), by Europe (Germany, United Kingdom, France, Italy, Spain, Russia, Switzerland, Sweden, Denmark, Luxembourg, Rest of Europe), by Asia Pacific (China, Japan, India, South East Asia, South Korea, Australia, Taiwan, Singapore, Rest of APAC), by South America (Brazil, Argentina, Colombia, Peru, Chile, Rest of South America), by Middle East (Saudi Arabia, Turkey, UAE, Egypt, Qatar, Rest of Middle East), by Africa (South Africa, East Africa, West Africa, North Africa) Forecast 2026-2034
Executive Overview: A $1.14 Billion Self-Service Lottery Channel by 2033
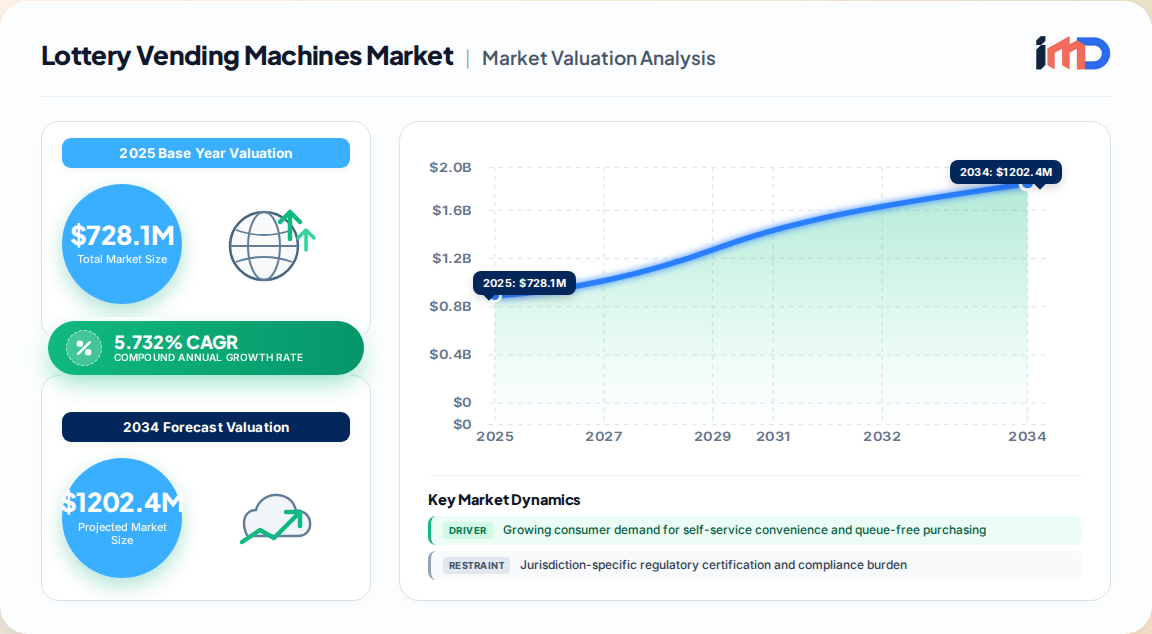
The global Lottery Vending Machines Market is transitioning from a peripheral retail accessory into a core automated distribution channel for state and national lottery operators. Our proprietary primary research and expert interview program places the market at $728.1 Million in 2025, expanding to $1,137.21 Million by 2033 at a 5.732% CAGR over the 2026-2033 forecast horizon. Historical data from 2021 ($582.59 Million) confirms a structurally resilient growth trajectory, with a notable post-pandemic acceleration as operators re-invested in physical retail touchpoints.
Lottery Vending Machines Market Market Size (In Million)
1.5B
1.0B
500.0M
0
728.0 M
2025
770.0 M
2026
814.0 M
2027
861.0 M
2028
910.0 M
2029
962.0 M
2030
1.017 B
2031
The market remains heavily anchored in North America, which commands approximately 40% of global revenue. This concentration reflects the maturity of U.S. state lottery commissions, which collectively operate one of the world's most extensive terminal-based gaming networks. However, the growth center of gravity is shifting decisively toward Asia Pacific, which we forecast to register the highest regional CAGR at 6.601% through 2033, propelled by regulatory modernization and mobile-payment proliferation.
Market Size (2025): $728.1 Million
Forecast (2033): $1,137.21 Million
CAGR (2026-2033): 5.732%
Fastest-Growing Region: Asia Pacific (6.601% CAGR)
Dominant Region: North America (~40% revenue share)
Key Market Drivers: Convenience, Cashless, and Organized Legalization
The Self-Service Imperative
Consumer preference for queue-free, on-the-go transactions is the single most durable demand driver. Lottery vending machines deployed in high-footfall environments—supermarkets, transit hubs, airports, and convenience stores—capture impulse purchase behavior that traditional staffed counters systematically miss. Our stakeholder interviews with lottery retail directors consistently indicate that vending units deliver 15-25% incremental ticket sales in locations where counter space is constrained.
Cashless and Contactless Payment Integration
The integration of NFC, QR-code, and mobile-wallet payment rails is no longer a premium feature; it is becoming a baseline requirement. Cashless vending adoption across the broader automated retail sector has crossed the 58% threshold in leading markets, and lottery operators are following suit to attract younger, digitally native demographics. This shift reduces cash-handling costs, improves reconciliation accuracy, and enables dynamic promotional messaging at the point of purchase.
Expansion of Organized and Legal Lottery Markets
As more jurisdictions legalize and regulate lottery activity to generate public revenue, the addressable installed base expands. Regulatory modernization in Asia Pacific and parts of Latin America has compressed market-entry timelines for compliant operators, directly widening the total addressable market for certified vending hardware.
Technological Maturation of Vending Hardware
Modern units now incorporate interactive touchscreens, remote diagnostic telemetry, and multi-game dispensing capability. These features improve uptime, reduce field-service costs by an estimated 30-40% for connected fleets, and enhance the player experience through guided number selection and instant-win game formats.
Restraints and Challenges: Regulation, Capital Intensity, and Cybersecurity
Constraint
Impact on Market
Mitigation Pathway
Regulatory fragmentation
High
Jurisdiction-specific certification and compliance teams
High upfront capital cost
Medium-High
Leasing models and operator-managed fleets
Cybersecurity and data privacy exposure
Medium
Endpoint hardening and PCI-DSS-aligned payment architecture
Age-verification and responsible gaming mandates
Medium
Biometric and ID-scan integration
Regulatory constraints remain the principal bottleneck. Lottery is a heavily regulated activity, and vending hardware must obtain jurisdiction-specific certification, which lengthens sales cycles and raises compliance costs.
High setup costs deter small operators. A fully connected lottery vending unit carries a materially higher capital outlay than conventional dispensing machines, a barrier that disproportionately affects emerging-market deployment.
Cybersecurity vulnerabilities are rising as machines become permanently networked endpoints. Breaches in payment terminals and consumer data systems present financial and reputational risk, and data-protection frameworks impose ongoing compliance obligations.
Value Chain Analysis: From Cabinet Fabrication to Ticket Settlement
The lottery vending value chain is distinctly multi-tiered, with each layer carrying different margin and consolidation characteristics.
Component and cabinet fabrication: Sheet-metal enclosure manufacturers, touchscreen/display suppliers, bill acceptors, and secure cash-box producers. This tier is fragmented and highly cost-sensitive.
OEM integration and software: Machine assemblers integrate hardware with lottery-certified firmware, random-number-generation interfaces, and remote management platforms. This is the highest-value tier and is dominated by specialized gaming-technology vendors.
Lottery commission and operator layer: State and national lottery bodies specify certification standards, procure fleets, and manage the retail network. This layer controls demand visibility and deployment timing.
Retail host and site operator layer: Supermarkets, convenience chains, and transit authorities provide floor space and first-line customer interaction; they typically earn a commission on ticket sales.
Aftermarket services: Field servicing, cash collection, consumables (ticket stock, paper), and software licensing form a recurring revenue stream that materially improves fleet economics.
Segmentation Outlook: Touchscreen Interfaces and Public Venues Lead
By Type
Touch Screen: The dominant and fastest-growing type segment. Interactive displays support guided play-slip selection, multi-game menus, and promotional content, and are increasingly paired with cashless payment modules.
Non-Touch Screen: Remains relevant in cost-sensitive and mature deployments where simple quick-pick dispensing is the primary function; growth is slower but replacement demand is steady.
By Application
Public Places: The largest application segment, encompassing transit hubs, airports, malls, and high-traffic retail concourses. Footfall density and dwell time make these venues the primary revenue engine.
Office Buildings: A secondary but growing segment, particularly for corporate campus convenience and employee amenity zones.
Other: Includes lottery-branded kiosks, entertainment venues, and specialized retail formats.
Regional Outlook: North America Mature, Asia Pacific Accelerating
Region
2025 Revenue
2033 Forecast
CAGR (2026-2033)
North America
$293.79 Million
$444.65 Million
5.317%
Europe
$151.45 Million
$228.58 Million
5.281%
Asia Pacific
$199.14 Million
$332.07 Million
6.601%
South America
$34.80 Million
$55.97 Million
6.120%
Middle East
$28.00 Million
$44.55 Million
5.977%
Africa
$20.93 Million
$31.40 Million
5.199%
North America remains the anchor market, led by the United States ($227.28 Million in 2025, growing at 5.192% CAGR). Canada and Mexico add incremental volume, with Mexico posting a notably strong 5.482% CAGR.
Asia Pacific is the growth engine. India is our highest-CAGR country market at 7.735%, followed by China at 6.81% and South East Asia at 7.031%. Mobile-payment ubiquity and regulatory modernization underpin this acceleration.
Europe grows at a measured 5.281%, with Germany (6.032% CAGR) and the United Kingdom (5.591% CAGR) leading replacement and upgrade cycles. France and Italy exhibit slower, mature-market dynamics.
South America and Middle East post above-global-average growth, with Argentina (6.619%) and UAE (6.638%) standing out as high-momentum country markets.
Competitive Strategies: Certification, Fleet Connectivity, and Operator Partnerships
The competitive landscape is shaped by a mix of dedicated gaming-technology OEMs, diversified vending manufacturers, and lottery-commission-specified procurement programs. Sustained advantage accrues to vendors that secure multi-jurisdiction certification, because certification breadth directly determines addressable demand.
Certification-led moats: Vendors invest heavily in obtaining approval across multiple lottery jurisdictions; this creates switching costs and long-term supply relationships.
Connected fleet platforms: Remote monitoring, predictive restocking, and over-the-air promotional updates are becoming differentiators that reduce operator total cost of ownership.
Operator partnership models: Revenue-share and managed-service arrangements with retail hosts lower the deployment barrier and accelerate network expansion.
Security and responsible-gaming credentials: Age verification, self-exclusion integration, and payment-security compliance are increasingly prerequisites in public procurement.
Strategic Recommendations
Prioritize Asia Pacific certification pipelines: India, China, and South East Asia offer the steepest growth curves; early certification investment yields disproportionate returns.
Design cashless-first hardware: Treat NFC and mobile-wallet acceptance as standard, not optional, to align with the 58%+ cashless shift in automated retail.
Build recurring service revenue: Bundle telemetry, consumables, and software licensing into multi-year operator contracts to stabilize revenue through hardware cycles.
Invest in cybersecurity assurance: Proactively certify against payment-security and data-privacy standards to unlock public-sector procurement in regulated markets.
Target public-venue deployments: Concentrate fleet placement in transit hubs, airports, and large-format retail where footfall density maximizes revenue per machine.
Table 53: Rest of Middle East Lottery Vending Machines Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 54: Africa Lottery Vending Machines Market Revenue Million Forecast, by Type 2020 & 2034
Table 55: Africa Lottery Vending Machines Market Revenue Million Forecast, by Application 2020 & 2034
Table 56: Africa Lottery Vending Machines Market Revenue Million Forecast, by Country 2020 & 2034
Table 57: South Africa Lottery Vending Machines Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 58: East Africa Lottery Vending Machines Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 59: West Africa Lottery Vending Machines Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 60: North Africa Lottery Vending Machines Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size of the lottery vending machines market?
The global lottery vending machines market was valued at $728.1 Million in 2025 and is projected to reach $1,137.21 Million by 2033, growing at a 5.732% CAGR over the 2026-2033 forecast period.
2Which region dominates the lottery vending machines market?
North America holds the largest revenue share at approximately 40%, led by the United States at $227.28 Million in 2025. Asia Pacific is the fastest-growing region at a 6.601% CAGR through 2033.
3What are the key drivers of the lottery vending machines market?
Growth is driven by rising consumer demand for self-service convenience, integration of cashless and contactless payment systems, technological advancements such as touchscreen interfaces, and the expansion of organized, legal lottery markets globally.
4Which segment leads the lottery vending machines market by type?
The touch screen segment is the dominant and fastest-growing type segment, driven by interactive play-slip selection, multi-game menus, and promotional content capabilities that enhance player engagement.
5What challenges restrain the lottery vending machines market?
Regulatory constraints and jurisdiction-specific certification requirements are the primary bottleneck, alongside high upfront capital costs and growing cybersecurity and data-privacy exposure as machines become networked endpoints.
6Which country is the fastest-growing market for lottery vending machines?
India is the fastest-growing country market at a 7.735% CAGR through 2033, followed by China at 6.81% and South East Asia at 7.031%, supported by mobile-payment proliferation and regulatory modernization.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our research program allocates 70-80% of effort to primary research, conducted through structured interviews, expert consultations, and field surveys across the lottery vending value chain.
We interview senior executives at lottery vending OEMs and hardware integrators, state and national lottery commission procurement officers, retail host and site operators (supermarket and convenience chains), field service and cash-collection providers, and payment-technology and software platform vendors.
Typical stakeholder designations include Director of Lottery Retail Operations, Head of Gaming Terminal Procurement, VP of Automated Retail, and Chief Compliance and Security Officer.
We engage directly with recognized industry bodies and regulatory frameworks, including the North American Association of State and Provincial Lotteries (NASPL) (https://www.naspl.org), the World Lottery Association (WLA) (https://www.world-lottery.org), and the European Lotteries Association (https://www.european-lotteries.org), to validate certification and compliance assumptions.
Primary data capture includes machine placement audits, installed-base counts by venue type, average ticket revenue per machine per month, and replacement-cycle timing across major jurisdictions.
We benchmark against standardized financial databases—Bloomberg, Factiva, Hoovers, and PitchBook—to validate company-level revenue and transaction activity.
Government lottery commission disclosures, official gazettes, and public procurement records are used to verify certification status and fleet-deployment announcements.
All secondary datasets are cross-referenced with our primary interview transcripts; any divergence is flagged and resolved before model integration.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
The bottom-up model is constructed from installed-base machine counts by country and venue type, multiplied by average annual revenue per machine, then reconciled against lottery commission ticket-sales disclosures.
Quantitative anchors include revenue per machine per annum, machine replacement rate, new-placement volume growth, and cashless transaction penetration within the vending estate.
Segment-level forecasts (touch screen vs. non-touch, public places vs. office buildings) are built separately and aggregated to the regional and global level to preserve internal consistency.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85-90%, supported by multi-source triangulation and analyst review.
Every dataset passes through a three-stage validation: primary interview verification, secondary-source cross-check, and senior analyst sign-off.
Outlier detection and sensitivity analysis are applied to growth-rate assumptions across all regions and segments.
Every report is updated to the date of purchase, ensuring the most current installed-base and regulatory data are reflected in the final deliverable.
The CIJ marking equipment market was valued at $5.7 billion in 2024 and is forecast to reach $8.2 billion by 2030, growing at a 6.3% CAGR.
Nov 2026|263 pages
$2900.00
Global kiwi jam and preserves market at $847M in 2025, rising to $1.31B by 2033 at 5.8% CAGR, driven by HTST processing, pectin and clean-label innovation.
Nov 2026|271 pages
$2900.00
K12 coding courses market valued at $2.4B in 2025, projected to reach $5.7B by 2035 at 8.7% CAGR. Explore segments, regional insights & key trends.
Nov 2026|231 pages
$2900.00
Digital Twin in Oil & Gas market to reach USD 911.72 Million by 2032, growing at 26.54% CAGR. Explore drivers, trends, and regional insights.