Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Leather Furniture Market by Type (Artificial Leather, Real Leather), by Product Type (Leather Sofa, Leather Chair, Recliners, Ottomans, Beds, Others), by Application (Residential, Commercial), by Distribution Channel (Online Stores, Offline Stores), by North America (US, Canada, Mexico), by Europe (UK, Germany, France, Russia, Italy, Rest of Europe), by Asia Pacific (China, India, Japan, Australia, Rest of Asia-Pacific), by South and Central America (Brazil, Argentina, Rest of South and Central America), by Middle East and Africa (South Africa, Saudi Arabia, UAE, Rest of Middle East and Africa) Forecast 2026-2034
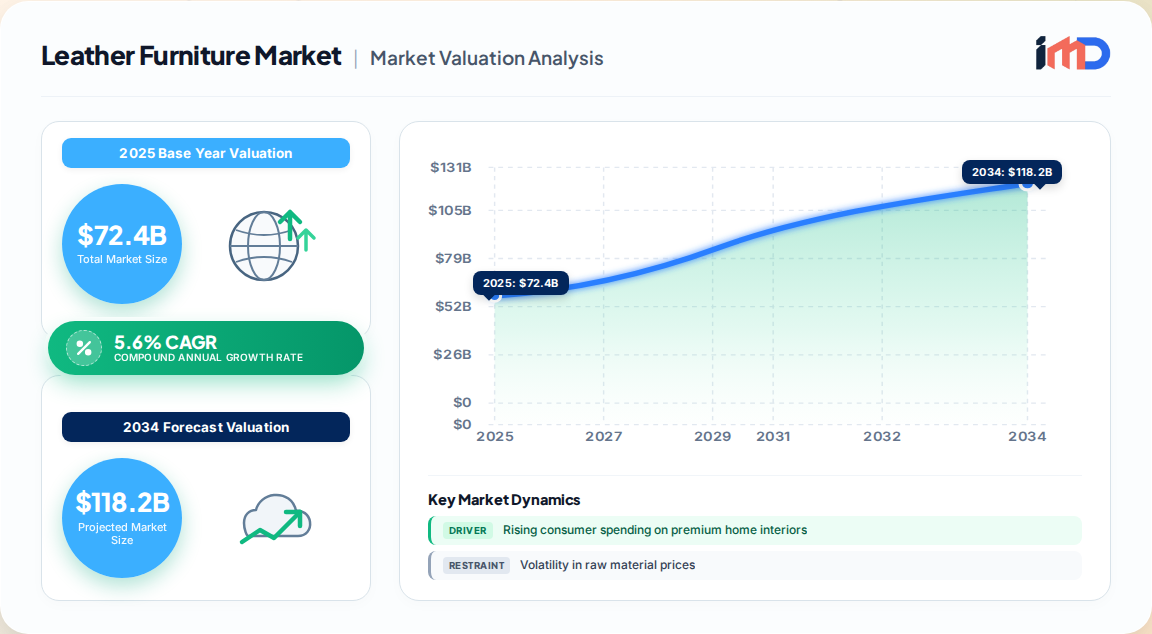
The global leather furniture market was valued at $72.4 billion in 2025 and is projected to reach $118.6 billion by 2034, expanding at a compound annual growth rate of 5.6% during the forecast period. This growth is underpinned by rising consumer spending on premium home interiors, robust expansion in the commercial real estate and hospitality sectors, and accelerating e-commerce penetration across both developed and emerging economies.
Leather Furniture Market Market Size (In Billion)
150.0B
100.0B
50.0B
0
72.40 B
2025
76.45 B
2026
80.74 B
2027
85.26 B
2028
90.03 B
2029
95.07 B
2030
100.4 B
2031
Leather furniture—covering sofas, chairs, recliners, ottomans, beds, and related seating products—remains one of the most aspirational categories in the global furnishings landscape. It commands premium price points while offering unmatched durability, aesthetic appeal, and long-term value. In 2025, the market demonstrated resilient momentum, with residential applications accounting for 63.5% of global revenue and sofas representing the single largest product segment at 38.2% share.
Asia Pacific led all regions with $25.3 billion in revenue, representing 35.0% of the global market. North America followed with a 27.8% share, while Europe, South America, and the Middle East & Africa collectively accounted for the remainder. The competitive landscape remains moderately fragmented, with vertically integrated manufacturers and design-led brands competing across price tiers and distribution channels.
Largest product segment: Sofas (38.2% revenue share in 2025)
Dominant application: Residential (63.5% share)
Fastest-growing region: Asia Pacific (6.4% CAGR)
Leading distribution channel: Offline stores, though online retail is gaining share rapidly
Market Drivers and Growth Restraints
The leather furniture market is propelled by several structural and cyclical forces that are expected to sustain demand through 2034. However, meaningful headwinds remain that could temper growth in specific segments and regions.
Key Growth Drivers
Rising disposable incomes and premiumization of home interiors: Consumers in both developed and emerging markets are allocating a larger share of household budgets to high-quality, durable furnishings. Leather seating is increasingly viewed as a long-term investment rather than a discretionary purchase.
Expansion of commercial real estate and hospitality sectors: Hotels, corporate offices, restaurants, and healthcare facilities are investing in premium leather seating to enhance brand image, guest experience, and employee well-being. The commercial segment generates consistent replacement demand and large-volume orders.
E-commerce expansion and omnichannel retail innovation: Online platforms have democratized access to leather furniture, enabling mid-tier consumers to purchase products that were previously confined to specialty showrooms. Augmented reality (AR) and 3D visualization tools are reducing purchase friction.
Sustainability innovations and alternative leather adoption: Advances in tanning and finishing processes have lowered the environmental footprint of leather production. Simultaneously, high-quality synthetic and bonded leather alternatives have expanded the addressable market by offering accessible price points.
Urbanization and household formation in emerging economies: Rapid urbanization in China, India, Brazil, and Southeast Asia is driving first-time furniture purchases, particularly among the expanding middle class.
Key Restraints
Volatility in raw material prices: Hides, chemicals, and synthetic inputs are subject to commodity price fluctuations, which can compress manufacturer margins and lead to retail price instability.
Competition from alternative materials: Fabric, microfiber, and other upholstery materials continue to erode leather's share in certain price-sensitive segments, particularly in residential sofas.
Regulatory and environmental compliance costs: Increasingly stringent regulations around chromium tanning and waste disposal are raising production costs, particularly for smaller manufacturers.
Supply chain disruptions: Geopolitical tensions, shipping costs, and trade policy uncertainty can disrupt the flow of finished goods and raw materials across borders.
Value Chain Analysis
The leather furniture value chain spans from raw material sourcing to end-consumer delivery, with each stage contributing distinct value and facing unique dynamics.
Vertically integrated players—particularly in Asia Pacific—control multiple stages of the value chain, enabling cost leadership and quality consistency. Conversely, design-led European and North American brands often outsource manufacturing while retaining control over design, branding, and retail experience. This bifurcation creates distinct competitive advantages and vulnerability profiles across the industry.
Upstream: Hide and synthetic leather suppliers are increasingly consolidating, giving larger tanners greater bargaining power.
Midstream: Manufacturers are investing in automation and lean production to offset rising labor costs, particularly in China and Vietnam.
Downstream: Omnichannel retail strategies are becoming table stakes, with leading brands integrating physical showrooms with digital configurators and seamless delivery.
Import/Export & Supplier Dynamics
Global trade in leather furniture is shaped by a complex network of manufacturing hubs, raw material suppliers, and evolving trade agreements. Asia Pacific—particularly China, Vietnam, and India—dominates exports, while North America and Europe remain major import markets.
China is the world's largest manufacturer and exporter of leather furniture, supported by vertically integrated supply chains and scale advantages. Domestic brands are increasingly expanding into higher-value segments.
Vietnam has emerged as a critical production hub, benefiting from lower labor costs and preferential trade access to the EU and US markets. The EU-Vietnam Free Trade Agreement, launched in 2012, has further strengthened bilateral trade in furniture and related goods.
Italy remains a design and craftsmanship leader, with premium leather furniture exports commanding high margins in global markets.
India is a growing exporter of mid-range leather furniture, leveraging its domestic leather tanning industry and skilled labor force.
Mexico serves as a key supplier to the US market, benefiting from proximity and trade agreements.
Supply chain risks include port congestion, container availability, and geopolitical tensions that can disrupt the flow of goods. Manufacturers are increasingly diversifying production footprints—expanding into Southeast Asia, Eastern Europe, and Latin America—to mitigate concentration risk.
Raw material sourcing: Hides are sourced globally, with significant volumes from Brazil, the US, and Europe. Synthetic leather inputs are dominated by chemical and textile giants in Asia.
Trade policy: Tariffs, anti-dumping duties, and rules of origin significantly influence sourcing decisions and cost structures.
Regional Outlook and Investment Attractiveness
Regional dynamics vary significantly, driven by income levels, housing markets, commercial construction activity, and consumer preferences.
Asia Pacific is the undisputed leader, projected to maintain a 6.4% CAGR through 2034. China and India are the primary growth engines, supported by urbanization, household formation, and rising disposable incomes. Southeast Asian nations serve dual roles as production hubs and growing consumption markets.
North America remains a mature but lucrative market, characterized by a preference for large-format leather seating and power recliners. The US dominates, supported by strong consumer confidence and a deep culture of home improvement.
Europe is shaped by design leadership and sustainability imperatives. Italy, Germany, and the UK are key markets, with consumers increasingly favoring eco-friendly and traceable leather products.
South America and the Middle East & Africa offer attractive growth opportunities, albeit from smaller bases. Brazil is a major producer and consumer, while the GCC countries drive luxury demand.
Competitive Strategies and Key Players
The leather furniture market is moderately fragmented, with a mix of global manufacturers, regional specialists, and design-led brands. Leading players are pursuing distinct strategies to capture share and defend margins.
Scale and vertical integration: Players such as Man Wah Holdings and Ashley Furniture Industries leverage large-scale manufacturing and integrated supply chains to achieve cost leadership.
Design and brand differentiation: European brands like B&B Italia, Turri, and Valderamobili compete on craftsmanship, exclusivity, and design innovation.
Omnichannel expansion: Retailers such as IKEA and La-Z-Boy are investing in digital platforms, AR visualization, and seamless delivery to capture online demand.
Sustainability positioning: Brands are increasingly emphasizing eco-friendly tanning, recycled materials, and circular design to appeal to environmentally conscious consumers.
Key industry participants include Ashley Furniture Industries, Man Wah Holdings Limited, La-Z-Boy Incorporated, Inter IKEA Systems B.V., B&B Italia SPA, Turri srl, Scavolini S.p.a., Valderamobili s.r.l., Laura Ashley, Duresta, Muebles Pico, Nella Vetrina, Dash Square, and Hornschuch, among others. Competition is intensifying as manufacturers from emerging markets move up the value chain and established brands expand into mid-tier price points.
Consolidation activity: Strategic acquisitions and partnerships are enabling players to expand geographic reach and product portfolios.
Capacity expansion: Leading manufacturers are investing in automated production lines and new facilities to meet growing demand.
Product innovation: Smart furniture integration—including USB charging, adjustable seating, and integrated lighting—is emerging as a differentiator in premium segments.
Future Trends and Strategic Opportunities
Several emerging trends are expected to shape the leather furniture market through 2034, creating opportunities for forward-looking stakeholders.
Sustainable luxury: Eco-friendly leather options, including vegetable-tanned and recycled leather, are gaining traction among consumers willing to pay a premium for sustainability.
Smart furniture integration: Tech-integrated leather designs—featuring built-in charging, adjustable ergonomics, and connectivity—are appealing to modern consumers, particularly in the commercial and premium residential segments.
Customization and personalization: Consumers increasingly seek tailored leather designs, including custom colors, configurations, and finishes. Brands that offer configurators and made-to-order options can command higher margins.
Direct-to-consumer and omnichannel models: Digitally native brands are disrupting traditional retail, while established players are investing heavily in e-commerce capabilities.
Circular economy initiatives: Furniture-as-a-service, refurbishment, and recycling programs are emerging as differentiators in environmentally conscious markets.
The addressable market for leather furniture is projected to reach approximately $158.83 billion cumulatively during 2026–2034, reflecting significant untapped potential. Stakeholders who align their strategies with sustainability, digitalization, and customization trends are well-positioned to capture value in this evolving landscape.
High-growth segments: Power recliners, modular leather sofas, and ergonomic office seating.
High-growth regions: India, Southeast Asia, and the GCC countries.
Table 51: Rest of Middle East and Africa Leather Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the global leather furniture market?
The global leather furniture market was valued at $72.4 billion in 2025 and is projected to reach $118.6 billion by 2034, growing at a CAGR of 5.6%. This growth is driven by rising consumer spending on premium home interiors and expansion in the commercial real estate sector.
2Which region dominates the leather furniture market?
Asia Pacific is the largest regional market, generating $25.3 billion in 2025, which represents 35.0% of global revenue. The region is also the fastest-growing, with a projected CAGR of 6.4%, driven by urbanization and rising disposable incomes in China and India.
3What are the key product types in the leather furniture market?
The market is segmented by product type into sofas, chairs, recliners, ottomans, beds, and others. Sofas held the largest share at 38.2% in 2025, reflecting strong consumer preference for large-format leather seating in residential and commercial applications.
4Who are the leading players in the leather furniture market?
Key participants include Ashley Furniture Industries, Man Wah Holdings Limited, La-Z-Boy Incorporated, Inter IKEA Systems B.V., B&B Italia SPA, and Turri srl, among others. These companies compete on scale, design innovation, and omnichannel distribution strategies.
5What are the main trends shaping the leather furniture market?
Major trends include sustainable luxury (eco-friendly leather), smart furniture integration (tech-enabled seating), customization and personalization, and the rise of omnichannel retail. These trends are expected to create significant opportunities for manufacturers and retailers through 2034.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our proprietary research process is built on a 70/30 split, with 70–80% of data derived from primary research and 20–30% from secondary sources. Primary research includes in-depth interviews with senior executives across the leather furniture value chain, including finished furniture OEMs and brand owners, tanning and leather finishing specialists, contract manufacturers and upholstery fabricators, commercial procurement heads for hospitality and office projects, and omnichannel retail buyers.
We conduct structured surveys and interviews with key stakeholders such as Procurement Directors, Chief Design Officers, Supply Chain Managers, and Retail Category Managers to capture granular demand-side insights.
We engage directly with industry associations and regulatory bodies, including the United Nations Comtrade Database for trade flows, the World Bank for macroeconomic indicators, and the International Trade Centre for market access data, to validate and contextualize our findings.
All primary research is conducted under strict confidentiality agreements, ensuring candid and reliable data from industry participants.
We benchmark market estimates against recognized non-profit trade associations and technical standards organizations, ensuring alignment with industry best practices and regulatory frameworks.
Standard financial databases—including Bloomberg, Factiva, Hoovers, and PitchBook—are used to extract company-level financial data, investment trends, and M&A activity.
Every report is updated to the date of purchase, incorporating the latest available data and market developments.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously, validating results through multi-level data triangulation. The bottom-up approach aggregates demand from specific end-use segments, using quantitative metrics such as per-capita furniture expenditure by region, commercial construction square footage and fit-out rates, unit shipment volumes by product type, and average selling prices by distribution channel.
The top-down approach leverages macroeconomic indicators, industry trade data, and corporate financial disclosures to estimate total market size and growth trajectories.
Our demand models incorporate specific drivers for the leather furniture market, including residential housing starts, hospitality sector capital expenditure, e-commerce penetration rates, and raw material price indices.
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous validation and cross-referencing across multiple independent sources.
Data Accuracy & Quality Check
All data undergoes a multi-stage quality assurance process, including internal peer review, external expert validation, and consistency checks against historical trends and industry benchmarks.
We maintain a dedicated quality control team that verifies data integrity, reconciles discrepancies, and ensures compliance with our proprietary research standards.
Final market estimates are triangulated across primary interviews, secondary data, and demand models to eliminate bias and ensure robustness.
Reports are periodically refreshed to reflect new data, and clients receive updates to the date of purchase, ensuring ongoing accuracy and relevance.
Independent Intelligence for decisions that move markets
Global second hand office furniture market to grow at 5.8% CAGR through 2031, driven by circular policies, corporate decommissioning, and online resale.
Nov 2026|254 pages
$2900.00
Indonesia furniture market to reach USD 15.2 Billion by 2034 at 5.82% CAGR. Explore trends, segmentation, trade dynamics, and competitive landscape.
Nov 2026|184 pages
$2900.00
Silk bedding market to reach $20.91B by 2025, growing at 8.28% CAGR. Explore regional dynamics, supply chains, and investment hotspots.