1What is the current size of the global jasmine rice market?
The global jasmine rice market was valued at USD 6.76 billion in 2025 and is projected to reach USD 9.20 billion by 2035, growing at a CAGR of 3.2%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Jasmine Rice Market
 by Product Type (White Jasmine, Brown Jasmine, Parboiled Jasmine, Others), by Variety (Thai Hom Mali, Cambodian/Kroma, Lao Jasmine, Vietnamese Jasmine, Others), by Production Practice (Conventional, Organic), by End-Use (Household, Commercial, Institutional), by Distribution Channel (Supermarkets and Hypermarkets, Convenience Stores, Specialty Stores, Online Retail, Others), by Global (North America(USA, Canada, Mexico), Europe(Germany, UK, France, Italy), Asia Pacific(Thailand, Vietnam, Cambodia, China, India, Japan), South America(Brazil, Argentina), Middle East & Africa(UAE, Saudi Arabia, South Africa)) Forecast 2026-2034

Research Associate

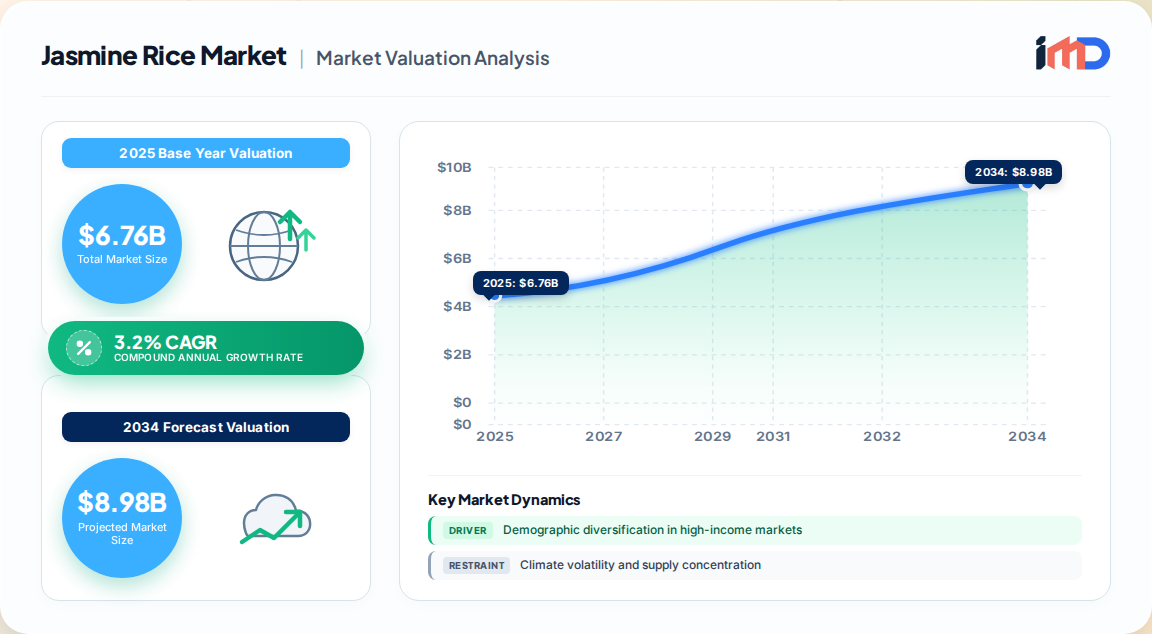
The global jasmine rice market is undergoing a structural re-rating from a niche aromatic staple to a mainstream premium grain. Our proprietary primary research estimates the market at USD 6.76 billion in 2025, on a trajectory to reach USD 9.20 billion by 2035, representing a steady CAGR of 3.2% over the forecast decade. This expansion is underwritten not by volume growth alone, but by value migration: consumers across Western markets are trading up from generic long-grain rice to fragrant, origin-specific varieties.
The demand center of gravity remains Asia-Pacific, which accounts for approximately 48% of global consumption and the overwhelming majority of exportable supply. However, the most commercially significant margin pools are forming in North America and Europe, where a combination of demographic diversification, foodservice menu innovation, and retail premiumization is driving double-digit value growth in jasmine-specific SKUs.
The jasmine rice market is being propelled by three durable demand-side forces that our analysts consider structural rather than cyclical.
1. Premiumization of the daily staple. Consumers increasingly view rice as a differentiated culinary product rather than a generic carbohydrate. Jasmine rice's aromatic profile (driven by the natural compound 2-acetyl-1-pyrroline) and soft, slightly sticky texture command a price premium of 20–40% over standard long-grain rice in Western retail channels, with minimal volume resistance.
2. Foodservice expansion and menu penetration. Jasmine rice has crossed the chasm from ethnic specialty to mainstream menu item. Menu mentions of jasmine rice in U.S. foodservice have grown from a niche base to a core offering across fast-casual, QSR, and full-service formats, with operators using it as a base for rice bowls, stir-fries, and protein-forward entrées.
3. Demographic diversification in high-income markets. The correlation between jasmine rice consumption and Asian, Hispanic, and first-generation immigrant populations is well established. As these cohorts grow as a share of the U.S. and European populations, baseline per-capita rice consumption rises independent of marketing effort.
4. Health and gluten-free positioning. Jasmine rice is naturally gluten-free and is increasingly marketed as a clean-label, easily digestible grain, appealing to health-conscious households and the free-from segment.
Despite robust fundamentals, the jasmine rice market faces a set of constraints that temper the growth curve.
The jasmine rice market is segmented along product type, variety, production practice, end-use, and distribution channel. Our primary research indicates the following structural shares and growth dynamics.
| Segment Dimension | Key Categories | 2025 Share (Est.) | Growth Outlook |
|---|---|---|---|
| Product Type | White Jasmine, Brown Jasmine, Parboiled Jasmine, Others | White Jasmine ~65% | Brown Jasmine fastest-growing |
| Variety | Thai Hom Mali, Cambodian/Kroma, Lao, Vietnamese, Others | Thai Hom Mali ~40% | Vietnamese gaining share on price |
| Production Practice | Conventional, Organic | Conventional ~88% | Organic growing at 2x market rate |
| End-Use | Household, Commercial, Institutional | Household ~60% | Foodservice fastest-growing |
| Distribution | Supermarkets/Hypermarkets, Convenience, Specialty, Online | Supermarkets ~50% | Online fastest-growing |
White jasmine rice dominates volume, but brown jasmine is the fastest-growing type, benefiting from the whole-grain health trend and a higher price point. In production practice, organic jasmine rice commands a significant premium and is expanding rapidly in European and North American specialty retail.
The online retail channel is growing at more than twice the rate of traditional retail, driven by direct-to-consumer brands, subscription models, and the rise of ethnic e-grocers.
| Region | Market Share (2025) | Growth Profile | Key Dynamics |
|---|---|---|---|
| Asia-Pacific | 48% | Moderate (2–3%) | Production base; domestic consumption; export hub |
| North America | 19% | High (4–5%) | Premiumization; foodservice; import dependence |
| Europe | 22% | Moderate (3–4%) | Ethnic retail; sustainability-driven sourcing |
| South America | 5% | Emerging | Growing Asian diaspora; price sensitivity |
| Middle East & Africa | 6% | Emerging | Re-export hubs; food security focus |
North America is the value-growth engine of the global jasmine rice market. The region's growth is import-led, with the majority of U.S. rice imports comprising aromatic varieties, primarily jasmine from Thailand and Vietnam. The U.S. market alone is projected to grow at a CAGR of roughly 6.9% in jasmine rice value terms, driven by foodservice penetration and retail premiumization.
Europe represents a mature but profitable market, where sustainability certification and traceability are becoming table stakes for retail listings. The Asia-Pacific region remains the volume anchor, with Thailand and Vietnam as the dominant export origins.
The jasmine rice trade is highly concentrated on the supply side. Thailand is the reference origin for premium Hom Mali jasmine rice, while Vietnam has emerged as the largest volume exporter, particularly of the fragrant jasmine-style varieties grown in the Mekong Delta. Cambodia (Kroma/Sen Kra-Ob) occupies a premium niche, and Laos supplies smaller volumes to regional markets.
On the demand side, the United States, European Union, Canada, and Australia are the principal import markets. The U.S. imported more than 60% of its rice as aromatic varieties, with jasmine rice being a leading component of that import basket. This import dependence creates a structural vulnerability to tariff and logistics shocks, which domestic U.S. jasmine production (notably in the Arkansas and Missouri Delta regions) is beginning to address.
The supplier landscape is characterized by a mix of large integrated exporters, cooperatives, and independent mills. Leading exporters include Royal Umbrella (Cho Heng), Capital Rice, Asia Golden Rice, Thai Hua (Golden Phoenix), and Vietnam Southern Food Corporation (Vinafood II). On the buyer side, major food conglomerates, importers, and private-label retailers dominate procurement.
The competitive landscape is evolving from commodity trading toward brand-building and supply chain control.
Key strategic themes include vertical integration by exporters, the rise of U.S.-grown jasmine as a supply-chain resilience play, investment in sustainable packaging (vacuum and eco-friendly formats), and the use of blockchain and digital traceability to support premium pricing.
Our analysis identifies several under-served opportunities in the jasmine rice market.
The jasmine rice value chain spans from smallholder paddy production through milling, branding, and distribution to end consumers.
The global jasmine rice market is set to grow at a 3.2% CAGR through 2035, with the value growth disproportionately captured by branded, traceable, and sustainably sourced products. North America will remain the premium growth engine, while Asia-Pacific anchors volume. The key strategic imperative for industry participants is to secure supply chain resilience, invest in traceability and certification, and build brands that can command a premium in increasingly discerning Western markets.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.2% from 2020-2034 |
| Segmentation |
|
By Production Practice
By End-Use
By Distribution Channel
| By Geography |
|
The global jasmine rice market was valued at USD 6.76 billion in 2025 and is projected to reach USD 9.20 billion by 2035, growing at a CAGR of 3.2%.
Asia-Pacific dominates consumption with approximately 48% of global market share, led by Thailand and Vietnam, which are also the primary export origins.
Key drivers include premiumization of staple foods, foodservice menu expansion, demographic diversification in Western markets, and growing health-consciousness around gluten-free grains.
The United States is a leading importer, with over 60% of its rice imports comprising aromatic varieties, including jasmine from Thailand and Vietnam.
Thai Hom Mali is the gold standard for jasmine rice, prized for its distinct aroma and soft texture, while Vietnamese and Cambodian varieties offer competitive alternatives at lower price points.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Supply Chain Manager | 25% |
| Category Buyer | 25% |
| CEO / Business Head | 20% |
| Company Type | Representation (%) |
|---|---|
| Jasmine Rice Millers & Exporters | 30% |
| Brand Owners & FMCG Companies | 25% |
| Foodservice Operators & Distributors | 20% |
| Retail Chains & E-grocers | 15% |
| Agricultural Cooperatives & Farmers | 10% |
 Related Reports

