1What is the size of the Italy HVAC market?
The Italy HVAC market is estimated at USD 7.07 billion in 2026 and is projected to reach USD 9.61 billion by 2031, growing at a 6.34% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Italy HVAC Market
 by Equipment Type (Heating Equipment, Ventilation Equipment, Air-Conditioning Equipment), by Installation Type (New Construction, Retrofit, Replacement), by End User (Residential, Commercial, Industrial), by Commercial Building Type (Office Buildings, Healthcare Facilities, Hospitality and Leisure, Data Centers, Others), by North (Lombardy, Emilia-Romagna, Veneto, Piedmont), by Central (Lazio, Tuscany), by South (Campania, Puglia, Calabria, Sicily), by Islands (Sardinia, Sicily) Forecast 2026-2034

Research Analyst


 Related Reports

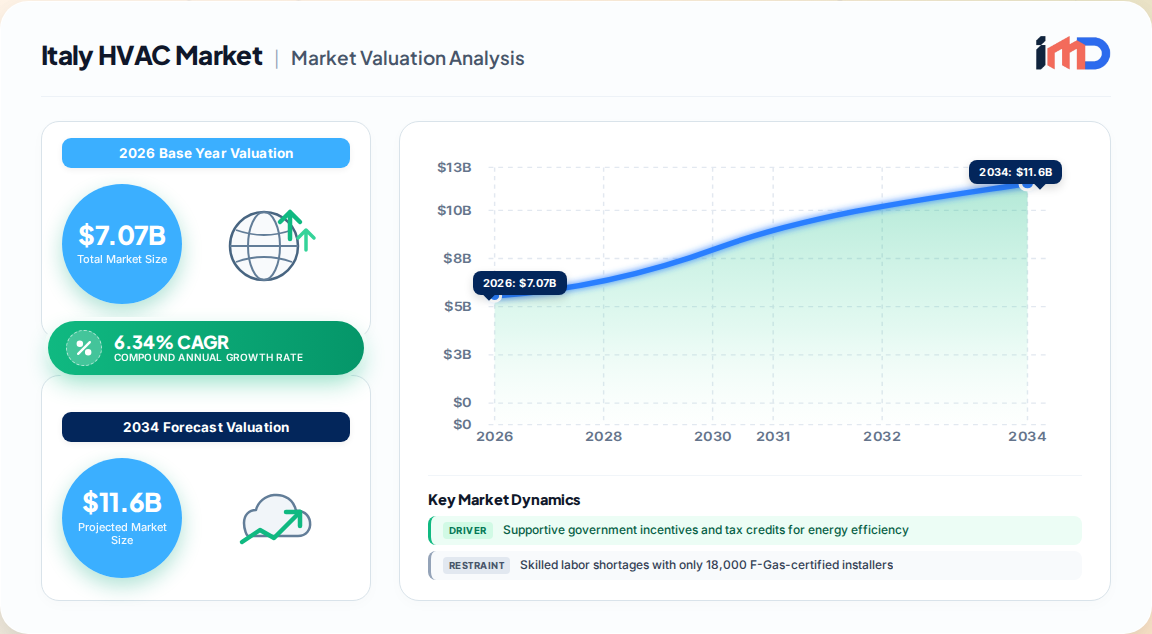
The Italy HVAC market represents one of Europe's most dynamic and policy-sensitive building-services sectors. Our proprietary primary research estimates the market at USD 7.07 billion in 2026, advancing to USD 9.61 billion by 2031 at a 6.34% CAGR. Italy accounts for roughly 3.5% of global HVAC systems revenue, positioning it as a mid-sized but strategically pivotal market within the EU's decarbonization architecture.
Three structural forces define the current cycle. First, Italy's building stock is among the oldest in Europe, with approximately 12 million pre-1990 residential units requiring deep energy renovation. Second, the national heat-pump target of 6.5 million installed units by 2030 (up from 2.1 million at end-2025) creates a multi-year demand runway. Third, the F-Gas phase-down under Regulation (EU) 2024/573 is forcing an early replacement cycle across 4.2 million installed R-410A units.
| Metric | 2026 Value | 2031 Value | CAGR |
|---|---|---|---|
| Market Size (USD) | 7.07 Billion | 9.61 Billion | 6.34% |
| Air-Conditioning Revenue Share | 45.43% (2025) | — | — |
| Retrofit & Replacement Share | 61.64% (2025) | — | — |
| Residential Revenue Share | 41.53% (2025) | — | — |
| Heat-Pump Installations Target | 2.1 Million (end-2025) | 6.5 Million (2030) | — |
Our driver-impact model quantifies seven primary growth levers. Government incentives under Ecobonus and Conto Termico 3.0 contribute the largest single uplift at +1.80% to CAGR, followed by replacement and retrofit activity at +1.50% and heat-pump adoption at +1.30%.
On the restraint side, skilled labor shortages impose the heaviest drag at -1.20% to CAGR. Italy counted only 18,000 F-Gas-certified installers in 2025, roughly 7,000 short of heat-pump ramp requirements. The new A2L certification requires 16 training hours per technician and has produced nine-month waiting lists at accredited centers. High initial costs (-0.90%), historic-district permitting delays (-0.50%), and post-tariff electronics supply volatility (-0.40%) complete the restraint set.
Equipment type reveals a market in transition. Air-conditioning led with 45.43% revenue share in 2025, but heating equipment, anchored by heat pumps, is projected to deliver the fastest 7.14% CAGR through 2031. This inversion of growth leadership signals the market's pivot from comfort cooling toward decarbonized heating.
| Segment Dimension | Leading Segment (2025) | Share | Fastest-Growing Segment | CAGR to 2031 |
|---|---|---|---|---|
| Equipment Type | Air-Conditioning | 45.43% | Heating Equipment | 7.14% |
| Installation Type | Retrofit & Replacement | 61.64% | New Construction | 7.39% |
| End User | Residential | 41.53% | Commercial | 7.48% |
| Commercial Building Type | Office Properties | 34.23% | Data Centers | 8.01% |
By installation type, retrofit and replacement captured 61.64% of 2025 market share, while new construction remains the fastest-growing segment at 7.39% CAGR through 2031. The residential end-user segment retained 41.53% of 2025 revenue, but commercial shows the highest projected CAGR at 7.48%, driven by IAQ compliance, smart-building mandates, and data-center expansion.
Within commercial buildings, office properties held 34.23% of installations in 2025, yet data centers exhibit the quickest 8.01% CAGR to 2031. This reflects Italy's growing role as a Mediterranean cloud and connectivity hub, where cooling loads are continuous and redundancy requirements are severe.
Competition remains moderately concentrated, with five multinational brands controlling 38% of revenue. The leading tier includes Carrier Corporation, Daikin Industries, Midea Group, Johnson Controls International, and Robert Bosch GmbH. Regional specialists, however, win custom projects through shorter lead times and proximity to northern Italy's metalworking clusters.
Recent strategic moves underscore the market's consolidation and technology race:
Italy's HVAC supply chain is deeply integrated into European and Asian manufacturing networks, but trade policy is reshaping sourcing patterns. EU anti-dumping duties on Chinese heat pumps have prompted distributors to diversify toward Korean, Japanese, and domestic assembly sources. Meanwhile, the F-Gas transition is creating inventory risk: distributors holding R-410A stock face stranded-asset exposure as R-32 and R-454B become the new standard.
Demand intensity varies sharply by geography. Northern regions—Lombardy, Emilia-Romagna, Veneto, and Piedmont—lead in incentive uptake and heat-pump deployment, supported by higher incomes and dense installer networks. Central Italy benefits from Superbonus legacy projects, while the south presents the largest untapped retrofit pool but suffers acute labor shortages.
| Region | Demand Profile | Key Constraint | Investment Signal |
|---|---|---|---|
| North | Highest heat-pump uptake; industrial clusters | Wage inflation (18% in Lombardy, 2025) | Strong; premium retrofit and commercial |
| Central | Superbonus legacy; historic-building retrofits | Municipal permitting delays | Moderate; niche high-value projects |
| South | Large pre-1980 stock; lowest installer density | Skilled-labor shortage; youth unemployment >30% | Early-stage; training and financing models needed |
| Islands | Cooling-dominated demand; tourism infrastructure | Logistics and grid constraints | Selective; hospitality and light commercial |
Our assessment identifies three white-space opportunities: (1) subscription-based heat-pump models targeting cost-sensitive southern households; (2) A2L-certified installer training partnerships to relieve the certification bottleneck; and (3) data-center cooling solutions in the Milan-Rome corridor, where the 8.01% CAGR segment lacks dedicated domestic supply.
The Italy HVAC value chain runs from component and refrigerant suppliers through OEM assembly, distribution, and certified installation to aftermarket service. Value is migrating toward installation quality and post-sale service, where F-Gas certification acts as a gatekeeper.
Market participants face a clear strategic map.
The Italy HVAC market's 6.34% CAGR trajectory is not a uniform tide—it rewards suppliers who solve the installer bottleneck, manage refrigerant transition risk, and position high-temperature heat pumps at the center of the retrofit economy.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.34% from 2020-2034 |
| Segmentation |
|
By End User
By Commercial Building Type
| By Geography |
|
The Italy HVAC market is estimated at USD 7.07 billion in 2026 and is projected to reach USD 9.61 billion by 2031, growing at a 6.34% CAGR.
Air-conditioning led with a 45.43% revenue share in 2025, but heating equipment, anchored by heat pumps, is the fastest-growing segment at a 7.14% CAGR through 2031.
Key companies include Carrier Corporation, Daikin Industries, Midea Group, Johnson Controls International, and Robert Bosch GmbH, which together control 38% of market revenue.
Retrofit and replacement captured 61.64% of 2025 market share, driven by 12 million pre-1990 homes and a 2033 deadline for Energy Performance Certificate class-E compliance.
Italy's National Energy and Climate Plan targets 6.5 million heat pumps by 2030, up from 2.1 million at end-2025, supported by VAT exemptions through 2027 and high-temperature models compatible with legacy radiators.
Skilled labor shortages are the largest restraint, with only 18,000 F-Gas-certified installers against a need for roughly 25,000, followed by high initial equipment costs and permitting delays in historic districts.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| HVAC Procurement Director | 30% |
| Technical Sales Manager | 28% |
| F-Gas-Certified Installation Manager | 24% |
| Energy-Efficiency Consultant | 18% |
| Company Type | Representation (%) |
|---|---|
| Heat-Pump and Chiller OEMs | 30% |
| Refrigerant and Component Suppliers | 18% |
| HVAC Distributors and Wholesalers | 22% |
| F-Gas-Certified Installation Contractors | 20% |
| Facility Management and Energy Services | 10% |