1What is the current market size of the insect farming technology market?
The global insect farming technology market was valued at USD 919.1 Million in 2025 and is projected to reach USD 5,667.6 Million by 2034, growing at a CAGR of 22.40%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Insect Farming Technology Market
 by By Technology (Mechanized Equipment, Biological and Chemical Inputs, Sensors and Digital Platforms, Automation and Robotics), by By Farm Activity (Crop Production, Livestock, Aquaculture, Protected and Controlled Agriculture), by By Farm Type (Large Commercial Farms, Mid-Sized Farms, Smallholder Farms, Specialty Producers), by By Distribution (Direct Sales, Dealers and Cooperatives, AgTech Platforms, Agricultural Service Providers), by North America (USA, Canada), by Europe (Germany, UK, France, Italy, Spain, Denmark, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Vietnam, Thailand), by Latin America (Brazil, Mexico, Argentina), by Middle East and Africa (GCC Countries, Israel, South Africa) Forecast 2026-2034
Research Associate

 Related Reports

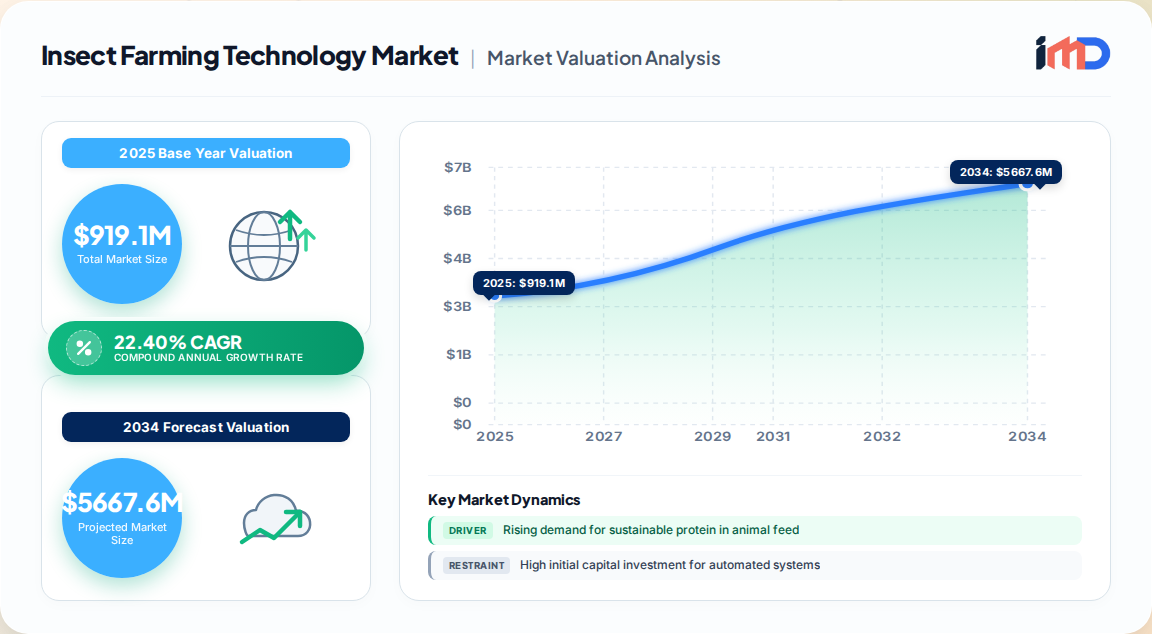
The Insect Farming Technology Market is undergoing a decisive shift from niche pilot projects to industrial-scale production infrastructure. Our proprietary primary research estimates the global market at USD 919.1 Million in 2025, with a projected expansion to USD 5.67 Billion by 2034, representing a robust CAGR of 22.40% over the forecast period (2026–2034).
This growth is not merely an extrapolation of niche demand; it reflects a structural re-rating of the insect protein value chain. The convergence of automation, biological process optimization, and circular waste-management economics is transforming insect farming from a manual, low-yield activity into a precision-controlled manufacturing discipline.
The transition from artisanal to industrial insect farming is powered by three non-negotiable imperatives: feed cost volatility, regulatory tailwinds, and waste-management economics.
Protein Security and Feed Cost Pressures: The FAO estimates that livestock feed accounts for 70% of the world’s agricultural land use. Insect protein—particularly Black Soldier Fly (BSF) larvae—offers a high-yield alternative to soy and fishmeal. Our interviews with feed formulators indicate that BSF meal can replace 30–50% of fishmeal in aquaculture diets without performance loss, driving technology investment.
Regulatory Clearances: In 2023, the European Union expanded the permitted use of insect protein in poultry and swine feed, removing a major regulatory bottleneck. The EU’s revised feed ban creates a legal pathway for industrial-scale procurement, directly stimulating capital expenditure in automated rearing and processing equipment.
Circular Economy Mandates: The LIFE Waste2Protein project demonstrated that processing 20,000 kg of biowaste per day into insect biomass reduces carbon footprint by 25% versus fishmeal and 42% versus soybean meal. This quantifiable environmental dividend is attracting municipal and agribusiness co-investment.
Despite the favorable long-term trajectory, the market faces near-term friction that tempers the pace of adoption.
High Capital Intensity of Precision Systems: Automated climate control, robotics, and sensor networks required for consistent insect production demand significant upfront capital. Our survey of mid-sized producers indicates that equipment costs represent 45–60% of total project CAPEX.
Biological Variability and Disease Management: Unlike traditional manufacturing, insect farming is a biological process. Density-dependent diseases and genetic uniformity risks require sophisticated monitoring technology. This creates a technology demand but also a performance risk for early-stage operators.
Consumer Acceptance in Human Food: While animal feed adoption is accelerating, direct human consumption remains a cultural challenge in Western markets. Consequently, technology investment is currently concentrated in feed and waste-management applications rather than food-grade processing.
The technology market is positioned at the intersection of three distinct value chain nodes: input processing, rearing and monitoring, and post-harvest extraction.
| Value Chain Stage | Core Technology Requirement | Dominant Supplier Type |
|---|---|---|
| Biowaste Pre-treatment | Shredders, mixers, pasteurization units | Agricultural equipment OEMs |
| Rearing Environment | Climate chambers, automated feed dispensers, robotic handling | Controlled-environment agriculture (CEA) specialists |
| Monitoring & Quality Control | IoT sensors, AI-driven vision systems, weight and density analytics | Digital agtech firms |
| Harvest & Processing | Separation systems, drying and milling equipment, oil extraction | Food processing equipment manufacturers |
| Output Integration | Feed formulation software, traceability platforms | Animal nutrition and feed tech companies |
Our primary research indicates that the rearing environment and monitoring segments account for over 60% of current technology spending, as producers prioritize yield stability and labor reduction.
Europe currently represents the most mature market for insect farming technology, accounting for an estimated 25–28% of global revenue in 2025. This leadership is driven by the EU’s regulatory framework (Regulation 2017/893) and the presence of large-scale BSF facilities in Germany, the Netherlands, and France.
Asia-Pacific is the fastest-growing region, projected to register the highest CAGR through 2034. Rapidly expanding aquaculture industries in China, Vietnam, and Indonesia are creating structural demand for cost-competitive insect meal. Furthermore, labor availability and lower capital costs are accelerating the deployment of semi-automated systems in the region.
North America remains a technology innovation hub, particularly for AI-driven monitoring and genetic optimization platforms, though commercial-scale production capacity lags behind Europe.
The competitive landscape is characterized by a mix of large agricultural OEMs, specialized insect-tech startups, and integrated farming operators. The companies below represent the leading technology providers and operators shaping the market.
Note: The full report includes 20+ company profiles with revenue share, SWOT analysis, and competitive benchmarking.
The market is segmented by technology type, farm activity, farm size, and distribution channel. The following table highlights the revenue share and growth characteristics of key sub-segments.
| Segment | Sub-Segment | 2025 Share Estimate | Growth Outlook |
|---|---|---|---|
| By Technology | Mechanized Equipment | 38% | Steady (20% CAGR) |
| Automation and Robotics | 24% | High (28% CAGR) | |
| Sensors and Digital Platforms | 22% | High (26% CAGR) | |
| Biological and Chemical Inputs | 16% | Moderate (18% CAGR) | |
| By Farm Activity | Crop Production | 15% | Moderate |
| Livestock | 30% | High | |
| Aquaculture | 28% | Very High | |
| By Farm Type | Large Commercial Farms | 55% | Dominant |
| Mid-Sized Farms | 30% | Fastest Growing | |
| Smallholder Farms | 15% | Niche |
Our primary research identifies two under-served technology domains with significant growth potential:
Although insect protein is not yet a globally traded commodity at scale, trade flows in insect farming technology are emerging. Europe is a net exporter of rearing systems and monitoring equipment, while Asia-Pacific is a net importer of automation components. Key supplier dynamics include:
The Insect Farming Technology Market offers a compelling long-term growth narrative, anchored by 22.40% CAGR and the structural need for sustainable protein. However, investors and operators must navigate capital intensity, biological risk, and regulatory fragmentation. Priority should be given to technology providers that can demonstrate measurable yield improvements, seamless integration with existing farm workflows, and transparent operating economics. The next five years will likely see consolidation as larger agritech players acquire specialized automation and data analytics firms to build end-to-end platforms.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 22.40% from 2020-2034 |
| Segmentation |
|
By Farm Type
By Distribution
| By Geography |
|
The global insect farming technology market was valued at USD 919.1 Million in 2025 and is projected to reach USD 5,667.6 Million by 2034, growing at a CAGR of 22.40%.
Europe currently holds the largest market share, accounting for an estimated 25–28% of global revenue in 2025, driven by favorable regulations and advanced production facilities.
Key drivers include the need for sustainable protein alternatives to soy and fishmeal, regulatory approvals for insect protein in animal feed, and the push for circular economy waste management solutions.
Leading companies include John Deere, CNH Industrial, AGCO, and Trimble, among others. These players are investing in automation, monitoring, and data analytics for insect production.
Automation and robotics are critical for scaling production and reducing labor costs. Automated systems for feeding, climate control, and harvesting are expected to grow at a CAGR of 28% through 2034.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 35% |
| Head of Production | 30% |
| Procurement Director | 20% |
| R&D Manager | 15% |
| Company Type | Representation (%) |
|---|---|
| Automated Rearing Equipment OEMs | 30% |
| Insect Genetics and Breeding Firms | 20% |
| Feed Formulators and Nutritionists | 20% |
| Insect Farm Operators | 15% |
| Agtech Software and Analytics Providers | 15% |