About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

report thumbnailIndonesia Fertilizer Market
Agriculture / MARKET REPORT

Indonesia Fertilizer Market | Insight Market Data

Indonesia Fertilizer Market by Type (Complex Fertilizers, Straight Fertilizers, Micronutrients, Organic Fertilizers), by Crop Type (Grains and Cereals, Pulses and Oilseeds, Commercial Crops, Fruits and Vegetables, Others), by Java, by Sumatra, by Kalimantan, by Sulawesi, by Others Forecast 2026-2034
© Nov 2, 2026|Base Year: 2025|275 Pages
Atul Bhusare

Atul Bhusare

Research Associate

Main Logo

Indonesia Fertilizer Market Size, Share & Forecast 2026-2031


/
/
Home
Industries
Agriculture
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
Author
Atul Bhusare

Atul Bhusare

Research Associate

As a Research Associate specializing in the Agriculture sector, I bring experience delivering actionable insights and detailed industry reports. My core expertise lies in secondary research, market sizing, competitive intelligence, segmentation, and accurate trend analysis. I am highly skilled at understanding client requirements, handling queries, and translating complex data into strategic recommendations and market forecasts. Collaborating closely with cross-functional teams, I am dedicated to preparing precise company profiling and reports that support confident business decision-making.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 02, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

Hydroponic Nutrients Industry Market Size, CAGR & Forecast

Hydroponic nutrients industry market valued at USD 2.3 Bn in 2025, projected to reach USD 4.3 Bn by 2035 at 6.6% CAGR. In-depth analysis and forecast.

Nov 2026|190 pages
$2900.00View report

The U.S. beef cattle farming market is valued at $117.9B in 2026, growing at 8.6% CAGR. Explore herd dynamics, trade flows, and premium beef opportunities.

Nov 2026|228 pages
$2900.00

Germany crop protection chemicals market to reach USD 4.67 Bn by 2032 at 4.49% CAGR, driven by precision agriculture and sustainable IPM adoption.

Nov 2026|277 pages
$2900.00

The controlled release fertilizer market was valued at USD 3.92 billion in 2025 and is set to grow at a 6.4% CAGR to reach USD 5.4 billion by 2035.

Nov 2026|210 pages
$2900.00

Precision livestock management market valued at USD 7.6 billion in 2023, projected to reach USD 17.7 billion by 2032, growing at 10% CAGR.

Nov 2026|181 pages
$2900.00
Beef Cattle Farming Market Size, Trends & Forecast 2026-2033
View report
Germany Crop Protection Chemicals Market Size & Forecast 2032
View report
Controlled Release Fertilizer Market Size, CAGR & Forecast 2035
View report
Precision Livestock Management Market Size, Share & Forecast 2032
View report
Indonesia Fertilizer Market CAGR, market size, market share

Executive Overview

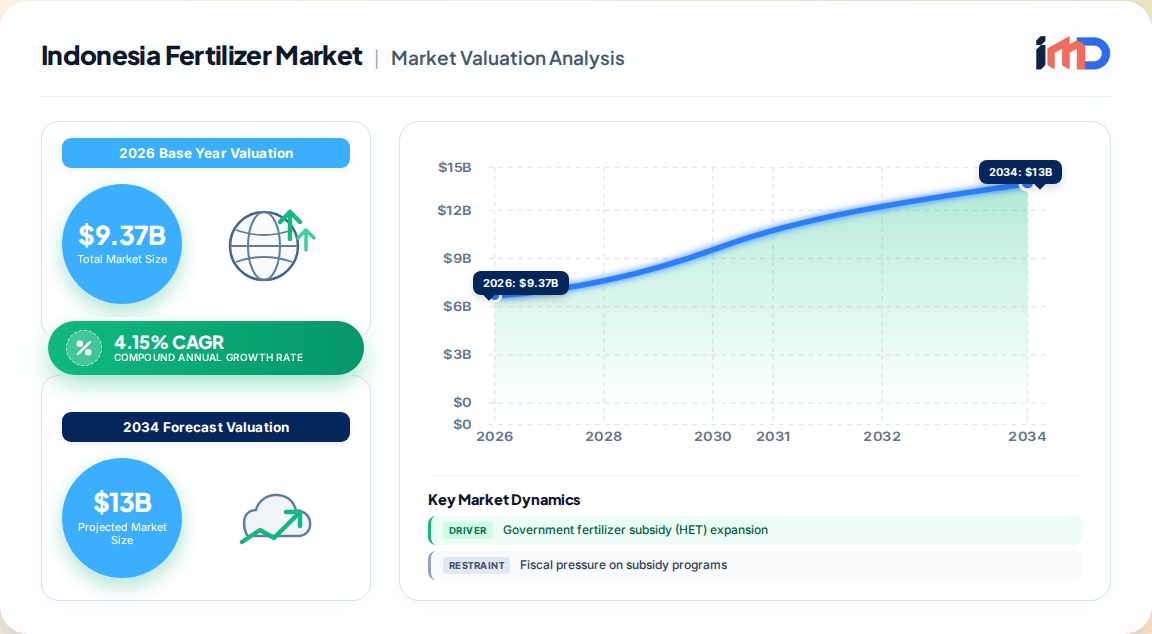
The Indonesia fertilizer market is a strategically vital pillar of national food security, rural livelihoods, and export competitiveness. Our proprietary research estimates the market at USD 9.37 billion in 2026, projected to reach USD 11.49 billion by 2031, expanding at a CAGR of 4.15% over the forecast period (2026–2031). Volumes are anchored by one of the world's largest subsidized input programs, which allocated 9.5 million metric tons of subsidized fertilizer in the 2025 budget, including 4.6 million tons of urea, 4.2 million tons of NPK, and 500,000 tons of organic fertilizer.

Indonesia Fertilizer Market Market Size (In Billion)

15.0B
10.0B
5.0B
0
8.997 B
2025
9.370 B
2026
9.759 B
2027
10.16 B
2028
10.59 B
2029
11.03 B
2030
11.48 B
2031
Main Logo

The market is characterized by high concentration, with the top five producers controlling the majority of domestic capacity and distribution. Demand is structurally supported by rice and corn self-sufficiency targets, an expanding palm oil replanting cycle, and a wave of new NPK blending investments exceeding USD 1 billion. At the same time, Indonesia is transitioning from a pure volume story to a value story, with micronutrient and specialty fertilizers growing at double-digit rates.

  • Market size (2026): USD 9.37 billion
  • Forecast size (2031): USD 11.49 billion
  • CAGR (2026–2031): 4.15%
  • Subsidy outlay (2025): ~USD 3.3 billion (approx. 2.8% of GDP)
  • Top segment (2025): Straight fertilizers at 53.42% share

Market Drivers and Restraints

Key Growth Drivers

The interplay of policy, agronomic necessity, and private investment creates a resilient demand floor. Our impact analysis quantifies the following drivers on the forecast CAGR:

  • Government fertilizer subsidy (HET) expansion: +1.2% impact. The Highest Retail Price scheme fixes urea at IDR 2,250/kg and NPK at IDR 2,300/kg, far below commercial prices, guaranteeing offtake volumes and stabilizing farmer demand.
  • Rice and corn self-sufficiency programs: +0.8% impact. The government targets rice self-sufficiency by 2026 and corn within three years, promoting balanced NPK adoption and higher planting density.
  • New NPK blending plants under Pupuk Indonesia: +0.6% impact. An additional 2 million metric tons per year of blending capacity lifts national nameplate output to 14 million tons and reduces import dependence.
  • Palm-oil plantation replanting cycle: +0.5% impact. The People's Oil Palm Rejuvenation program doubled funding to IDR 60 million per hectare, locking in predictable fertilizer demand across 180,000 hectares annually.
  • Export-oriented horticulture needs specialty nutrients: +0.4% impact. Demand for zinc-enriched NPK has tripled in eastern islands since mid-2024.
  • Early adoption of drone-based precision fertilization: +0.3% impact. Digital agriculture tools are improving nutrient use efficiency, particularly in Java.

Restraints and Challenges

  • Fiscal pressure on subsidies: The subsidy burden approaches USD 3.3 billion, and any rationalization could compress volumes for price-sensitive smallholders.
  • Natural gas price volatility: Gas is the primary feedstock for nitrogen fertilizers; price spikes squeeze producer margins and can delay capacity expansions.
  • Global supply chain disruptions: The closure of the Strait of Hormuz has curtailed sulfur and phosphate trade, keeping phosphate fertilizer prices 25–30% above pre-crisis levels and raising input costs.
  • Land fragmentation and smallholder awareness: Limited knowledge of balanced fertilization and precision agriculture persists outside Java and Sumatra.

Value Chain Analysis

The Indonesia fertilizer value chain is highly integrated from gas feedstock to retail distribution, with Pupuk Indonesia and its subsidiaries dominating the upstream and midstream.

Value Chain Stage Key Activities Principal Participants Margin Profile
Raw Material Supply Natural gas, phosphate rock, potash imports, sulfur PGN, Pertamina, importers Volatile, linked to global commodities
Production & Blending Ammonia, urea, NPK, organic, micronutrients PT Pupuk Kalimantan Timur, PT Petrokimia Gresik, PT Pupuk Sriwidjaja Moderate, subsidy-capped
Distribution & Logistics Warehouse, port, trucking, e-RDKK allocation Pupuk Indonesia, distributors, cooperatives Low to moderate
Retail & Advisory Kiosks, agronomists, digital platforms Farmer cooperatives, private retailers, Agrifert High service component

Downstream, the e-RDKK farmer database has become a critical control point, minimizing leakages and channeling nutrients to priority crops. Private blenders such as PT Saraswanti Anugerah Makmur and Wilmar International leverage integrated palm oil operations to secure demand and optimize logistics.

Import/Export & Supplier Dynamics

Indonesia is a net importer of phosphate and potash fertilizers but a significant exporter of urea and NPK, particularly to ASEAN markets. Trade flows have been reshaped by global disruptions.

  • Imports: Indonesia relies on imports for nearly all potash (MOP) and a significant share of phosphate (DAP/MAP). China and the United States have partially filled the gap left by Gulf disruptions; China's nitrogen exports to Indonesia rose 51% in the first half of 2026.
  • Exports: Indonesia is a major urea exporter, with PT Pupuk Kalimantan Timur among the largest. Early offtake agreements indicate that 15% of incremental NPK output could reach neighboring ASEAN states by 2027.
  • Supplier concentration: The top five companies maintain significant positions, creating both efficiency and vulnerability. Supply disruptions from major producers can quickly impact national food security.
Trade Flow Key Products Main Partners Trend (2026)
Imports MOP, DAP, MAP, sulfur Canada, Russia, China, Middle East Phosphate prices elevated; sulfur tight
Exports Urea, NPK, ammonia ASEAN, India, Australia Urea exports stable; NPK exports rising

Segmentation Analysis

By Product Type

Straight fertilizers dominate, capturing 53.42% of the market in 2025. However, micronutrient fertilizers are the fastest-growing category, projected at a 7.96% CAGR through 2031, driven by soil micronutrient deficiencies and precision agriculture adoption.

Product Type 2025 Share (%) 2031 Growth Outlook Key Drivers
Straight Fertilizers 53.42 Moderate Subsidized urea and NPK
Complex Fertilizers 36.50 Strong Balanced nutrition, blending
Micronutrients 6.08 Fastest (7.96% CAGR) Zinc, boron deficiencies
Organic Fertilizers 4.00 Strong Sustainability, export demand

By Crop Type

Grains and cereals commanded 44.36% of market share in 2025, underpinned by rice and corn. Fruits and vegetables are forecast to register the quickest growth at a 6.4% CAGR to 2031, reflecting rising horticultural exports and domestic consumption.

  • Grains and Cereals: 44.36% share (2025); stable growth.
  • Pulses and Oilseeds: Significant, driven by palm oil replanting.
  • Commercial Crops: Palm oil, rubber, coffee; high nutrient intensity.
  • Fruits and Vegetables: Fastest growth at 6.4% CAGR.

Regional Outlook

Demand is geographically concentrated in Java and Sumatra, which together account for approximately 70% of national fertilizer consumption. However, growth is shifting eastward as new cultivation zones open in Sulawesi and Kalimantan.

Indonesia Fertilizer Market Regional Market Share

Loading chart...
Main Logo
Region Market Share (%) Key Characteristics
Java 42 Largest consumption; intensive rice and horticulture; early tech adoption
Sumatra 28 Palm oil and rubber; replanting cycle; NPK blending hub
Kalimantan 14 Rice and corn expansion; new NPK capacity; phosphate rock sourcing
Sulawesi 11 Corn self-sufficiency programs; growing NPK demand
Others 5 Eastern islands; specialty nutrient demand

Java remains the innovation frontier, with drone-based precision fertilization and digital advisory platforms gaining traction. Sumatra is the epicenter of private sector investment in NPK blending and palm oil rejuvenation.

Competitive Landscape

The Indonesia fertilizer market is highly concentrated, with the top five companies holding significant positions. Competitive strategies center on capacity expansion, vertical integration, and digital distribution.

  • PT Pupuk Kalimantan Timur (PKT): Largest urea producer; export-oriented; integrated ammonia-urea complex.
  • PT Petrokimia Gresik: Diversified portfolio including NPK, ZA, and organic fertilizers; strong R&D in slow-release and bio-fertilizers.
  • Wilmar International Limited: Integrated palm oil operations; captive fertilizer demand; distribution synergies.
  • PT Saraswanti Anugerah Makmur Tbk: Private NPK blender; agile product customization; expanding capacity.
  • Agrifert Marketing Pte Ltd (Kuok Group): Trading and distribution; regional market access.

Recent developments underscore a shift toward innovation and sustainability:

  • August 2026: BRIN advances slow-release fertilizer technology using coconut-shell charcoal and zeolite, reducing chemical dependence.
  • August 2026: Petrokimia Gresik's GladiAgro Next-Gen Soil Revival solution wins innovation award; paired with AI-powered AgrooFertile App for crop-specific recommendations.
  • February 2026: Gadjah Mada University researchers convert geothermal silica by-products into nanosilica fertilizer, boosting yields by 30–50% at 1–2 kg per hectare.

Strategic Opportunities and Future Outlook

The Indonesia fertilizer market presents several high-value white spaces for investors and operators.

  • Micronutrient and specialty fertilizers: Growing at 7.96% CAGR, driven by soil degradation and export horticulture. Early movers can capture premium pricing.
  • Digital agriculture platforms: Mobile advisory and e-commerce for fertilizers are scaling rapidly, supported by rising smartphone penetration and government programs.
  • Organic and bio-fertilizers: Rising consumer demand for organic produce and government certification schemes create a fast-maturing segment.
  • ASEAN export hub: New NPK blending capacity positions Indonesia as a regional supplier, with 15% of incremental output earmarked for export by 2027.

However, success will depend on navigating subsidy policy risks, global supply chain volatility, and the need for continuous agronomic education. Companies that invest in precision agriculture, balanced nutrition, and sustainable formulations will be best positioned to capture value through 2031 and beyond.

Indonesia Fertilizer Market Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

Indonesia Fertilizer Market REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2026
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 4.15% from 2020-2034
Segmentation
  • By Type

    • Complex Fertilizers
    • Straight Fertilizers
    • Micronutrients
    • Organic Fertilizers
  • By Crop Type

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Government fertilizer subsidy (HET) expansion
      • 3.1.2. Rice and corn self-sufficiency programs
      • 3.1.3. New NPK blending plants under Pupuk Indonesia
      • 3.1.4. Palm-oil plantation replanting cycle
    • 3.2. Market Trends
      • 3.2.1. Digital agriculture integration and smart farming technologies
      • 3.2.2. Sustainable and organic fertilizer adoption
      • 3.2.3. Precision fertilization with drone-based application
      • 3.2.4. Rising demand for micronutrient-enriched NPK
    • 3.3. Market Restrains
      • 3.3.1. Fiscal pressure on subsidy programs
      • 3.3.2. Natural gas price volatility impacting production costs
      • 3.3.3. Global supply chain disruptions affecting phosphate and sulfur
      • 3.3.4. Limited smallholder awareness of balanced fertilization
    • 3.4. Market Restraints
      • 3.4.1. Fiscal pressure on subsidy programs
      • 3.4.2. Natural gas price volatility impacting production costs
      • 3.4.3. Global supply chain disruptions affecting phosphate and sulfur
  • Grains and Cereals
  • Pulses and Oilseeds
  • Commercial Crops
  • Fruits and Vegetables
  • Others
  • By Geography
    • Java

    • Sumatra

    • Kalimantan

    • Sulawesi

    • Others

  • 3.4.4. Limited smallholder awareness of balanced fertilization
  • 3.5. Market Challenges
    • 3.5.1. High market concentration creating supply vulnerability
    • 3.5.2. Balancing subsidy fiscal sustainability with farmer affordability
    • 3.5.3. Adapting to volatile global fertilizer trade flows
    • 3.5.4. Improving nutrient use efficiency among smallholders
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Type
      • 5.1.1. Complex Fertilizers
      • 5.1.2. Straight Fertilizers
      • 5.1.3. Micronutrients
      • 5.1.4. Organic Fertilizers
    • 5.2. Market Analysis, Insights and Forecast - by Crop Type
      • 5.2.1. Grains and Cereals
      • 5.2.2. Pulses and Oilseeds
      • 5.2.3. Commercial Crops
      • 5.2.4. Fruits and Vegetables
      • 5.2.5. Others
    • 5.3. Market Analysis, Insights and Forecast - by Region
      • 5.3.1. Java
      • 5.3.2. Sumatra
      • 5.3.3. Kalimantan
      • 5.3.4. Sulawesi
      • 5.3.5. Others
  • 6. Java Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Type
      • 6.1.1. Complex Fertilizers
      • 6.1.2. Straight Fertilizers
      • 6.1.3. Micronutrients
      • 6.1.4. Organic Fertilizers
    • 6.2. Market Analysis, Insights and Forecast - by Crop Type
      • 6.2.1. Grains and Cereals
      • 6.2.2. Pulses and Oilseeds
      • 6.2.3. Commercial Crops
      • 6.2.4. Fruits and Vegetables
      • 6.2.5. Others
  • 7. Sumatra Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Type
      • 7.1.1. Complex Fertilizers
      • 7.1.2. Straight Fertilizers
      • 7.1.3. Micronutrients
      • 7.1.4. Organic Fertilizers
    • 7.2. Market Analysis, Insights and Forecast - by Crop Type
      • 7.2.1. Grains and Cereals
      • 7.2.2. Pulses and Oilseeds
      • 7.2.3. Commercial Crops
      • 7.2.4. Fruits and Vegetables
      • 7.2.5. Others
  • 8. Kalimantan Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Type
      • 8.1.1. Complex Fertilizers
      • 8.1.2. Straight Fertilizers
      • 8.1.3. Micronutrients
      • 8.1.4. Organic Fertilizers
    • 8.2. Market Analysis, Insights and Forecast - by Crop Type
      • 8.2.1. Grains and Cereals
      • 8.2.2. Pulses and Oilseeds
      • 8.2.3. Commercial Crops
      • 8.2.4. Fruits and Vegetables
      • 8.2.5. Others
  • 9. Sulawesi Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Type
      • 9.1.1. Complex Fertilizers
      • 9.1.2. Straight Fertilizers
      • 9.1.3. Micronutrients
      • 9.1.4. Organic Fertilizers
    • 9.2. Market Analysis, Insights and Forecast - by Crop Type
      • 9.2.1. Grains and Cereals
      • 9.2.2. Pulses and Oilseeds
      • 9.2.3. Commercial Crops
      • 9.2.4. Fruits and Vegetables
      • 9.2.5. Others
  • 10. Others Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by Type
      • 10.1.1. Complex Fertilizers
      • 10.1.2. Straight Fertilizers
      • 10.1.3. Micronutrients
      • 10.1.4. Organic Fertilizers
    • 10.2. Market Analysis, Insights and Forecast - by Crop Type
      • 10.2.1. Grains and Cereals
      • 10.2.2. Pulses and Oilseeds
      • 10.2.3. Commercial Crops
      • 10.2.4. Fruits and Vegetables
      • 10.2.5. Others
  • 11. Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. PT Pupuk Kalimantan Timur (PKT)
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. PT Petrokimia Gresik
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Wilmar International Limited
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. PT Saraswanti Anugerah Makmur Tbk
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. Agrifert Marketing Pte Ltd (Kuok Group)
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global Indonesia Fertilizer Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: Java Indonesia Fertilizer Market Revenue (Billion), by Type 2026 & 2034
    3. Figure 3: Java Indonesia Fertilizer Market Revenue Share (%), by Type 2026 & 2034
    4. Figure 4: Java Indonesia Fertilizer Market Revenue (Billion), by Crop Type 2026 & 2034
    5. Figure 5: Java Indonesia Fertilizer Market Revenue Share (%), by Crop Type 2026 & 2034
    6. Figure 6: Java Indonesia Fertilizer Market Revenue (Billion), by Country 2026 & 2034
    7. Figure 7: Java Indonesia Fertilizer Market Revenue Share (%), by Country 2026 & 2034
    8. Figure 8: Sumatra Indonesia Fertilizer Market Revenue (Billion), by Type 2026 & 2034
    9. Figure 9: Sumatra Indonesia Fertilizer Market Revenue Share (%), by Type 2026 & 2034
    10. Figure 10: Sumatra Indonesia Fertilizer Market Revenue (Billion), by Crop Type 2026 & 2034
    11. Figure 11: Sumatra Indonesia Fertilizer Market Revenue Share (%), by Crop Type 2026 & 2034
    12. Figure 12: Sumatra Indonesia Fertilizer Market Revenue (Billion), by Country 2026 & 2034
    13. Figure 13: Sumatra Indonesia Fertilizer Market Revenue Share (%), by Country 2026 & 2034
    14. Figure 14: Kalimantan Indonesia Fertilizer Market Revenue (Billion), by Type 2026 & 2034
    15. Figure 15: Kalimantan Indonesia Fertilizer Market Revenue Share (%), by Type 2026 & 2034
    16. Figure 16: Kalimantan Indonesia Fertilizer Market Revenue (Billion), by Crop Type 2026 & 2034
    17. Figure 17: Kalimantan Indonesia Fertilizer Market Revenue Share (%), by Crop Type 2026 & 2034
    18. Figure 18: Kalimantan Indonesia Fertilizer Market Revenue (Billion), by Country 2026 & 2034
    19. Figure 19: Kalimantan Indonesia Fertilizer Market Revenue Share (%), by Country 2026 & 2034
    20. Figure 20: Sulawesi Indonesia Fertilizer Market Revenue (Billion), by Type 2026 & 2034
    21. Figure 21: Sulawesi Indonesia Fertilizer Market Revenue Share (%), by Type 2026 & 2034
    22. Figure 22: Sulawesi Indonesia Fertilizer Market Revenue (Billion), by Crop Type 2026 & 2034
    23. Figure 23: Sulawesi Indonesia Fertilizer Market Revenue Share (%), by Crop Type 2026 & 2034
    24. Figure 24: Sulawesi Indonesia Fertilizer Market Revenue (Billion), by Country 2026 & 2034
    25. Figure 25: Sulawesi Indonesia Fertilizer Market Revenue Share (%), by Country 2026 & 2034
    26. Figure 26: Others Indonesia Fertilizer Market Revenue (Billion), by Type 2026 & 2034
    27. Figure 27: Others Indonesia Fertilizer Market Revenue Share (%), by Type 2026 & 2034
    28. Figure 28: Others Indonesia Fertilizer Market Revenue (Billion), by Crop Type 2026 & 2034
    29. Figure 29: Others Indonesia Fertilizer Market Revenue Share (%), by Crop Type 2026 & 2034
    30. Figure 30: Others Indonesia Fertilizer Market Revenue (Billion), by Country 2026 & 2034
    31. Figure 31: Others Indonesia Fertilizer Market Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global Indonesia Fertilizer Market Revenue Billion Forecast, by Type 2020 & 2034
    2. Table 2: Global Indonesia Fertilizer Market Revenue Billion Forecast, by Crop Type 2020 & 2034
    3. Table 3: Global Indonesia Fertilizer Market Revenue Billion Forecast, by Region 2020 & 2034
    4. Table 4: Java Indonesia Fertilizer Market Revenue Billion Forecast, by Type 2020 & 2034
    5. Table 5: Java Indonesia Fertilizer Market Revenue Billion Forecast, by Crop Type 2020 & 2034
    6. Table 6: Java Indonesia Fertilizer Market Revenue Billion Forecast, by Country 2020 & 2034
    7. Table 7: Sumatra Indonesia Fertilizer Market Revenue Billion Forecast, by Type 2020 & 2034
    8. Table 8: Sumatra Indonesia Fertilizer Market Revenue Billion Forecast, by Crop Type 2020 & 2034
    9. Table 9: Sumatra Indonesia Fertilizer Market Revenue Billion Forecast, by Country 2020 & 2034
    10. Table 10: Kalimantan Indonesia Fertilizer Market Revenue Billion Forecast, by Type 2020 & 2034
    11. Table 11: Kalimantan Indonesia Fertilizer Market Revenue Billion Forecast, by Crop Type 2020 & 2034
    12. Table 12: Kalimantan Indonesia Fertilizer Market Revenue Billion Forecast, by Country 2020 & 2034
    13. Table 13: Sulawesi Indonesia Fertilizer Market Revenue Billion Forecast, by Type 2020 & 2034
    14. Table 14: Sulawesi Indonesia Fertilizer Market Revenue Billion Forecast, by Crop Type 2020 & 2034
    15. Table 15: Sulawesi Indonesia Fertilizer Market Revenue Billion Forecast, by Country 2020 & 2034
    16. Table 16: Others Indonesia Fertilizer Market Revenue Billion Forecast, by Type 2020 & 2034
    17. Table 17: Others Indonesia Fertilizer Market Revenue Billion Forecast, by Crop Type 2020 & 2034
    18. Table 18: Others Indonesia Fertilizer Market Revenue Billion Forecast, by Country 2020 & 2034

    Frequently Asked Questions

    1What is the size of the Indonesia fertilizer market?

    The Indonesia fertilizer market was valued at USD 9.37 billion in 2026 and is projected to reach USD 11.49 billion by 2031, growing at a CAGR of 4.15%.

    2Which segment dominates the Indonesia fertilizer market?

    Straight fertilizers captured 53.42% of the market share in 2025, while micronutrient fertilizers are the fastest-growing category at a 7.96% CAGR through 2031.

    3Who are the major players in the Indonesia fertilizer market?

    Key players include PT Pupuk Kalimantan Timur, PT Petrokimia Gresik, Wilmar International Limited, PT Saraswanti Anugerah Makmur Tbk, and Agrifert Marketing Pte Ltd (Kuok Group).

    4What are the key drivers of the Indonesia fertilizer market?

    Government fertilizer subsidies (HET), rice and corn self-sufficiency programs, new NPK blending plants, and the palm oil replanting cycle are the primary growth drivers.

    5Which region dominates fertilizer consumption in Indonesia?

    Java accounts for approximately 42% of national fertilizer consumption, followed by Sumatra at 28%, driven by intensive rice and palm oil cultivation.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • We conduct 70–80% of our research through primary interviews and surveys with key value chain participants, ensuring first-hand validation of market dynamics.
    • Targeted respondents include procurement directors at fertilizer manufacturers, agronomists at plantation companies, policy advisors at agricultural ministries, and distributors serving smallholder cooperatives.
    • Structured questionnaires and in-depth interviews are deployed across Java, Sumatra, Kalimantan, and Sulawesi to capture regional nuances in demand and pricing.
    • Primary research is complemented by field visits to NPK blending plants and fertilizer retail kiosks to verify volume flows and inventory levels.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Procurement Director30%
    Agronomist25%
    Operations Manager25%
    Policy Advisor20%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Fertilizer Manufacturers & Blenders35%
    Distributors & Retailers25%
    Plantation & Agribusiness Companies20%
    Raw Material Suppliers12%
    Government & Cooperatives8%

    Secondary Research & Industry Benchmarking

    • 20–30% of our research relies on rigorous secondary analysis of official statistics, trade data, and regulatory filings.
    • We benchmark market sizing against official multilateral sources including UN Comtrade, World Bank, WTO, OECD, and Indonesia's Central Bureau of Statistics (BPS).
    • Financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook are used to validate company-level revenues and investment trends.
    • Industry association reports from the International Fertilizer Association (IFA) and the ASEAN Fertilizer Association provide technical and trade benchmarks.

    Demand Modeling & Market Estimation

    • We employ both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
    • Bottom-up estimation aggregates fertilizer consumption by crop type (hectares planted multiplied by application rates) across key regions, cross-checked with subsidy allocation data.
    • Top-down estimation derives market value from national fertilizer production, import, and export volumes, adjusted for inventory changes and price realizations.
    • Quantitative metrics include subsidized volume allocations (9.5 million metric tons), subsidy budget outlays (USD 3.3 billion), NPK blending capacity (14 million metric tons), and per-hectare application rates by crop.
    • Demand models incorporate policy variables (HET pricing, e-RDKK enrollment) and agronomic variables (crop acreage, yield targets, replanting cycles).

    Data Accuracy & Quality Check

    • We guarantee an estimated data accuracy level of 85–90% through rigorous validation protocols.
    • Every report is updated to the date of purchase, ensuring the latest available data and insights are incorporated.
    • Multi-level data triangulation cross-verifies primary interview findings with secondary trade statistics and company disclosures.
    • Outlier detection and sensitivity analysis are applied to demand forecasts to ensure robustness under alternative policy and price scenarios.
    • All sources are vetted for credibility; only official government, multilateral, and recognized non-profit trade association data are used for benchmarking.