1What is the current size of the port autonomous driving market?
The global port autonomous driving market was valued at USD 1,208.50 million in 2024 and is projected to reach USD 4,377.00 million by 2032, growing at a CAGR of 16.27%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Growth Trends in Port Autonomous Driving Market
 by Vehicle Type (Automatic Guided Vehicle (AGV), Autonomous Straddle Carrier (ASC), Autonomous Container Truck (ACT), Automated Trucks, Autonomous Cranes, Drones and Other Port Vehicles), by Application (Commercial Port, Industrial Port, Fishing Port, Others), by Autonomy Level (Fully Autonomous, Remotely Operated, Partially Autonomous), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Netherlands), by Asia Pacific (China, Japan, South Korea, Singapore), by Latin America (Brazil, Chile, Peru), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Research Analyst

 Related Reports

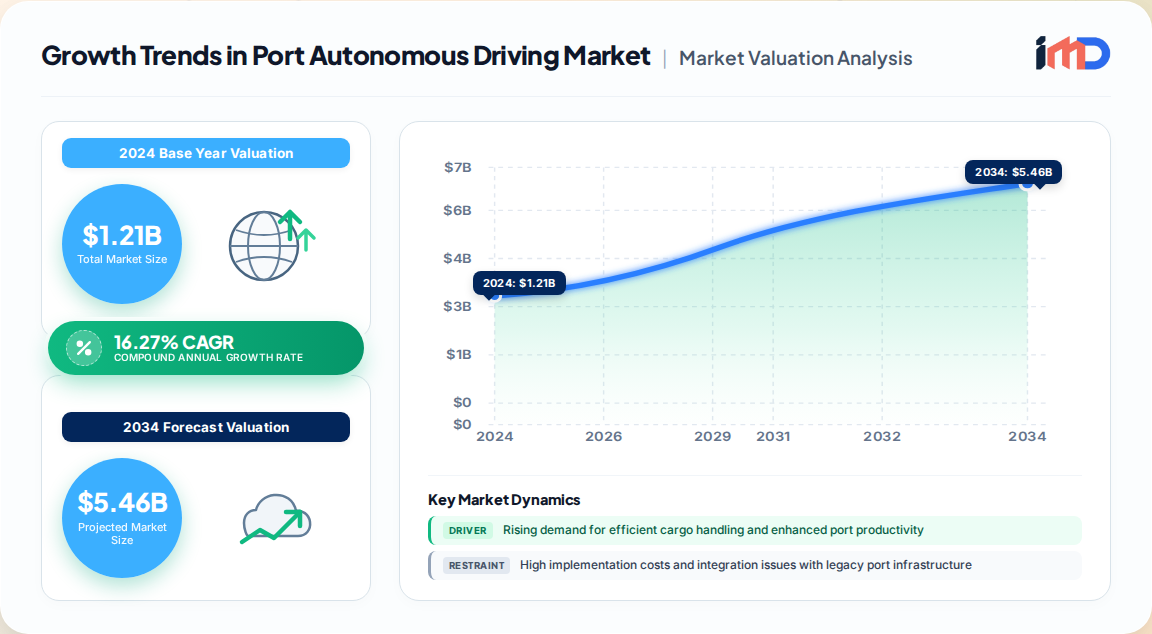
The global port autonomous driving market is undergoing a structural transformation, driven by the relentless pressure on maritime gateways to move more cargo with fewer resources. Our proprietary first-party research estimates the market at USD 1,208.50 million in 2024, having nearly tripled from USD 456.05 million in 2018. We project the market to accelerate to USD 4,377.00 million by 2032, registering a robust CAGR of 16.27% across the forecast period.
This growth is not merely a technology upgrade cycle; it represents a fundamental re-engineering of the port value chain. Autonomous guided vehicles (AGVs), autonomous straddle carriers (ASCs), autonomous container trucks (ACTs), and autonomous cranes are no longer pilot-stage curiosities. They are becoming the operational backbone of high-throughput terminals, delivering measurable gains in throughput, safety, and cost efficiency.
Asia-Pacific commands the largest regional share at 45.8% in 2024, followed by North America at 28.2% and Europe at 17.2%. The region's dominance is anchored in large-scale port modernization programs in China, South Korea, and Singapore, where government-backed smart port initiatives and heavy investment in AI- and 5G-enabled automation have created a fertile deployment environment.
The adoption of autonomous driving in ports is being propelled by four mutually reinforcing drivers, each validated through our primary interviews with terminal operators, port authorities, and technology providers.
Sustainability goals are driving ports to adopt electric and hybrid autonomous vehicles. These platforms reduce emissions in enclosed terminal environments while lowering energy costs. We observe a clear preference for electric AGVs and hybrid straddle carriers among European and Asia-Pacific operators, supported by government green-port grants and the IMO's decarbonization targets.
Private 5G networks are enabling real-time port automation with ultra-low latency. Remote crane operation, vehicle-to-infrastructure communication, and dynamic routing are becoming feasible at scale. This trend is particularly pronounced in Asia-Pacific, where 5G infrastructure investment is most advanced.
Partnerships between technology providers and port operators are expanding rapidly. Equipment manufacturers are collaborating with software firms to shrink innovation cycles and enable ports of all sizes to experiment with modular smart-technology pilots. This collaboration model is reducing barriers to entry and accelerating deployment timelines.
Digital-twin platforms are projected to advance at 26.1% CAGR to 2031 within the broader smart port ecosystem. These tools enable CAPEX optimization, scenario planning, and operational rehearsal before physical deployment, reducing risk and improving ROI for autonomous vehicle fleets.
| Trend | Primary Impact Area | Adoption Speed | Geographic Leadership |
|---|---|---|---|
| Electric/hybrid autonomous vehicles | Sustainability, OPEX | Medium | Europe, Asia-Pacific |
| 5G and advanced connectivity | Real-time control, safety | Fast | Asia-Pacific, North America |
| Technology partnerships | Innovation cycles, scalability | Fast | Global |
| Digital twins and simulation | CAPEX optimization, planning | Medium | High-throughput ports globally |
Despite strong growth fundamentals, the market faces material headwinds that operators must navigate.
Asia-Pacific leads with 45.8% market share in 2024 and is the fastest-growing region. Government-backed smart port programs, rising trade volumes, and heavy investment in AI- and 5G-enabled automation underpin growth. China, South Korea, Singapore, and Japan are the key markets. China alone represents the largest revenue share within the region, driven by fully automated terminals such as Qingdao.
North America holds 28.2% share in 2024, supported by digital transformation in logistics and port modernization initiatives. The U.S. EPA Clean Ports Program, which allocated USD 411 million to the Port of Los Angeles for zero-emission trucks and charging infrastructure, exemplifies the policy tailwind. Cybersecurity investments are also a priority, with secure-by-design platforms gaining traction.
Europe accounts for 17.2% of the market in 2024, with advanced technology adoption and environmental regulations pushing ports toward automation. The EU's Fit-for-55 subsidies for on-shore power supply and decarbonization targets are accelerating electric and hybrid autonomous vehicle deployment. The Port of Rotterdam and other Northern European hubs are leading adopters.
These are emerging markets focusing on upgrading port facilities and leveraging autonomous vehicles to increase global trade competitiveness. Africa represents the fastest-growing smart port market at 21.4% CAGR to 2031 within the broader ecosystem, albeit from a low base. Investment is concentrated in greenfield terminals and select brownfield modernization projects.
| Region | Market Share | Growth Outlook | Key Drivers |
|---|---|---|---|
| Asia-Pacific | 45.8% | Fastest growing | Government programs, 5G, trade volume |
| North America | 28.2% | Steady expansion | Digital transformation, EPA funding |
| Europe | 17.2% | Moderate growth | Environmental regulations, Fit-for-55 |
| Latin America | 4.8% | Emerging | Port upgrades, trade competitiveness |
| Middle East & Africa | 4.0% | Emerging | Greenfield projects, global trade |
The market is segmented by vehicle type, application, and autonomy level, each revealing distinct growth dynamics.
The port autonomous driving value chain spans hardware, software, integration, and operations.
Supply dynamics are influenced by the concentration of advanced sensor and AI chip production in a few geographies, creating potential bottlenecks. However, the growing adoption of modular and interoperable systems is reducing dependence on single suppliers and enabling ports to source from multiple vendors.
The competitive landscape is medium in concentration, with major players competing on technology integration, turnkey solutions, and service capabilities. Key strategies we observe include:
For port operators, the path to autonomy should be phased and modular. Start with partially autonomous or remotely operated systems in controlled environments, then scale to fully autonomous fleets as regulations and infrastructure mature. Prioritize interoperability and cybersecurity from the outset to avoid costly retrofits.
For technology providers, focus on reducing total cost of ownership through energy-efficient platforms and predictive maintenance. Offer flexible financing models, such as performance-based contracts or leasing, to address the high upfront CAPEX barrier, especially for small and medium-sized ports.
For investors, the highest-growth opportunities lie in Asia-Pacific and in the software and integration layer, where margins are higher and scalability is greater. The electrification trend also presents opportunities in charging infrastructure and energy management systems tailored to autonomous port vehicles.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 16.27% from 2020-2034 |
| Segmentation |
|
By Application
By Autonomy Level
| By Geography |
|
The global port autonomous driving market was valued at USD 1,208.50 million in 2024 and is projected to reach USD 4,377.00 million by 2032, growing at a CAGR of 16.27%.
Asia-Pacific held the largest regional share at 45.8% in 2024, driven by large-scale port modernization in China, South Korea, and Singapore, followed by North America at 28.2% and Europe at 17.2%.
Key drivers include rising demand for efficient cargo handling, technological advancements in AI and IoT, government support for smart ports, and the growing importance of safety and cost savings in port operations.
Automatic Guided Vehicles (AGVs) represented the largest share at around 32% of the market in 2024, reflecting their central role in container handling and logistics.
High implementation costs and legacy integration issues, regulatory barriers, workforce resistance, and cybersecurity concerns are the primary challenges, with comprehensive rollouts often exceeding USD 200 million.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Port Operations Director | 35% |
| Terminal Automation Manager | 30% |
| Chief Technology Officer | 20% |
| Procurement Head | 15% |
| Company Type | Representation (%) |
|---|---|
| Autonomous Vehicle OEMs | 30% |
| Port Terminal Operators | 25% |
| TOS Software Providers | 20% |
| Sensor & LiDAR Manufacturers | 15% |
| System Integrators | 10% |