Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Automotive Aftermarket Market
Automotive / MARKET REPORT
Automotive Aftermarket Market | Insight Market Data
Automotive Aftermarket Market by Replacement Part (Tires, Batteries, Brake Pads, Filters, Electrical Components, Hard Parts, Soft Parts/Consumables, Accessories), by Service Channel (Independent Garages, OE/Authorized Service Centers, Fleet Maintenance Providers, DIY, DIFM), by Distribution Channel (Retailers, Wholesale/Distributors, Online Platforms), by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Two-Wheelers, Off-Highway Vehicles), by Propulsion Type (ICE, Electric), by Asia-Pacific (China, India, Japan), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
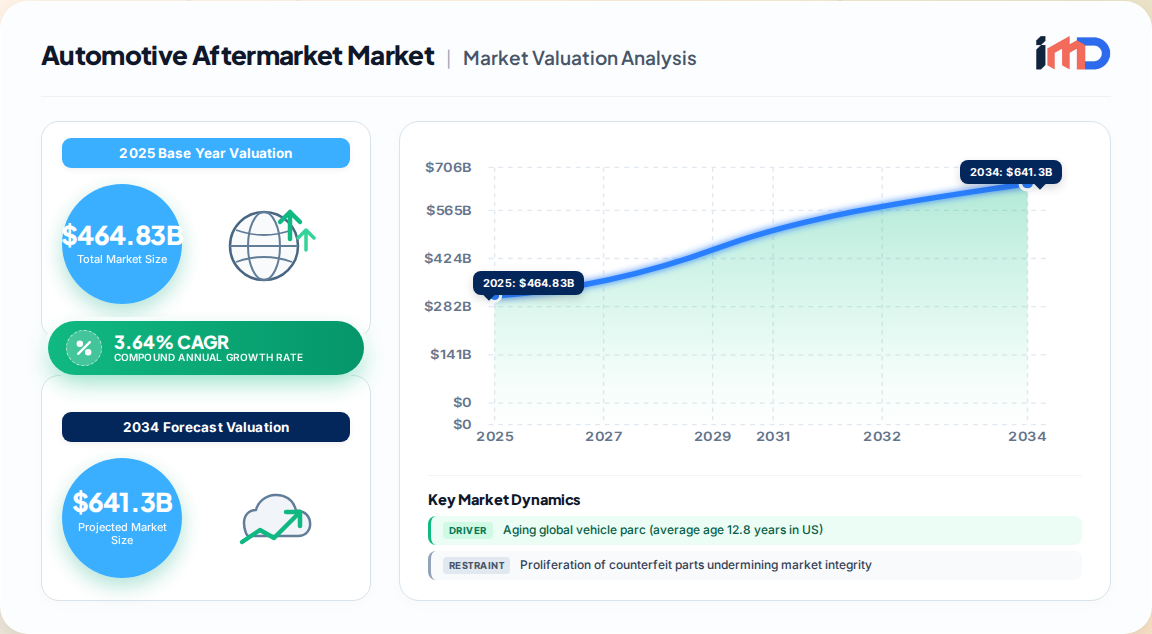
The global automotive aftermarket market is a resilient, mature, and highly fragmented industry that provides replacement parts, accessories, and services for vehicles after their original sale. Our proprietary primary research estimates the market at USD 464.83 billion in 2025, projected to reach USD 555.82 billion by 2030, expanding at a CAGR of 3.64%. This growth is underpinned by an aging global vehicle fleet, the expansion of e-commerce channels, and the increasing technological complexity of vehicles, which drives demand for specialized parts and services.
Automotive Aftermarket Market Market Size (In Billion)
750.0B
600.0B
450.0B
300.0B
150.0B
0
464.8 B
2025
481.8 B
2026
499.3 B
2027
517.5 B
2028
536.3 B
2029
555.8 B
2030
576.0 B
2031
The industry is characterized by a complex distribution ecosystem that has evolved from traditional two-step distribution to a multi-channel model encompassing warehouse distributors, retailers, e-commerce platforms, and direct-to-consumer sales by manufacturers. The United States remains the single largest national market, valued at approximately USD 546 billion in 2024 across light, medium, and heavy-duty vehicles, according to the Auto Care Association. However, Asia-Pacific is the fastest-growing region, accounting for 37.71% of global market share in 2024 and is poised to grow at a CAGR of 3.69% through 2030.
Key Market Drivers & Restraints
The market's trajectory is shaped by a confluence of demographic, technological, and economic factors.
Growth Drivers
Aging Vehicle Parc: The average age of vehicles in operation in the United States reached a record 12.8 years in 2024, and mature European fleets hover around 12 years. Older vehicles require more frequent replacement of wear-and-tear components, providing a stable baseline of demand. This driver adds an estimated 1.2 percentage points to the global CAGR, with the highest impact in North America and Europe.
Expansion of E-Commerce: Online platforms are rapidly gaining share due to SKU breadth, price transparency, and convenience. Online parts sales in the US alone are projected at USD 44.1 billion in 2024 (including marketplaces). This channel contributes approximately 0.8 percentage points to global growth, with Europe and North America leading.
Rising Vehicle Miles Traveled (VMT): Economic expansion and infrastructure development in emerging economies like India and Indonesia are increasing vehicle utilization, accelerating wear on tires, brakes, and filters. This factor adds 0.7 percentage points to the CAGR, primarily in Asia-Pacific.
Fleet Adoption of Predictive Maintenance: Telematics and connected vehicle data enable condition-based maintenance, reducing downtime and creating new revenue streams for service providers. This contributes 0.5 percentage points to growth, concentrated in North America and the EU.
Restraints & Challenges
Proliferation of Counterfeit Parts: The prevalence of counterfeit components, especially brake pads and airbags, undermines consumer trust and brand integrity. This challenge is estimated to shave 0.6 percentage points off the global CAGR, with the highest impact in emerging markets.
EV Powertrain Shift: The transition to electric vehicles reduces demand for traditional engine-related parts (e.g., exhaust systems, spark plugs) while creating demand for battery, thermal management, and high-voltage components. This shift is a net negative for legacy parts providers, dampening growth by 0.4 percentage points, particularly in Europe and China.
OEM Direct-to-Consumer Subscriptions: Automakers are increasingly offering subscription-based parts and service bundles, which could disintermediate independent aftermarket channels. This restraint impacts growth by 0.3 percentage points, notably in North America and Europe.
Talent Deficit: A persistent shortage of qualified technicians, compounded by the need for high-voltage and ADAS calibration skills, constrains service capacity and growth.
Segmentation Analysis
The market is segmented by replacement part, service channel, distribution channel, vehicle type, and geography.
By Replacement Part
Tires dominated with a 21.27% share in 2024, driven by the sheer volume of replacement cycles (212 million passenger tires shipped in the US in 2024). This segment is expected to maintain steady growth.
Electrical Components are the fastest-growing segment, projected at a CAGR of 3.67% through 2030, fueled by the increasing electronic content in modern vehicles (ADAS, infotainment, sensors).
Hard Parts (wear-and-tear items like brake pads, filters) benefit from the aging fleet and represent a significant revenue pool.
By Service Channel
Independent Garages held the largest share at 43.42% in 2024, as out-of-warranty vehicles seek cost-effective service. This channel is expected to remain dominant but face rising competition from specialized chains.
Fleet Maintenance Providers are the fastest-growing channel, with a projected CAGR of 3.76%, as predictive analytics and total cost of ownership (TCO) optimization drive fleet outsourcing.
OE/Authorized Service Centers maintain a significant share but are losing ground in the aftermarket as vehicles age.
By Distribution Channel
Retailers captured 47.61% of the market share in 2024, including auto parts stores, tire retailers, and mass merchants. However, online platforms are advancing at a CAGR of 3.71%, reshaping distribution economics. The rise of omnichannel strategies (click-and-collect, drop-shipping) is a key trend.
By Vehicle Type
Passenger Cars commanded 51.25% of the market share in 2024, driven by their overwhelming share of the global vehicle parc. This segment was valued at USD 323.57 billion in 2024.
Two-Wheelers are forecast to grow at the quickest pace (CAGR of 3.73%), particularly in Asia-Pacific where they represent a primary mode of transport. Commercial vehicles (LCVs and HCVs) are also a critical segment, with demand tied to economic activity and freight volumes.
Regional Outlook
Asia-Pacific: The largest and fastest-growing region, accounting for 37.71% of global market share in 2024, with a CAGR of 3.69%. China, India, and Japan are key markets, driven by an expanding vehicle parc, rising VMT, and increasing e-commerce penetration. China alone was projected to have an aftermarket of USD 188 billion by 2020.
North America: A mature but stable market, with the US aftermarket valued at USD 546 billion in 2024. The region is a hub for technological innovation, with high adoption of predictive maintenance and e-commerce. The average vehicle age and miles traveled support steady demand.
Europe: A mature market with a vehicle fleet of approximately 12 years average age. The region leads in circular economy initiatives and remanufacturing, but faces a faster pace of electrification and ADAS adoption, which could disrupt legacy parts demand.
South America: A growing market, with Brazil and Argentina showing potential. The region is characterized by a high proportion of older vehicles and a growing DIY culture.
Middle East & Africa: A diverse region with significant demand for durable, low-cost parts. The market is fragmented, with a growing influence of e-commerce and independent distributors.
The global automotive aftermarket is highly competitive and fragmented, with a mix of global distributors, regional players, and specialized manufacturers.
Company
Headquarters
Specialization
AutoZone Inc.
USA
Retail distribution, hard parts
O'Reilly Automotive
USA
Retail distribution, hard parts
Genuine Parts Company (NAPA)
USA
Distribution and retail
Advance Auto Parts
USA
Retail distribution
LKQ Corporation
USA
Salvage and recycled parts
Continental AG
Germany
Tires, electronics
Bridgestone Corporation
Japan
Tires
Michelin
France
Tires
Robert Bosch GmbH
Germany
Parts and diagnostics
Denso Corporation
Japan
Parts and electronics
Aisin Seiki
Japan
Parts
Tenneco Inc.
USA
Ride control, emissions
ZF Friedrichshafen AG
Germany
Powertrain, chassis
Magna International
Canada
Parts and systems
3M Company
USA
Accessories and chemicals
The market is medium-concentrated, with the top players holding significant share but facing competition from regional distributors and online platforms. Strategic consolidation, especially among warehouse distributors, continues to reshape the landscape. Companies are also investing in digital capabilities and supply chain efficiency.
Strategic Outlook & Investment Opportunities
Electrification and Hybridization: While a long-term restraint, the shift to EVs creates opportunities in battery diagnostics, thermal management, and high-voltage safety. Aftermarket providers need to develop training programs and specialized tools.
Digitalization: The proliferation of digital influence (USD 77 billion in 2023) and online sales (USD 44.1 billion in 2024) highlights the need for omnichannel strategies. Companies should invest in e-commerce platforms, data analytics, and seamless customer experiences.
Circular Economy: Remanufacturing and recycling of parts is gaining traction, supported by sustainability goals and cost advantages. This is particularly relevant in Europe, where regulatory pressure is high.
Right to Repair: The ongoing debate between OEMs and independent repairers will shape access to diagnostic data and software. Companies should advocate for fair access and develop compatible tools.
AI and Predictive Maintenance: Artificial intelligence is transforming inventory management and fault diagnosis, reducing downtime and improving accuracy. Early adopters can gain a competitive edge.
Import/Export & Supplier Dynamics
Global trade in automotive parts is a critical component of the aftermarket supply chain. The United States is a major importer of parts from Mexico, China, and Germany, while also exporting to Canada and other markets. In 2024, the US replacement tire market was valued at USD 57.7 billion, with significant import volumes.
Major Exporters: Germany, Japan, and China are leading exporters of aftermarket parts. German companies, for example, offer both original and high-quality aftermarket alternatives, with integrated logistics and customs clearance services.
Trade Barriers: Regulations such as India's Quality Control Orders (QCOs) for automotive components add compliance burden for foreign manufacturers. These QCOs mandate BIS certification for wheel rims, safety glass, and fasteners, impacting export costs and lead times.
Supply Chain Risks: The COVID-19 pandemic exposed vulnerabilities in global supply chains, leading to increased focus on regionalization and inventory buffers. The shift to EVs also requires new supply chains for battery components and electronic modules.
Supplier Landscape: A typical German exporter of automotive parts and oils, for instance, supplies a wide range of brands including Mercedes-Benz, BMW, Volkswagen, Bosch, and Continental, offering wholesale supply and logistics services to partners in Vietnam, Brazil, and Singapore. Such intermediaries play a crucial role in connecting manufacturers with global markets.
Value Chain Analysis
The value chain for automotive aftermarket parts involves several stages:
Manufacturing: Original Equipment Manufacturers (OEMs) and aftermarket manufacturers produce parts. Increasingly, 3D printing is being used for low-volume or obsolete parts.
Distribution: Warehouse distributors (WDs) buy in bulk and supply to retailers and jobbers. The traditional two-step model has given way to multiple channels, including direct-to-consumer and e-commerce drop-shipping.
Retail/Service: Auto parts stores, tire retailers, and independent garages sell to consumers and perform services. Online marketplaces like Amazon and eBay are increasingly important, accounting for USD 21.8 billion in US aftermarket sales in 2024.
End Consumer: DIY (Do-It-Yourself) and DIFM (Do-It-For-Me) are the two primary consumer segments. DIFM dominates, but DIY remains significant for basic maintenance.
Strategic White-Space Analysis
Specialized EV Kits: There is a clear gap in the market for comprehensive EV maintenance kits, including high-voltage gloves, insulated tools, and battery diagnostic software.
ADAS Calibration Services: As ADAS features become standard, there is a growing need for calibration services. Independent shops often lack the equipment and training, presenting an opportunity for specialized service providers.
Over-the-Air (OTA) Update Solutions: As vehicles become software-defined, aftermarket providers can offer OTA update management and cybersecurity solutions.
Subscription-Based Maintenance: For fleet operators, subscription models that bundle predictive maintenance, parts, and service can create recurring revenue streams.
Circular Economy Platforms: Online marketplaces for remanufactured and recycled parts can capitalize on sustainability trends and cost-conscious consumers.
Table 50: Saudi Arabia Automotive Aftermarket Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: South Africa Automotive Aftermarket Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the automotive aftermarket market?
Our proprietary research estimates the global automotive aftermarket market at **USD 464.83 billion in 2025**, projected to reach **USD 555.82 billion by 2030**, growing at a **CAGR of 3.64%**.
2Which region dominates the automotive aftermarket market?
Asia-Pacific is the largest and fastest-growing region, accounting for **37.71% of the global market share in 2024** and expected to grow at a **CAGR of 3.69%** through 2030, driven by an expanding vehicle fleet and rising vehicle miles traveled.
3What are the key drivers of the automotive aftermarket market?
The primary drivers include an aging global vehicle fleet (average age of 12.8 years in the US), expansion of e-commerce channels, rising vehicle miles traveled in emerging economies, and the adoption of predictive maintenance analytics by fleets.
4Which companies are leading the automotive aftermarket market?
Major players include AutoZone, O'Reilly Automotive, Genuine Parts Company (NAPA), Advance Auto Parts, LKQ Corporation, Continental AG, Bridgestone, Michelin, Robert Bosch, and Denso Corporation.
5How is the automotive aftermarket market segmented?
The market is segmented by replacement part (tires, batteries, brake pads, filters, etc.), service channel (independent garages, OE service centers, fleet maintenance), distribution channel (retailers, online platforms), and vehicle type (passenger cars, commercial vehicles, two-wheelers).
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of our data collection effort. We conduct in-depth interviews with procurement directors at warehouse distributors, operations managers at independent repair chains, e-commerce category managers for automotive parts, supply chain heads at Tier-1 parts manufacturers, and fleet maintenance supervisors.
We interview senior executives (C-suite and VPs), aftermarket category managers, diagnostic technicians and master mechanics, and regulatory affairs specialists to capture both strategic and operational insights.
We gather quantitative data on SKU-level sales volumes, inventory turnover rates, service bay utilization, and average repair order values to build our bottom-up market model.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
35%
Operations Manager
25%
Category Manager
20%
Supply Chain Head
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Warehouse Distributors
30%
Independent Repair Shops
25%
Tier-1 Parts Manufacturers
20%
E-commerce Platforms
15%
Fleet Operators
10%
Secondary Research & Industry Benchmarking
Secondary research constitutes 20-30% of our methodology, drawing from official sources such as the Auto Care Association, Specialty Equipment Market Association (SEMA), American Automotive Policy Council, and European Automobile Manufacturers' Association (ACEA).
We benchmark against government trade statistics (UN Comtrade, US ITC, Eurostat) and non-profit technical standards bodies (SAE International, ISO) to validate import/export flows and technology adoption rates. All sources are official .gov, .org, or recognized non-profit trade associations; no commercial market research firms are cited.
We utilize financial databases including Bloomberg, Factiva, Hoovers, and PitchBook to analyze company financials, M&A activity, and investment trends.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously. The bottom-up approach aggregates demand from vehicle registrations by age cohort, average annual miles driven, parts failure rates by component, and average replacement cost. The top-down approach reconciles with GDP growth, vehicle parc expansion, and aftermarket revenue disclosures from public companies.
We validate our estimates through multi-level data triangulation, cross-referencing primary interviews with trade association data and financial disclosures. Our model is updated quarterly to reflect the latest market dynamics.
Data Accuracy & Quality Check
Our proprietary process guarantees an estimated data accuracy level of 85-90%. All data points are subjected to rigorous sanity checks, outlier detection, and reconciliation with historical trends.
Every report is updated to the date of purchase, ensuring that clients receive the most current market intelligence, including the latest quarterly earnings, new product launches, and regulatory changes.
Related Reports
Automotive chemicals market valued at $70.1 billion in 2025, growing at 5.2% CAGR to $112.1 billion by 2034, driven by EV thermal fluids and synthetic lubricants.
Nov 2026|276 pages
$2900.00
Kids scooter market to reach US$ 8.80 Billion by 2034 at 4.7% CAGR from US$ 5.53 Billion in 2024. Kick scooters lead with 87.4% share; Europe dominates globally.
Nov 2026|242 pages
$2900.00
The Electric Vehicle Magnets Market is valued at USD 2.74 Billion in 2025 and is projected to reach USD 11.63 Billion by 2033, growing at a CAGR of 19.8%.
Nov 2026|180 pages
$2900.00
The global automobile weather strip market is valued at $8.6 Billion in 2025, growing at a 3.5% CAGR to reach $12.1 Billion by 2035, driven by EV adoption and comfort demand.