1What is the automotive chemicals market size in 2025?
Our proprietary modeling values the global automotive chemicals market at approximately $70.1 billion in 2025, with lubricants contributing the largest share at 38.2% of total revenue.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Automotive Chemicals Market
 by Product Type (Lubricants(Engine Oil, Gear Oil, Greases, Penetration Lubricants, Dry Lubricants), Functional Fluids(Coolants, Brake Fluids, Transmission Fluids), Specialty Chemicals, Additives(Fuel Additives, Performance Additives), Cleaners, Material Plastics(Polyurethane, Polyvinyl Chloride, Acrylonitrile Butadiene Styrene, Polystyrene, Polyethylene, Polyoxymethylene), Coatings(Ceramic, Paint Coating, Paint Sealant, Wax, Polymer Coatings, Graphene), Adhesives(Structural, Non-Structural, Heat-Cured, Room Temperature-Cured), Cleaning Products(Waxes, Polishes, Vinyl Protectants)), by Application (Engine Components, Transmission Fluids, Fuel Additives, Coatings, Interior/Exterior Cleaning, Two-Wheelers, Passenger Vehicles, Light Commercial Vehicles, Heavy Commercial Vehicles), by End-use (OEM, Aftermarket, Recycling), by Sales Channel (OEMs, Aftermarket), by Asia Pacific (China, India, Japan, South Korea, Thailand, Indonesia, Vietnam), by Europe (Germany, UK, France, Italy, Spain), by North America (USA, Canada, Mexico), by Latin America (Brazil, Argentina), by Middle East & Africa Forecast 2026-2034


Research Analyst
 Related Reports

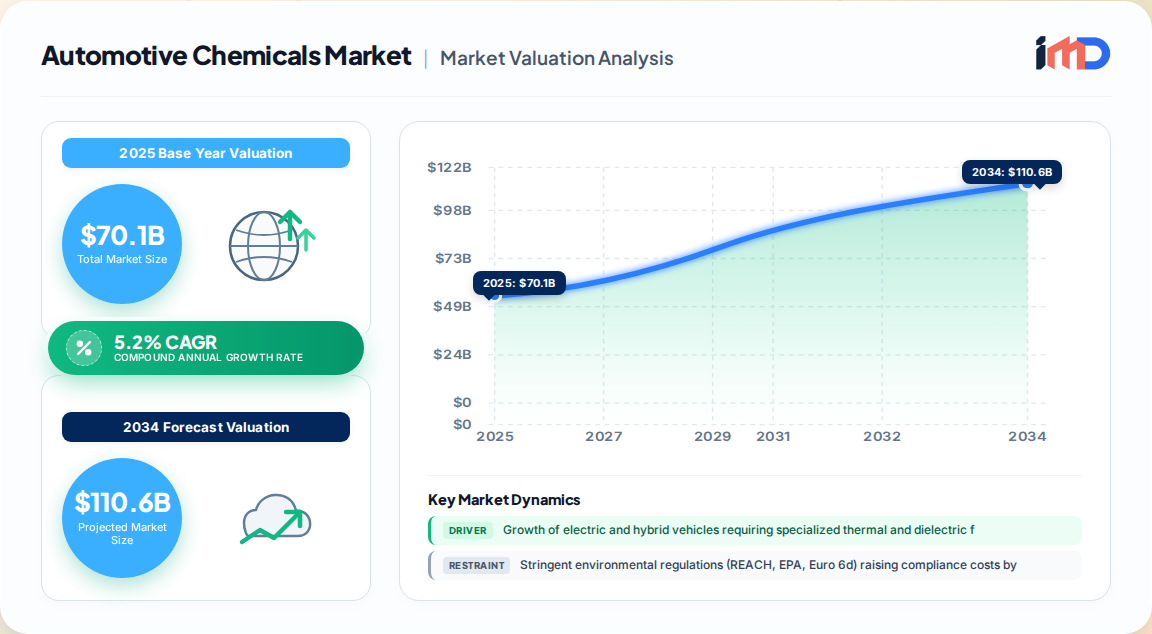
The global automotive chemicals market is being fundamentally re-priced rather than merely expanded. Our proprietary bottom-up modeling places the market at $70.1 billion in 2025, on a trajectory to $112.1 billion by 2034, implying a 5.2% CAGR across the forecast window. This is not a uniform expansion: the growth is concentrated in fluids engineered for electrified powertrains, high-performance synthetic lubricants, and low-VOC appearance and coating chemistries.
The structural story is one of substitution. Traditional internal combustion engine (ICE) fluid volumes (engine oils, transmission fluids, exhaust after-treatment reagents) face secular volume erosion per vehicle, while battery thermal management fluids, dielectric coolants, and electric-motor bearing lubricants expand at double-digit rates per vehicle. The net effect is a market that grows in value faster than in volume.
| Metric | 2025 | 2034 | CAGR |
|---|---|---|---|
| Global market value | $70.1 billion | $112.1 billion | 5.2% |
| Lubricants share of revenue | 38.2% | Declining | - |
| Asia Pacific revenue share | 42.5% | Stable | - |
| Europe revenue share | 28.3% | Stable | - |
| North America revenue share | 19.2% | Stable | - |
Lubricants remain the anchor category at 38.2% of total revenue, but the fastest value accretion is occurring in functional fluids and specialty additives. The aftermarket channel, buoyed by an ageing global vehicle parc and extended maintenance intervals, continues to underwrite volume stability even as OEM demand shifts toward higher-specification, lower-volume formulations.
Five drivers dominate our demand decomposition, and they are not equally weighted.
Regulatory stringency is the single largest constraint, and it is asymmetric in its impact.
Our segmentation reveals a clear hierarchy of scale versus momentum.
| Segment | Position | Share or Growth Note |
|---|---|---|
| Engine oils (lubricants) | Largest | ~38–43% of revenue; synthetic adoption accelerating |
| Functional fluids | Core | Coolants, brake fluids, transmission fluids; EV thermal variants growing fast |
| Additives | Fastest-growing type | Fuel additives and performance packages growing above market average |
| Coatings | Fastest-growing application | Ceramic and polymer coatings growing ~12% in key detailing channels |
| Engine components | Largest application | ~35% of application revenue; 50% of application value from passenger and commercial vehicles |
| Fuel additives | Fastest application growth | Emissions and efficiency driven, ~10% sales growth in passenger cars |
| Aftermarket | Largest end-use | ~55% share; OEM holds ~61% in alternate segmentations, reflecting methodological scope differences |
| Two-wheelers | High-volume application | ~71% share where two-wheeler weighting is applied, reflecting Asian mobility patterns |
The divergence between 'largest' and 'fastest' is the core investment insight: incumbency sits in engine oils, but incremental growth pools sit in additives, coatings, and EV-specific fluids.
Asia Pacific commands 42.5% of global revenue (~$29.8 billion in 2025), reflecting its position as the world's largest vehicle manufacturing hub, with China, India, and Japan collectively accounting for over half of global vehicle production. China's production base of roughly 27 million units annually and India's production of approximately 22.9 million units anchor regional demand.
Europe holds 28.3% share, driven less by volume than by formulation sophistication. Euro 6d compliance, a battery-electric share of new sales near 15.8%, and proximity to major OEM engineering centers give European chemical suppliers outsized influence over global specifications.
North America accounts for 19.2%, supported by high vehicle ownership density, EPA and CARB-driven innovation, and a mature aftermarket distribution network. Latin America (6.8%) and Middle East & Africa (3.2%) represent the expansion frontier as vehicle populations grow and fleet operators prioritize extended equipment life.
Automotive chemicals trade flows reflect the underlying vehicle production geography. Asia Pacific is the dominant net exporter of finished lubricants and additive packages, while Europe and North America are net exporters of high-value specialty chemistries and additive concentrates but net importers of commodity base oils and commodity coolants.
| Flow Characteristic | Asia Pacific | Europe | North America |
|---|---|---|---|
| Finished lubricants | Net exporter | Balanced | Balanced |
| Additive packages | Growing exporter | Net exporter | Net exporter |
| Base oils | Mixed | Net importer | Balanced |
| EV thermal fluids | Emerging exporter | Net exporter | Net exporter |
| Appearance chemicals | Net exporter | Balanced | Net exporter |
Supplier concentration is moderate. Vertically integrated petrochemical majors control base oil and additive intermediate supply, while formulators and blenders occupy the mid-chain. Regional chemical distributors and private-label manufacturers, including EU-based producers serving household and automotive/technical chemical categories under ISO 9001 and ISO 14001 systems, provide flexible assortment to distributors and retail chains. Origin documentation and EU Ecolabel-type certification are increasingly procurement prerequisites for cross-border supply into Europe.
The value chain is characterized by a pronounced margin gradient that favors additive and specialty chemistry positions.
The strategic implication is clear: firms that own additive formulation technology and OEM specification approvals capture disproportionate margin, while pure blenders face commoditization risk as synthetic base oil access widens.
The market is moderately concentrated at the top and fragmented at the base. Vertically integrated chemical majors with proprietary additive technology and global OEM relationships lead, while appearance chemicals and private-label automotive technical chemicals remain fragmented with low concentration.
Key players include BASF, Dow, ExxonMobil, Shell, 3M, Chevron, LyondellBasell, Eastman Chemical, Huntsman Corporation, LIQUI MOLY GmbH, ITW Global Brands, Valvoline, and Tetrosyl Ltd.
Strategic developments worth tracking:
Three under-served opportunities stand out for investors and strategics:
The automotive chemicals market through 2034 will reward portfolios weighted toward additive technology, EV-specific fluids, and certified sustainable chemistry, while exposing commodity blenders to margin compression. Growth of 5.2% CAGR to $112.1 billion is achievable, but only for participants positioned on the correct side of the electrification and compliance divide.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.2% from 2020-2034 |
| Segmentation |
|
By Application
By End-use
By Sales Channel
| By Geography |
|
Our proprietary modeling values the global automotive chemicals market at approximately $70.1 billion in 2025, with lubricants contributing the largest share at 38.2% of total revenue.
The market is projected to expand at a 5.2% CAGR from 2026 to 2034, reaching roughly $112.1 billion by the end of the forecast period.
Asia Pacific leads with 42.5% of global revenue, valued at approximately $29.8 billion in 2025, driven by China, India, and Japan accounting for over half of global vehicle production.
Additives are the fastest-growing product type and coatings the fastest-growing application, with ceramic and polymer car coatings expanding at roughly 12% annually in detailing channels.
EVs require dielectric coolants, battery thermal management fluids, and electric-motor lubricants rated for 10,000 to 20,000 RPM. With EVs projected to reach 35% of new vehicle sales by 2034, these specialty fluids represent the market's most significant incremental growth pool.
Key participants include BASF, Dow, ExxonMobil, Shell, 3M, Chevron, LyondellBasell, Eastman Chemical, Huntsman Corporation, LIQUI MOLY GmbH, ITW Global Brands, Valvoline, and Tetrosyl Ltd.
Synthetic and semi-synthetic lubricants deliver extended drain intervals, superior thermal stability, and better protection in modern ICE and hybrid powertrains, supporting premium pricing even where overall fluid volumes remain flat.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Lubricant Formulation Chemist | 27% |
| Aftermarket Category Manager | 24% |
| Regulatory Compliance Lead | 19% |
| Company Type | Representation (%) |
|---|---|
| Additive & Specialty Chemical Formulators | 32% |
| Base Oil, Glycol & Intermediate Suppliers | 21% |
| OEM Fluid Specification & Engineering Teams | 18% |
| Aftermarket Distributors & Private-Label Blenders | 19% |
| Recycling & Re-Refining Operators | 10% |