1What is the current size of the automobile weather strip market?
The global automobile weather strip market was valued at $8.6 billion in 2025 and is projected to reach $12.1 billion by 2035, growing at a CAGR of 3.5%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Automobile Weather Strip Insightful Market
 by Material Type (EPDM Rubber, PVC Rubber, Thermoplastic Elastomer/Rubber (TPE)), by Product Type (Doorframe, Windows, Roof Rail, Windshield, Trunk, Hood), by Application (Passenger Cars, Commercial Vehicles, Electric Vehicles, Two-Wheelers), by Sales Channel (OEM, Aftermarket), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain, Rest of Europe), by Asia-Pacific (China, Japan, South Korea, India, Australia, Rest of Asia-Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of Middle East & Africa) Forecast 2026-2034
Research Analyst


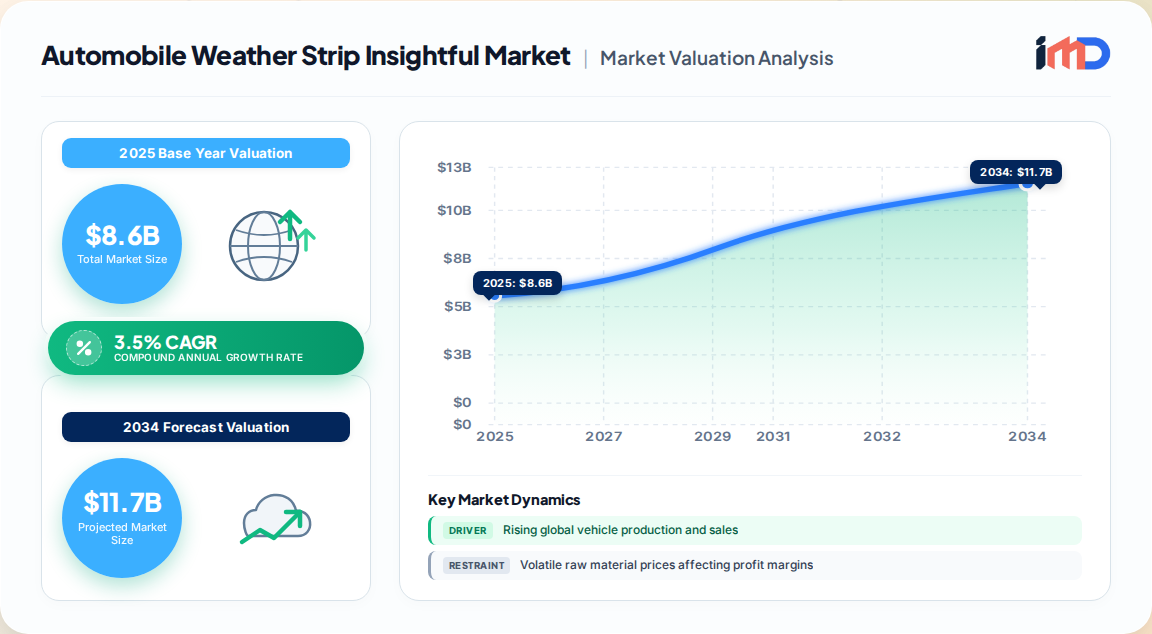
The global automobile weather strip market represents a mature yet resilient segment of the automotive supply chain. Our proprietary primary research estimates the market at $8.6 billion in 2025, with a projected compound annual growth rate (CAGR) of 3.5% from 2026 to 2035, reaching approximately $12.1 billion by the end of the forecast period. This growth is not merely a function of rising vehicle production volumes—global motor vehicle output surpassed 96.4 million units in 2025 according to international trade association data—but is increasingly driven by content-per-vehicle escalation. As vehicles become quieter, more electrified, and more tightly sealed for thermal efficiency, the weather strip evolves from a simple rubber gasket into a sophisticated acoustic and aerodynamic system.
Key market dynamics reveal a bifurcated landscape. On one hand, the OEM channel demands ever-higher performance for sealing against wind noise (critical in EVs), water ingress, and dust, while simultaneously pressing suppliers on cost and weight. On the other, the aftermarket is experiencing steady replacement demand as aging vehicle fleets in mature markets require maintenance. The material mix is shifting gradually but perceptibly. EPDM rubber remains the workhorse, commanding over 38% of material share, but thermoplastic elastomers (TPE) and thermoplastic vulcanizates (TPV) are gaining ground due to their recyclability and lighter weight. Meanwhile, sustainability mandates are pushing manufacturers to incorporate recycled content—pioneering efforts have demonstrated weather strips with 20% recycled rubber, a signal of the circular economy's arrival in this niche.
The expansion of the automobile weather strip market is propelled by four principal drivers, each with distinct regional nuances:
However, the market faces notable restraints:
The market is segmented along four primary axes, each revealing distinct growth patterns and strategic imperatives.
| Segment | Dominant Sub-segment (2025) | Market Share (%) | Fastest-Growing Sub-segment | Key Insight |
|---|---|---|---|---|
| Material Type | EPDM Rubber | ~38% | TPE/TPV | EPDM's proven weathering and compression-set resistance maintain dominance, but TPE gains from recyclability and design freedom. |
| Product Type | Doorframe Weather Strips | ~63% | Window Weather Strips | Doorframes require multiple seals per opening, driving volume; window seals benefit from acoustic and thermal demands, especially in EVs. |
| Application | Passenger Vehicles | ~75% | Commercial Vehicles | Passenger cars dominate volume; commercial vehicles (LCVs/HCVs) show faster growth due to fleet expansion and aftermarket needs. |
| Sales Channel | OEM | ~80% | Aftermarket | OEMs dictate specifications and design integration; aftermarket grows with vehicle parc aging, particularly in North America and Europe. |
Material Deep-Dive: EPDM remains the material of choice for its excellent resistance to UV, ozone, and temperature extremes. However, TPE (including TPV) is gaining traction because it is lighter, fully recyclable, and can be processed on standard thermoplastic equipment, reducing cycle times. The shift is gradual but directional; suppliers that offer both material families are best positioned to serve diverse OEM requirements.
Product Deep-Dive: Doorframe weather strips are the largest product category, as each door aperture requires an upper seal, a lower seal, and often an auxiliary seal. Window weather strips (beltline seals, glass run channels) are the fastest-growing, driven by the need for tighter sealing in EVs and the integration of sensors and cameras that require clean glass surfaces.
Asia-Pacific commands the largest share of the global automobile weather strip market, estimated at 41% in 2025, valued at approximately $3.5 billion. The region's dominance is underpinned by China's massive vehicle production—over 30 million units annually—and the rapid expansion of EV manufacturing. China alone is projected to grow at a CAGR of 5.1%, reaching a market size of $2.8 billion by 2035.
North America, led by the United States, represents a mature but high-value market. The U.S. market alone was valued at $3.2 billion in 2025, driven by a strong automotive manufacturing base and a preference for larger vehicles (SUVs, pickups) that require more extensive sealing. The aftermarket is also robust, with a large vehicle parc necessitating replacement parts.
Europe is characterized by stringent regulatory standards and a high penetration of premium vehicles. The region is a hub for innovation in sustainable materials, with OEMs actively seeking weather strips made from bio-based or recycled rubber. Germany remains the largest European market, followed by France and the UK.
South America and the Middle East & Africa are smaller but growing markets, with expansion tied to economic development, urbanization, and increasing vehicle ownership. Local production is limited, so these regions rely heavily on imports, creating opportunities for global suppliers with established distribution networks.
The automobile weather strip market is moderately concentrated, with a handful of global players accounting for a significant share of OEM contracts. Our primary research identifies the following leading suppliers:
Recent strategic developments indicate a clear focus on sustainability, lightweighting, and acoustic performance:
These initiatives reflect a broader trend: weather strip suppliers are transitioning from component manufacturers to system integrators, offering design, simulation, and validation services to OEMs to secure long-term contracts.
The automobile weather strip value chain is characterized by tight integration between material suppliers, extruders, and OEMs. The upstream segment is dominated by chemical and rubber compounders who supply EPDM, TPE, and other elastomers. Prices for these raw materials are subject to volatility, influenced by oil prices, supply chain disruptions, and environmental regulations.
Midstream, weather strip manufacturers operate extrusion lines, often co-located with OEM assembly plants or in dedicated industrial parks. They provide just-in-sequence delivery to minimize inventory costs. The extrusion process is capital-intensive, requiring precision dies and curing systems (for rubber) or precise temperature control (for thermoplastics).
Downstream, OEMs integrate weather strips into door modules, window frames, and trunk lids. The aftermarket channel involves distributors, retailers, and independent repair shops, with demand driven by vehicle age and environmental conditions.
Trade data from the World Bank's WITS database indicates that global trade in rubber and plastic seals (HS codes 4016 and 3926) is substantial, with major exporters including Germany, China, Japan, and the United States. However, weather strips are often supplied regionally to reduce logistics costs and lead times, making the market less dependent on global trade flows than other automotive components.
Our analysis identifies several white-space opportunities:
For procurement, automakers should consider dual-sourcing strategies to mitigate supply chain risks, particularly for EPDM-based strips, which are subject to material price volatility. Early engagement with suppliers on design and material selection can also yield cost savings and performance improvements.
The automobile weather strip market will continue to grow steadily, but stakeholders must navigate several challenges:
Despite these challenges, the long-term outlook remains positive, driven by vehicle production growth, electrification, and the relentless pursuit of cabin comfort and efficiency.
While weather strips are often produced close to assembly plants, global trade in weather strip components (including extruded profiles and specialized seals) is significant. According to UN Comtrade data, global exports of rubber weather strips (HS 401693) exceeded $4.5 billion in 2024, with China, Germany, and the United States as leading exporters. China's export value alone was over $1.2 billion, reflecting its role as a manufacturing hub for both domestic and international OEMs.
Major supplier clusters are located in:
Importing regions include North America and Europe, where demand exceeds local production for certain specialty seals. However, the overall market is less globally integrated than other automotive components due to the bulky nature of weather strips and the benefits of local supply.
The global automobile weather strip market is a stable, innovation-driven segment poised for measured growth. The interplay of electrification, sustainability, and comfort demands will reshape material choices and product designs. Suppliers that invest in acoustic technology, sustainable materials, and agile manufacturing will be best positioned to capture value. With a CAGR of 3.5% and a projected market size of $12.1 billion by 2035, the industry offers attractive opportunities for incumbents and new entrants alike, provided they navigate the challenges of cost, regulation, and technological change.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.5% from 2020-2034 |
| Segmentation |
|
By Application
By Sales Channel
| By Geography |
|
The global automobile weather strip market was valued at $8.6 billion in 2025 and is projected to reach $12.1 billion by 2035, growing at a CAGR of 3.5%.
Asia-Pacific holds the largest share, accounting for approximately 41% of the global market in 2025, driven by high vehicle production in China and other emerging economies.
Key drivers include rising global vehicle production, increasing electric vehicle adoption (which demands superior acoustic insulation), stringent regulatory standards for noise and emissions, and growing consumer focus on comfort.
EPDM rubber is the most widely used material, holding over 38% of the market share, due to its durability and weather resistance. Thermoplastic elastomers (TPE) are the fastest-growing segment, favored for their recyclability and lighter weight.
Leading companies include Hutchinson, Cooper Standard, Toyoda Gosei, Dura Automotive Systems, Vibracoustic, Nihon Plast, KACO, Sika AG, and Saint-Gobain, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Senior Material Engineer | 25% |
| Product Manager - Sealing Systems | 20% |
| R&D Head | 15% |
| Supply Chain Manager | 10% |
| Company Type | Representation (%) |
|---|---|
| Tier-1 Automotive Suppliers | 40% |
| Rubber & Elastomer Compounders | 25% |
| OEM Procurement & Engineering Teams | 20% |
| Aftermarket Distributors & Retailers | 10% |
| Independent Testing & Certification Bodies | 5% |
 Related Reports
