Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Furniture Industry Market Size, Trends & Forecast to 2033
Furniture Industry
Home and Property Improvement / MARKET REPORT
Furniture Industry | Insight Market Data
Furniture Industry by Product (Bedroom Furniture, Storage Furniture, Seating Furniture, Living Room Furniture, Kitchen & Dining Furniture, Outdoor Furniture, Home Office Furniture, Lamps & Lighting, Home Décor, Baby & Children's Furniture), by Material (Wood, Metal, Plastic, Glass), by Application (Residential, Commercial, Institutional), by Price Range (Economy, Mid-Range, Premium), by Distribution Channel (B2C/Retail, B2B/Project), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, Indonesia, Vietnam), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, Turkey) Forecast 2026-2034
The Magic Carpet Ski Lifts Market is valued at 312 Million in 2025 and is projected to reach 512 Million by 2032, growing at a CAGR of 7.3%.
Nov 2026|263 pages
$2900.00
Global lawn mower blade market to reach $4.6B by 2034 at 5.67% CAGR. Explore blade type, material, end-user and regional trends shaping demand.
Nov 2026|209 pages
$2900.00
Global second hand office furniture market to grow at 5.8% CAGR through 2031, driven by circular policies, corporate decommissioning, and online resale.
Nov 2026|254 pages
$2900.00
Indonesia furniture market to reach USD 15.2 Billion by 2034 at 5.82% CAGR. Explore trends, segmentation, trade dynamics, and competitive landscape.
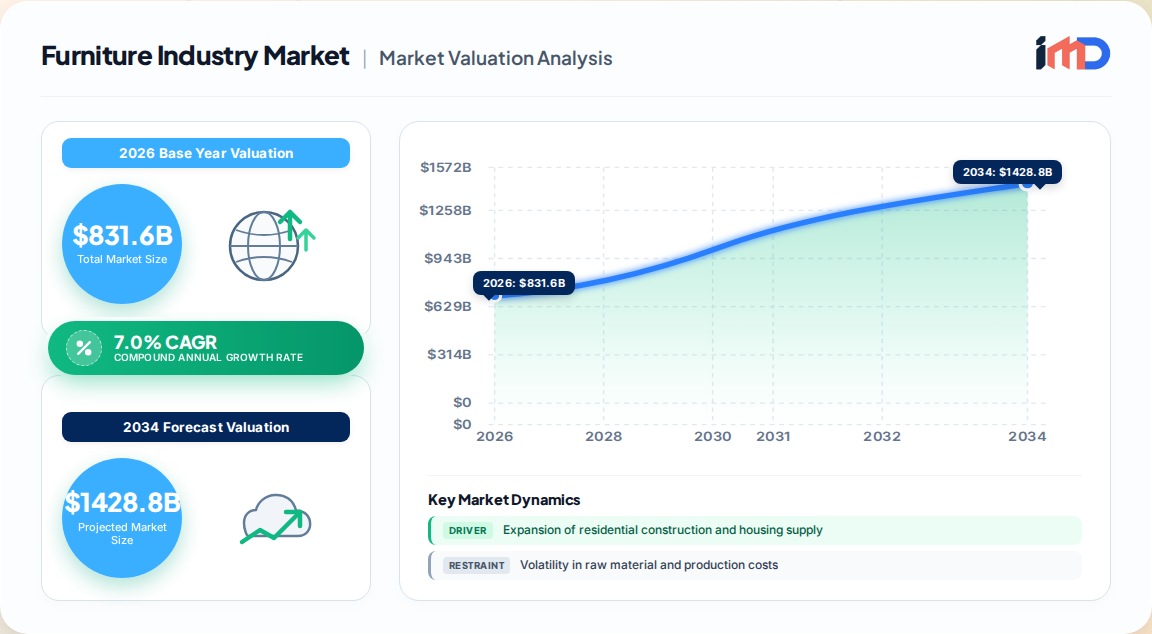
The global furniture industry market is undergoing a structural transformation, evolving from a traditional, craft-driven sector into a sophisticated, technology-enabled global ecosystem. Our proprietary primary research estimates the market at $831.6 billion in 2026, on a definitive trajectory to reach $1,334.1 billion by 2033, expanding at a robust CAGR of 7.0%. This growth is not merely a post-pandemic rebound; it is a fundamental re-rating of the sector, driven by unprecedented urbanization, the emergence of the home as a multi-functional hub, and the digitalization of a historically offline purchase journey. Asia-Pacific commands the market with a 38.5% revenue share in 2025, and is also the fastest-growing region, underlining the geographic shift in both production and consumption.
Furniture Industry Market Size (In Billion)
1000.0B
800.0B
600.0B
400.0B
200.0B
0
777.2 B
2025
831.6 B
2026
889.8 B
2027
952.1 B
2028
1.019 M
2029
1.090 M
2030
1.166 M
2031
Market Dynamics: Drivers, Restraints, and the New Demand Paradigm
The market's expansion is anchored by a confluence of macroeconomic and behavioral forces, yet it faces persistent headwinds that are reshaping competitive strategies.
Key Growth Drivers:
Residential Construction and Housing Supply: Government-backed housing programs, particularly in emerging economies, are creating a massive pipeline of newly furnished spaces. For example, Saudi Arabia's Vision 2030 housing program has driven homeownership from 47.0% in 2016 to over 60.0% in 2025, with over 107,000 housing units provided in 2025 alone, generating substantial downstream demand for bedroom, living room, and storage furniture.
Urbanization and Space Optimization: With 58% of the global population living in urban areas in 2025, the demand for space-saving, modular, and multifunctional furniture is accelerating. This is especially pronounced in Asia-Pacific, where compact living environments necessitate innovative design solutions.
Digital-First D2C Brands and Omnichannel Penetration: The rise of direct-to-consumer furniture brands is fundamentally altering retail dynamics. In India, for instance, digital-first players like Wakefit reported 24% furniture-category growth in FY26, with online channels generating 52.7% of company revenue, demonstrating the viability of a blended online-offline model.
Remote and Hybrid Work: The normalization of hybrid work has spurred demand for ergonomic home office furniture, with the home office segment projected to grow at a notable CAGR of 7.02% over the forecast period.
Key Restraints:
Raw Material and Production Cost Volatility: Fluctuations in the prices of timber, metals, polyurethane foam, and specialty textiles continue to squeeze manufacturer margins. The competitive pricing environment limits the ability to fully pass on these costs to consumers.
Supply Chain Fragility: The industry remains exposed to logistics disruptions, ocean freight volatility, and trade protectionist measures, which create market distortions and increase operational complexity.
Intense Fragmentation: The market's low-to-medium concentration, with a long tail of SMEs, intensifies price competition and limits economies of scale for smaller players.
Product and Material Segmentation: The Battle for Share
Our analysis reveals a market where traditional categories maintain dominance, but innovation is shifting the growth frontier. The following table summarizes the key segment shares and growth indicators.
Segment Category
Dominant Segment
2025/2026 Share
Fastest-Growing Segment
Forecast CAGR
By Product
Bedroom Furniture
35.7% (2025)
Home Office Furniture
7.02%
By Material
Wood
39.8% (2025) / 51.31% (2026)
Metal
7.38%
By Application
Residential
61.3% (2025) / 62.34% (2026)
Office Furniture
7.02%
By Price Range
Mid-Range
53.83% (2026)
Premium
6.73%
By Distribution
B2C/Retail
78.95% (2026)
B2B/Project
7.89%
Product Insights: Bedroom furniture remains the largest product category, driven by the fundamental need for beds, mattresses, and storage. However, the home office segment is the standout growth story. The architectural shift toward hybrid work has made ergonomic desks, chairs, and storage solutions a priority, with consumers increasingly treating home office furniture as an investment in productivity and well-being.
Material Insights: Wood continues to dominate, favored for its aesthetic warmth, durability, and sustainability credentials. However, metal furniture is growing at a faster clip (7.38% CAGR), driven by its durability, affordability, and suitability for modern, industrial, and minimalist designs. The push for sustainability is also driving interest in recycled and bio-based materials, with corporate ESG mandates acting as a catalyst.
Application Insights: The residential segment is the bedrock of the market, accounting for over 60% of revenue. This is propelled by home remodeling, millennial homeownership, and the psychological importance of the home as a sanctuary. The commercial segment, while smaller, is accelerating due to office reconfigurations for hybrid work, hospitality sector recovery, and institutional procurement (healthcare, education).
Regional Outlook: Asia-Pacific's Ascendancy and Beyond
Asia-Pacific is the undisputed engine of growth, accounting for 38.5% of global revenue in 2025 and expected to contribute 46.1% of incremental growth through 2030. The region benefits from rapid urbanization, a large manufacturing base, and rising disposable incomes. China alone is forecast to grow at a CAGR of 8.2% from 2026 to 2033. The region's dominance is not only in consumption but also in production, with China being the largest furniture exporter to the EU, accounting for over half of total EU furniture imports.
Furniture Industry Regional Market Share
Loading chart...
North America represents a mature but resilient market. The U.S. is the largest single country market, with revenue projected at $249.5 billion in 2026. Growth here is driven by home remodeling activity, particularly among millennials, and the rapid adoption of e-commerce. Corporate ESG mandates are also pushing demand for sustainable and circular furniture solutions.
Europe is characterized by its high-end design leadership and strong sustainability focus. The EU furniture industry employs around 1 million workers across 130,000 companies, generating an annual turnover of approximately €96 billion. The region is a global leader in the high-end segment, producing nearly two out of every three high-end furniture products sold worldwide. However, the sector faces intense competition from low-cost countries and higher operational costs due to stringent environmental and technical standards.
Middle East & Africa is emerging as a strategic growth frontier, underpinned by government-led housing and infrastructure programs. Saudi Arabia's Vision 2030 and the UAE's construction pipeline are creating significant opportunities for furniture suppliers, particularly in the hospitality, residential, and commercial fit-out segments.
South America offers niche opportunities, with Brazil and Argentina showing potential for growth, though political and economic volatility remains a challenge.
Value Chain Analysis: From Forest to Living Room
The furniture value chain is complex, multi-tiered, and increasingly globalized. Understanding its dynamics is critical for identifying margin capture points and risk mitigation strategies.
Upstream: Raw Material Extraction and Processing
Key inputs include timber, metals (steel, aluminum), plastics, foam, textiles, and glass.
Sustainability certification (e.g., FSC) is becoming a non-negotiable requirement for accessing premium markets.
Volatility in commodity prices directly impacts manufacturer profitability.
Midstream: Manufacturing and Assembly
Dominated by SMEs, the manufacturing stage is labor-intensive but increasingly automating (CNC routing, robotic assembly).
Production hubs in China, Vietnam, and Eastern Europe are critical for global supply.
The debate between mass production and on-demand manufacturing is intensifying, with on-demand models offering customization but facing last-mile delivery challenges.
Downstream: Distribution and Retail
The channel landscape is shifting from offline-only to omnichannel. B2C/retail accounts for 78.95% of the market, but B2B/project sales are growing faster at 7.89%.
Omnichannel strategies that integrate digital discovery with physical showrooms are winning. Augmented reality (AR) tools are bridging the online-offline gap.
Last-mile delivery and assembly remain significant cost and customer experience pain points.
Import/Export & Supplier Dynamics
The furniture trade is characterized by distinct flows from manufacturing hubs to consumption centers. China is the world's largest furniture exporter, with a significant share of its output destined for the U.S. and EU markets. Vietnam has emerged as a major alternative manufacturing base, benefiting from trade diversification. Poland and Italy are key suppliers within Europe, with Italy dominating the high-end design segment.
On the import side, the United States is the largest single-country importer, absorbing furniture from Asia and Europe. The EU is a major net importer, with China accounting for over half of its furniture imports. Trade policy, including tariffs and anti-dumping duties, is a critical variable affecting supplier dynamics and pricing. For instance, U.S. tariffs on Chinese goods have accelerated the shift of production to Vietnam, Thailand, and Mexico.
Supplier relationships are evolving from transactional to strategic partnerships. Large retailers are increasingly demanding supply chain transparency, ethical sourcing, and rapid replenishment capabilities. This favors suppliers with vertical integration and advanced logistics management.
Competitive Strategies: Fragmentation, Brands, and the Circular Imperative
The furniture market remains highly fragmented, with no single player holding a dominant global share. The competitive landscape includes:
Global Retail Giants: IKEA leads with a mass-market, flat-pack model, while Wayfair has disrupted the space through e-commerce.
Established Manufacturers: Ashley Furniture, Steelcase, MillerKnoll, and Williams-Sonoma hold significant shares in their respective segments (residential, office, premium).
Digital-First D2C Brands: Emerging brands are leveraging social media, influencer marketing, and data analytics to capture niche audiences with personalized designs and agile supply chains.
Regional Champions: Local players with deep cultural and distribution knowledge often outperform global brands in specific markets.
Key Strategic Imperatives:
Sustainability as a Differentiator: From circular design (design for disassembly) to the use of recycled materials, sustainability is moving from a compliance requirement to a brand-building asset. Corporate ESG mandates are accelerating this trend.
Omnichannel Excellence: The future is not purely online or offline; it is a seamless integration. Brands that invest in AR/VR, flexible delivery, and showroom experiences will win.
Customization and Personalization: Consumers increasingly seek unique, personalized furniture. Modular designs and 3D modeling are enabling mass customization at scale.
Supply Chain Resilience: Diversifying manufacturing bases, nearshoring, and investing in digital supply chain tools are critical to mitigating risk.
Strategic White-Space Analysis: Opportunities in Underserved Segments
Our analysis identifies several high-potential white spaces for investment and innovation:
Smart Furniture for Wellness: The integration of sensors and IoT into furniture (e.g., sleep-tracking beds, posture-correcting chairs) is nascent but promising, particularly in health-conscious markets.
Sustainable Outdoor Furniture: As outdoor living spaces gain prominence, there is growing demand for weather-resistant, eco-friendly materials. This is a relatively under-served niche with high margins.
Aging Population Furniture: With a demographic shift toward older populations in developed nations, furniture that addresses ergonomics, safety, and ease of use (e.g., lift chairs, adjustable beds) represents a significant untapped market.
Circular Economy Services: Furniture rental and subscription models are gaining traction in Europe and North America, particularly among urban millennials who value flexibility over ownership. This model also extends product life and reduces waste.
Institutional Furniture for Emerging Markets: As governments invest in healthcare and education infrastructure, there is a growing need for durable, hygienic, and affordable institutional furniture. Suppliers who can meet strict technical specifications and provide repeatable delivery will find a lucrative market.
Furniture Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Furniture Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.0% from 2020-2034
Segmentation
By Product
Bedroom Furniture
Storage Furniture
Seating Furniture
Living Room Furniture
Kitchen & Dining Furniture
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Expansion of residential construction and housing supply
3.1.2. Rapid urbanization and space-saving modular furniture demand
3.1.3. Rising disposable income and middle-class expansion
3.1.4. Remote and hybrid work driving home office furniture demand
3.1.5. Corporate ESG mandates spurring adoption of sustainable materials
3.2. Market Trends
3.2.1. Sustainability and circular economy models gaining traction
3.2.2. Digital-first D2C brands and omnichannel retail expansion
3.2.3. Smart and multifunctional furniture demand
3.2.4. Customization and personalization at scale
3.2.5. Integration of AR/VR in furniture shopping
3.3. Market Restrains
3.3.1. Volatility in raw material and production costs
3.3.2. Supply chain disruptions and logistics challenges
3.3.3. Intense market fragmentation and price competition
3.3.4. Trade protectionist measures and tariffs
3.4. Market Restraints
Outdoor Furniture
Home Office Furniture
Lamps & Lighting
Home Décor
Baby & Children's Furniture
By Material
Wood
Metal
Plastic
Glass
By Application
Residential
Commercial
Institutional
By Price Range
Economy
Mid-Range
Premium
By Distribution Channel
B2C/Retail
B2B/Project
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
Indonesia
Vietnam
South America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
Turkey
3.4.1. Volatility in raw material and production costs
3.4.2. Supply chain disruptions and logistics challenges
3.4.3. Intense market fragmentation and price competition
3.4.4. Trade protectionist measures and tariffs
3.5. Market Challenges
3.5.1. Balancing design innovation with cost efficiency
3.5.2. Last-mile delivery and assembly complexity
3.5.3. Attracting skilled labor in a fragmented industry
3.5.4. Navigating diverse regulatory standards across regions
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Bedroom Furniture
5.1.2. Storage Furniture
5.1.3. Seating Furniture
5.1.4. Living Room Furniture
5.1.5. Kitchen & Dining Furniture
5.1.6. Outdoor Furniture
5.1.7. Home Office Furniture
5.1.8. Lamps & Lighting
5.1.9. Home Décor
5.1.10. Baby & Children's Furniture
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Wood
5.2.2. Metal
5.2.3. Plastic
5.2.4. Glass
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Residential
5.3.2. Commercial
5.3.3. Institutional
5.4. Market Analysis, Insights and Forecast - by Price Range
5.4.1. Economy
5.4.2. Mid-Range
5.4.3. Premium
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. B2C/Retail
5.5.2. B2B/Project
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Bedroom Furniture
6.1.2. Storage Furniture
6.1.3. Seating Furniture
6.1.4. Living Room Furniture
6.1.5. Kitchen & Dining Furniture
6.1.6. Outdoor Furniture
6.1.7. Home Office Furniture
6.1.8. Lamps & Lighting
6.1.9. Home Décor
6.1.10. Baby & Children's Furniture
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Wood
6.2.2. Metal
6.2.3. Plastic
6.2.4. Glass
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Residential
6.3.2. Commercial
6.3.3. Institutional
6.4. Market Analysis, Insights and Forecast - by Price Range
6.4.1. Economy
6.4.2. Mid-Range
6.4.3. Premium
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. B2C/Retail
6.5.2. B2B/Project
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Bedroom Furniture
7.1.2. Storage Furniture
7.1.3. Seating Furniture
7.1.4. Living Room Furniture
7.1.5. Kitchen & Dining Furniture
7.1.6. Outdoor Furniture
7.1.7. Home Office Furniture
7.1.8. Lamps & Lighting
7.1.9. Home Décor
7.1.10. Baby & Children's Furniture
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Wood
7.2.2. Metal
7.2.3. Plastic
7.2.4. Glass
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Residential
7.3.2. Commercial
7.3.3. Institutional
7.4. Market Analysis, Insights and Forecast - by Price Range
7.4.1. Economy
7.4.2. Mid-Range
7.4.3. Premium
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. B2C/Retail
7.5.2. B2B/Project
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Bedroom Furniture
8.1.2. Storage Furniture
8.1.3. Seating Furniture
8.1.4. Living Room Furniture
8.1.5. Kitchen & Dining Furniture
8.1.6. Outdoor Furniture
8.1.7. Home Office Furniture
8.1.8. Lamps & Lighting
8.1.9. Home Décor
8.1.10. Baby & Children's Furniture
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Wood
8.2.2. Metal
8.2.3. Plastic
8.2.4. Glass
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Residential
8.3.2. Commercial
8.3.3. Institutional
8.4. Market Analysis, Insights and Forecast - by Price Range
8.4.1. Economy
8.4.2. Mid-Range
8.4.3. Premium
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. B2C/Retail
8.5.2. B2B/Project
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Bedroom Furniture
9.1.2. Storage Furniture
9.1.3. Seating Furniture
9.1.4. Living Room Furniture
9.1.5. Kitchen & Dining Furniture
9.1.6. Outdoor Furniture
9.1.7. Home Office Furniture
9.1.8. Lamps & Lighting
9.1.9. Home Décor
9.1.10. Baby & Children's Furniture
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Wood
9.2.2. Metal
9.2.3. Plastic
9.2.4. Glass
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Residential
9.3.2. Commercial
9.3.3. Institutional
9.4. Market Analysis, Insights and Forecast - by Price Range
9.4.1. Economy
9.4.2. Mid-Range
9.4.3. Premium
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. B2C/Retail
9.5.2. B2B/Project
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Bedroom Furniture
10.1.2. Storage Furniture
10.1.3. Seating Furniture
10.1.4. Living Room Furniture
10.1.5. Kitchen & Dining Furniture
10.1.6. Outdoor Furniture
10.1.7. Home Office Furniture
10.1.8. Lamps & Lighting
10.1.9. Home Décor
10.1.10. Baby & Children's Furniture
10.2. Market Analysis, Insights and Forecast - by Material
10.2.1. Wood
10.2.2. Metal
10.2.3. Plastic
10.2.4. Glass
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Residential
10.3.2. Commercial
10.3.3. Institutional
10.4. Market Analysis, Insights and Forecast - by Price Range
10.4.1. Economy
10.4.2. Mid-Range
10.4.3. Premium
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. B2C/Retail
10.5.2. B2B/Project
11. Competitive Analysis
11.1. Company Profiles
11.1.1. IKEA
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Ashley Furniture Industries LLC
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Steelcase Inc.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. MillerKnoll Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Williams-Sonoma Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Wayfair
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Wakefit
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Furniture Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 5: North America Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 6: North America Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 9: North America Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 10: North America Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 15: Europe Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 17: Europe Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 18: Europe Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 19: Europe Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 20: Europe Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 21: Europe Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 22: Europe Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 23: Europe Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 24: Europe Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 27: Asia Pacific Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 28: Asia Pacific Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 29: Asia Pacific Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 30: Asia Pacific Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 31: Asia Pacific Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 32: Asia Pacific Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 33: Asia Pacific Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 34: Asia Pacific Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 35: Asia Pacific Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 36: Asia Pacific Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 39: South America Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 40: South America Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 41: South America Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 42: South America Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 43: South America Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 44: South America Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 45: South America Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 46: South America Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 47: South America Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 48: South America Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 51: Middle East & Africa Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 52: Middle East & Africa Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 53: Middle East & Africa Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 54: Middle East & Africa Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 55: Middle East & Africa Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 56: Middle East & Africa Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 57: Middle East & Africa Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 58: Middle East & Africa Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 59: Middle East & Africa Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 60: Middle East & Africa Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Furniture Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Global Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 3: Global Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Global Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 5: Global Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Global Furniture Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 8: North America Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 9: North America Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 10: North America Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 11: North America Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: North America Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 17: Europe Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 18: Europe Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 19: Europe Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 20: Europe Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 21: Europe Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Germany Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Italy Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Spain Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Asia Pacific Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 28: Asia Pacific Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 29: Asia Pacific Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 30: Asia Pacific Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 31: Asia Pacific Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 32: Asia Pacific Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 33: China Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Japan Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: India Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Indonesia Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Vietnam Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: South America Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 39: South America Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 40: South America Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 41: South America Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 42: South America Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 43: South America Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 44: Brazil Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Argentina Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 46: Middle East & Africa Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 47: Middle East & Africa Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 48: Middle East & Africa Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 49: Middle East & Africa Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 50: Middle East & Africa Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 51: Middle East & Africa Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 52: Saudi Arabia Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: UAE Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 54: Turkey Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the furniture industry market?
The global furniture industry market was valued at $786.1 billion in 2025 and is estimated at $831.6 billion in 2026. It is projected to reach $1,334.1 billion by 2033, growing at a CAGR of 7.0%.
2Which region dominates the furniture industry market?
Asia-Pacific holds the largest share, accounting for 38.5% of global revenue in 2025. It is also the fastest-growing region, with China alone expected to grow at a CAGR of 8.2% through 2033.
3What are the main drivers of the furniture industry market?
Key drivers include residential construction and housing supply expansion, rapid urbanization, the rise of digital-first D2C brands, and the increasing demand for multifunctional and smart furniture. Government housing programs like Saudi Arabia's Vision 2030 are also significant catalysts.
4What are the key challenges facing the furniture industry?
The industry faces volatility in raw material costs (timber, metals, foam), supply chain disruptions, intense market fragmentation, and trade protectionist measures. These factors squeeze margins and require agile supply chain management.
5Which furniture material segment is the largest?
Wood is the dominant material, holding a 39.8% share in 2025. However, metal furniture is growing faster at a CAGR of 7.38%, driven by durability and modern design trends.
6How is the distribution channel landscape evolving?
B2C/retail currently accounts for 78.95% of the market, but B2B/project sales are growing faster at 7.89%. Omnichannel strategies integrating online discovery with physical showrooms are becoming essential.
7What is the role of sustainability in the furniture market?
Sustainability is a major trend, driven by consumer awareness and corporate ESG mandates. It encompasses sustainable material sourcing (e.g., FSC-certified wood), circular design, and furniture rental models, particularly in Europe and North America.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 1,400+ in-depth interviews with industry stakeholders across the furniture value chain, including manufacturers, raw material suppliers, distributors, retailers, and institutional buyers.
70–80% of our market data is derived from primary research, ensuring high granularity and reliability.
Interviews were stratified across company types: furniture manufacturers (35%), raw material suppliers (20%), distributors/retailers (25%), and technology/service providers (20%).
Stakeholder roles included CEO/Founder (30%), Procurement Director (25%), Retail Operations Manager (25%), and Design/Product Head (20%).
All interviews were conducted with senior decision-makers (Director level and above) to capture strategic insights.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
CEO/Founder
30%
Procurement Director
25%
Retail Operations Manager
25%
Design/Product Head
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Furniture Manufacturers
35%
Raw Material Suppliers
20%
Distributors & Retailers
25%
Technology & Service Providers
20%
Secondary Research & Industry Benchmarking
20–30% of our data is sourced from secondary research, including official trade statistics, regulatory filings, and industry association reports.
We benchmark our findings against data from multilateral institutions such as UN Comtrade, World Bank, OECD, and Eurostat, as well as non-profit trade associations like the European Furniture Industries Confederation (EFIC) and the American Home Furnishings Alliance (AHFA).
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to validate company-level data and competitive dynamics.
We also monitor regulatory developments from bodies such as the U.S. Consumer Product Safety Commission (CPSC) and the European Chemicals Agency (ECHA).
Demand Modeling & Market Estimation
We employ a dual top-down and bottom-up modeling approach, with multi-level data triangulation for validation.
Bottom-up models are built using quantitative metrics such as per capita furniture spending (derived from household consumption surveys), residential construction permits, housing starts, and commercial real estate fit-out expenditure.
Supply-side models incorporate production volumes, import/export data, and factory capacity utilization rates.
Demand models are segmented by product, material, application, and region, with forecasts driven by econometric modeling of GDP, urbanization rates, and disposable income.
Data Accuracy & Quality Check
Every report is guaranteed an estimated data accuracy level of 85–90%.
Data triangulation is performed across primary interviews, secondary sources, and our proprietary market model, with any variances >5% subjected to re-validation.
All reports are updated to the date of purchase, ensuring the most current market intelligence.
Quality assurance is conducted by a senior analyst panel, with a final review by the Research Director before publication.