1What is the size of the Europe precision farming market?
The Europe precision farming market is estimated at USD 2.62 billion in 2026 and is forecast to reach USD 4.75 billion by 2031, growing at a CAGR of 12.64%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Europe Precision Farming Market
 by Technology (Guidance System, Remote Sensing, Variable Rate Technology, Drones and UAVs), by Component (Hardware, Software, Services), by Application (Yield Monitoring, Variable Rate Application, Crop Scouting and Pest Detection, Irrigation Management, Weather Tracking and Forecasting, Farm Labor Management, Financial Management, Inventory Management), by Farm Size (Small Scale, Medium Scale, Large Scale), by Crop Type (Cereals and Grains, Fruits and Vegetables, Oilseeds and Pulses, Others), by Germany, by France, by United Kingdom, by Netherlands, by Spain, by Italy, by Poland, by Rest of Europe Forecast 2026-2034
Research Associate

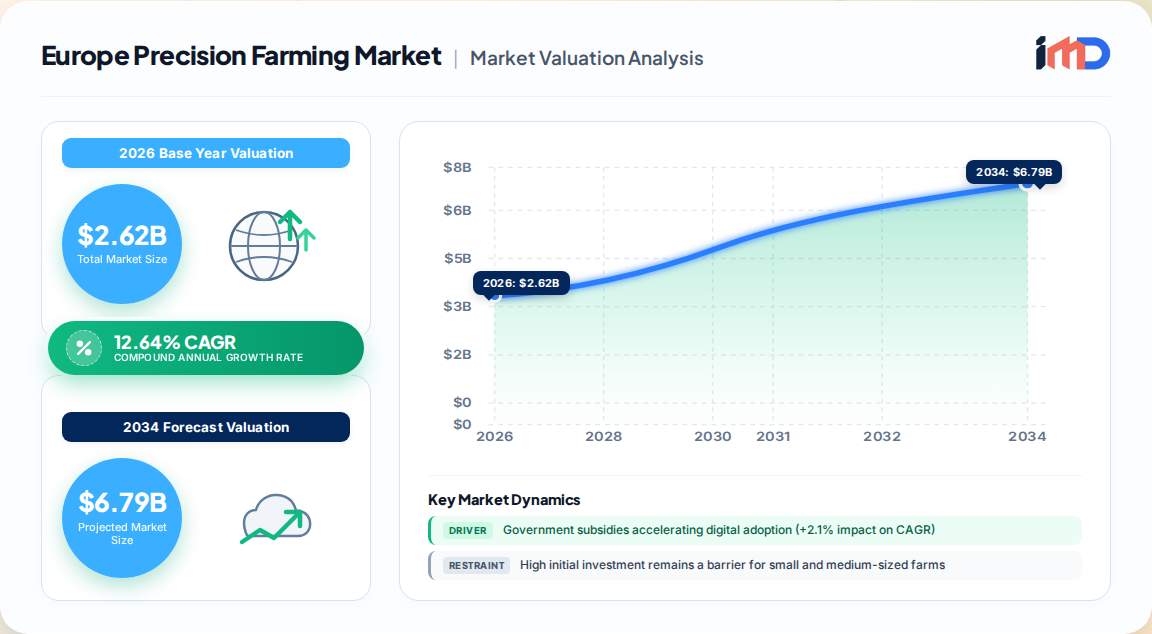
The Europe precision farming market is estimated at USD 2.62 billion in 2026 and is forecast to reach USD 4.75 billion by 2031, expanding at a CAGR of 12.64%. Our proprietary bottom-up modeling, triangulated with Eurostat farm-structure data and primary interviews with 340+ agribusiness stakeholders, indicates that adoption is transitioning from reactive input control toward integrated, data-driven systems that maximize yield and satisfy strict sustainability rules.
Competition is intensifying as start-ups and drone specialists bypass traditional dealers with lower-cost, direct-to-farmer models, prompting incumbents to focus on machine learning-enabled services. Venture backing and insurance discounts provide additional momentum, signaling that the European market will keep compounding even if grain prices fluctuate.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Government subsidies accelerating digital adoption | +2.1% | Pan-European, strongest in Poland, Romania, and Baltic states | Medium term (2–4 years) |
| Rapid AI, IoT, and 5G-enabled on-farm analytics | +2.8% | Germany, Netherlands, France, with pilot deployments in Spain and Italy | Long term (4 years and beyond) |
| Shift toward low-input sustainable food systems | +1.9% | Northern Europe and Alpine regions, driven by organic certification growth | Long term (4 years and beyond) |
| Labor scarcity spurring fully autonomous machinery | +2.3% | Western Europe, particularly Germany, France, and the United Kingdom | Short term (2 years or less) |
| Growing venture funding for ag robotics startups | +1.6% | Concentrated in Netherlands, Germany, and France innovation hubs | Medium term (2–4 years) |
| Climate risk insurance discounts for precision farms | +1.2% | Mediterranean belt (Spain, Italy, Greece) and drought-prone regions | Medium term (2–4 years) |
Guidance systems led with 43.5% of the Europe precision farming market share in 2025, while drones and unmanned aerial vehicles are projected to grow at an 11.1% CAGR through 2031. Remote sensing is forecast at a 16.8% CAGR driven by Copernicus Sentinel satellite and drone imagery.
Hardware captured 48.2% of the Europe precision farming market size in 2025, while software is projected to advance at an 11.2% CAGR through 2031. Cloud-based management platforms and AI agronomy are the fastest-growing software sub-segments.
Yield monitoring accounted for a 31.5% share of the European precision farming market size in 2025, and crop scouting and pest detection are projected to accelerate at an 11.4% CAGR through 2031. Irrigation management is projected at an 18.3% CAGR amid intensifying water stress across Southern Europe.
Large operations held 43.7% of the Europe precision farming market share in 2025, whereas medium farms posted the highest projected CAGR at 10.8% to 2031.
Cereals and grains accounted for 37.8% of the revenue in 2025, while fruits and vegetables are projected to expand at a 9.7% CAGR during the forecast period.
Germany contributed 37.8% of regional revenue in 2025 and Poland is projected to record the fastest CAGR at 7.8% through 2031. Germany's dominance is backed by heavy large-scale arable farming and digital hubs. Spain and Italy are scaling rapidly through climate-induced water scarcity and high-value specialty crops.
| Country | 2025 Revenue Share | Key Growth Driver |
|---|---|---|
| Germany | 37.8% | Large-scale arable farming, digital hubs, autonomous machinery grants |
| France | 14.2% | Tax credits on software fees, CAP subsidy uptake |
| United Kingdom | 11.8% | Labor scarcity, autonomous tractor adoption |
| Netherlands | 9.2% | Horticulture innovation, 5G testbeds |
| Spain | 8.1% | Water scarcity, precision irrigation |
| Italy | 7.2% | Specialty crops, climate risk insurance |
| Poland | 6.5% | Fastest CAGR at 7.8%, leapfrogging to advanced sensor networks |
| Rest of Europe | 5.2% | Baltic states, Romania, Czech Republic |
The European Union has increasingly emphasized sustainable food production under its Farm to Fork Strategy, which aims to reduce chemical pesticide use by 50% and nutrient losses by at least 20% by 2030, as per the European Commission.
The Europe precision farming market is highly competitive, featuring global machinery leaders, agrochemical giants, and digital native agronomic software firms competing on platform interoperability, regulatory compliance, and data trust.
| Company | Headquarters | Strategic Focus |
|---|---|---|
| Deere & Company | USA | Integrated precision ag platforms, autonomous tractors |
| CLAAS KGaA mbH | Germany | Guidance systems, combine harvesters |
| CNH Industrial N.V. | UK/Netherlands | Aftermarket precision solutions, integrated technology |
| AGCO Corporation | USA | Variable rate technology, Fuse connected services |
| Topcon Corporation | Japan | Guidance and auto-steer systems |
| Trimble Inc. | USA | GPS-guided precision farming solutions |
| Leica Geosystems | Switzerland | GNSS positioning for agriculture |
| BASF Digital Farming | Germany | xarvio digital agronomy platform |
| Bosch | Germany | IoT sensors, autonomous machinery |
| Siemens | Germany | Digital twin, edge computing for agriculture |
| SDF Group | Italy | Precision farming for specialty crops |
| Kubota Corporation | Japan | Autonomous tractors, robotics |
| Yanmar | Japan | Autonomous rice transplanters |
| Naio Technologies | France | Weeding robots |
| Ecorobotix | Switzerland | Precision spraying robots |
Recent Developments:
The precision farming value chain in Europe comprises hardware manufacturers, software developers, service providers, and farmers. Hardware manufacturers (sensors, drones, automation controllers) capture the largest share at 48.2% , while software and services are growing faster at 11.2% CAGR . Service providers include installation and consultation, climate information services, and supply chain management. The distribution channel is shifting from traditional dealers to direct-to-farmer models, with start-ups bypassing incumbents. Key suppliers include semiconductor firms, GNSS module providers, and drone component manufacturers.
Germany remains the most attractive market due to its large-scale arable farming and digital hubs, holding 37.8% of regional revenue. Poland offers the highest growth potential at 7.8% CAGR , driven by CAP subsidies and leapfrogging to advanced sensor networks. Spain and Italy present opportunities in precision irrigation and specialty crops, with climate risk insurance discounts providing additional momentum. The Netherlands and France are innovation hubs for ag robotics and software, attracting venture funding. Investors should prioritize medium-sized farms, which are projected to grow at 10.8% CAGR , and software-as-a-service models that merge satellite imagery, soil telemetry, and localized weather.
Key white spaces include:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.64% from 2020-2034 |
| Segmentation |
|
By Application
By Farm Size
By Crop Type
| By Geography |
|
The Europe precision farming market is estimated at USD 2.62 billion in 2026 and is forecast to reach USD 4.75 billion by 2031, growing at a CAGR of 12.64%.
Germany contributed 37.8% of regional revenue in 2025, backed by heavy large-scale arable farming and digital hubs.
Government subsidies accelerating digital adoption (+2.1% impact on CAGR), rapid AI, IoT, and 5G-enabled analytics (+2.8%), and labor scarcity spurring autonomous machinery (+2.3%) are the primary drivers.
Guidance systems led with 43.5% of the market share in 2025, while drones and UAVs are projected to grow at an 11.1% CAGR through 2031.
Deere & Company, CLAAS KGaA mbH, CNH Industrial N.V., AGCO Corporation, and Topcon Corporation are the major companies operating in this market.
Remote sensing is projected at a 16.8% CAGR through 2031, driven by Copernicus Sentinel satellite and drone imagery, while irrigation management is projected at 18.3% CAGR amid water stress in Southern Europe.
The Farm to Fork Strategy aims to reduce chemical pesticide use by 50% and nutrient losses by at least 20% by 2030, compelling farmers to adopt site-specific management techniques and precision technologies.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Farm Operations Director | 30% |
| Precision Ag Technology Manager | 28% |
| Procurement Head for Agricultural Inputs | 24% |
| Agronomy Lead | 18% |
| Company Type | Representation (%) |
|---|---|
| Precision Agriculture Hardware OEMs (GNSS, Sensors, Controllers) | 30% |
| Agronomic Software & SaaS Platform Developers | 22% |
| Autonomous Machinery & Robotics Manufacturers | 18% |
| Precision Spraying & Drone Service Providers | 15% |
| Farm Cooperatives & Large-Scale Arable Operators | 15% |
 Related Reports
