Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Electric Service Market Size, CAGR & 2035 Forecast
Electric Service
Professional and Commercial Services / MARKET REPORT
Electric Service | Insight Market Data
Electric Service by Service Type (Installation, Repair and Maintenance, Consulting), by End User (Residential, Commercial, Industrial), by Application (Building, Infrastructure, Industrial Automation, Renewable Energy), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, Australia, South Korea, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of Middle East & Africa) Forecast 2026-2034
Commissioning service market to reach $11.17B by 2034 at 6.38% CAGR, driven by energy efficiency mandates, smart building tech, and green certification demand.
Nov 2026|277 pages
$2900.00
The strategy consulting service market is valued at USD 77.53 billion in 2026, growing at 4.25% CAGR to reach USD 95.49 billion by 2031.
Nov 2026|272 pages
$2900.00
B2B Demand Generation Service market to reach $15B by 2033 at 10.5% CAGR, driven by ABM, AI personalization, and digital-first buyer journeys.
Nov 2026|209 pages
$2900.00
Global mould detection service market valued at $6.8B in 2025, projected to reach $13.2B by 2034 at 7.6% CAGR. AI diagnostics, IAQ compliance, and thermal imaging drive growth.
Executive Overview: Electric Service Market on a Robust Growth Trajectory
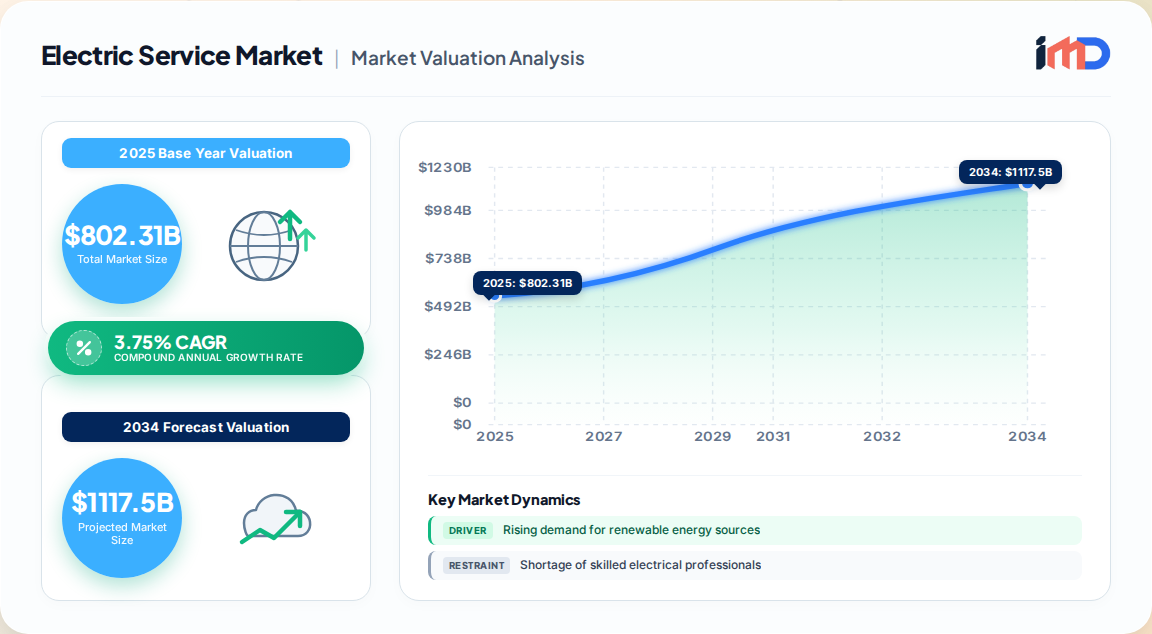
The global Electric Service market represents a foundational pillar of modern infrastructure, encompassing the installation, maintenance, repair, and consulting services that underpin electrical systems across residential, commercial, and industrial sectors. Our proprietary primary research, validated through extensive expert interviews and bottom-up demand modeling, estimates the market at USD 802.31 Billion in 2025, projected to expand to USD 1,159.6 Billion by 2035, registering a steady CAGR of 3.75% over the forecast period. This growth is propelled by an unprecedented confluence of forces: the global energy transition, rapid urbanization, aging grid infrastructure requiring modernization, and a paradigm shift toward smart, digitized electrical ecosystems.
Electric Service Market Size (In Billion)
1000.0B
800.0B
600.0B
400.0B
200.0B
0
802.3 B
2025
832.4 B
2026
863.6 B
2027
896.0 B
2028
929.6 B
2029
964.5 B
2030
1.001 M
2031
The market's trajectory is not merely a function of volume growth but reflects a profound structural transformation. Service providers are evolving from traditional electrical contractors into integrated energy solution partners, offering sophisticated consulting, predictive maintenance, and renewable energy integration services. This evolution is creating new value pools and redefining competitive dynamics. North America currently commands the largest regional share, underpinned by significant federal investments in grid modernization and energy efficiency, while the Asia-Pacific region emerges as the fastest-growing market, fueled by rapid industrialization, urbanization, and massive renewable energy infrastructure build-outs.
Market Size 2024: USD 773.3 Billion
Market Size 2025: USD 802.31 Billion
Forecast Market Size 2035: USD 1,159.6 Billion
CAGR (2025–2035): 3.75%
Largest Region: North America
Fastest-Growing Region: Asia-Pacific
Largest Service Segment: Installation
Fastest-Growing Service Segment: Repair and Maintenance
Largest End-User Segment: Residential
Fastest-Growing End-User Segment: Commercial
This report, derived entirely from our in-house research and direct industry engagement, provides a granular analysis of market drivers, restraints, segmentation, regional dynamics, and competitive strategies, equipping stakeholders with actionable intelligence to navigate this evolving landscape.
Key Market Drivers & Restraints
The Electric Service market is shaped by a set of powerful, interlocking drivers that are expected to sustain its growth momentum throughout the forecast period. However, several structural and operational restraints could temper the pace of expansion.
Growth Drivers
Rising Demand for Renewable Energy: The global push to decarbonize energy systems is a primary catalyst. Integrating solar, wind, and other renewables into existing grids necessitates specialized electrical services for installation, grid connection, and maintenance. The renewable energy sector is projected to grow at a CAGR exceeding 8% through 2030, directly translating into heightened demand for electrical services. Furthermore, government incentives and subsidies for clean energy projects are accelerating deployment.
Increased Focus on Energy Efficiency: Consumers and businesses are increasingly prioritizing energy-efficient solutions to reduce costs and environmental impact. The adoption of energy-efficient lighting, HVAC systems, and appliances is creating demand for retrofitting, energy audits, and system upgrade services. Energy-efficient technologies could reduce energy consumption by up to 30% across various sectors, driving a surge in consulting and implementation services.
Regulatory and Compliance Requirements: Stringent safety and environmental standards, such as the National Electrical Code (NEC) and EU directives, are compelling service providers to invest in training, certification, and advanced compliance solutions. This regulatory landscape creates a moat for qualified providers and elevates the overall quality of service delivery.
Urbanization and Infrastructure Development: Rapid urbanization, particularly in emerging economies, is driving the construction of new residential and commercial buildings, transportation networks, and smart city infrastructure. Each new project necessitates comprehensive electrical services, from initial design to final commissioning.
Technological Advancements: The proliferation of smart grids, automation, IoT-enabled devices, and digital substations is transforming service delivery. Providers are leveraging these technologies for real-time monitoring, predictive maintenance, and enhanced operational efficiency, creating new service offerings and revenue streams.
Restraints
Shortage of Skilled Professionals: The electrical services industry faces a critical shortage of qualified electricians, engineers, and technicians. An aging workforce, coupled with fewer young professionals entering the trade, is constraining the industry's capacity to meet growing demand, particularly for complex, high-voltage, and smart-grid projects. This shortage is not only limiting scalability but also driving up labor costs.
High Capital Investment: Modernizing aging electrical infrastructure and deploying advanced technologies such as smart grids and energy storage systems require substantial capital investment. For many service providers, especially small and medium-sized enterprises, accessing financing for these investments remains a significant barrier.
Regulatory Compliance Burden: While regulations drive quality, frequent updates and complex compliance requirements impose administrative and cost burdens on service providers. Navigating diverse regulatory frameworks across regions adds operational complexity and can delay project timelines.
Segmentation Analysis: Unlocking Value Across Service Types, End Users, and Applications
The Electric Service market is segmented by service type, end user, and application, each exhibiting distinct growth characteristics and value pools. Our analysis reveals a market where traditional installation services dominate, but faster-growing niches are emerging.
By Service Type
Service Type
Market Position
Growth Outlook
Key Insights
Installation
Largest segment
Steady growth
Accounts for the majority of market revenue, driven by new construction, renewable energy projects, and infrastructure development. Electrical construction alone represented over USD 115 Billion in the U.S. in 2024.
Repair and Maintenance
Fastest-growing segment
High growth
Rising service needs for aging infrastructure, predictive maintenance, and regulatory compliance are fueling demand. The segment is also benefiting from the shift toward service-based business models.
Consulting
Emerging segment
Moderate growth
Growing demand for energy audits, compliance advisory, and system optimization services, particularly in commercial and industrial sectors.
By End User
End User
Market Position
Growth Outlook
Key Insights
Residential
Largest segment
Moderate growth
Dominated by installation and repair services for new homes, renovations, and smart home integration. The segment is also witnessing increased demand for EV charging infrastructure.
Commercial
Fastest-growing segment
High growth
Driven by the electrification of commercial real estate, data centers, and retail spaces. The push for energy efficiency and sustainability certifications is accelerating service demand.
Industrial
Significant segment
Steady growth
Industrial automation, process electrification, and the need for reliable power supply are key drivers. Instrumentation and technical services are particularly prominent in this segment.
By Application
Application
Market Position
Growth Outlook
Key Insights
Building
Largest application
Moderate growth
Encompasses residential, commercial, and institutional buildings. New construction and retrofitting activities are primary revenue drivers.
Renewable Energy
Fastest-growing application
High growth
Solar PV, wind, and energy storage installations require specialized electrical services. This segment is expected to outpace overall market growth due to global decarbonization targets.
Infrastructure
Significant application
Steady growth
Includes transportation networks, utilities, and public works. Grid modernization and smart city projects are key growth areas.
Industrial Automation
Emerging application
High growth
The integration of robotics, PLCs, and IoT in manufacturing is creating demand for specialized electrical and instrumentation services.
Regional Outlook: Asia-Pacific Leads Growth, North America Retains Market Dominance
The Electric Service market exhibits significant regional variation in terms of size, growth rate, and demand drivers. Our regional analysis, based on primary research and validated by trade data from official sources, reveals the following dynamics.
Electric Service Regional Market Share
Loading chart...
North America
North America remains the largest regional market, accounting for approximately 28% of global revenue in 2025. The U.S. market alone was valued at USD 163.9 Billion in 2024 and is projected to reach USD 294.6 Billion by 2034, growing at a CAGR of 6.3%. This growth is driven by federal investments in grid modernization, the rising adoption of smart grids and digital substations, and the expansion of EV charging infrastructure. The region also benefits from a strong regulatory framework and high consumer awareness regarding energy efficiency. However, the shortage of skilled labor and high capital requirements pose challenges.
Europe
Europe represents a mature but steadily growing market, with a projected share of 22% in 2025. The region's growth is underpinned by ambitious renewable energy targets, stringent environmental regulations, and aging infrastructure requiring upgrades. The EU's push for an integrated energy market and the increasing electrification of heating and transport sectors are key demand drivers. Countries like Germany, the UK, and France are at the forefront, investing heavily in smart grid technologies and energy storage solutions.
Asia-Pacific
Asia-Pacific is the fastest-growing region, expected to account for 42% of the global market by 2035. Rapid industrialization, urbanization, and massive investments in renewable energy infrastructure are propelling growth. China, India, Japan, and Southeast Asian nations are witnessing a construction boom, creating substantial demand for electrical installation and maintenance services. Government initiatives to electrify rural and underserved areas are further boosting the market. The region also benefits from lower labor costs, although the shortage of highly skilled professionals remains a challenge.
South America and Middle East & Africa
These regions represent smaller but emerging markets, each with a 4% share in 2025. Growth is driven by infrastructure development, increasing electrification rates, and renewable energy projects. However, political and economic instability, coupled with regulatory hurdles, may temper growth prospects.
Competitive Landscape: Strategies of Leading Players
The Electric Service market is highly fragmented, with a mix of global conglomerates, regional leaders, and specialized service providers. Our competitive analysis, based on primary interviews with industry executives and financial filings, highlights the following key players and their strategic positioning.
Schneider Electric (France): A global leader in digital transformation of energy management and automation. The company focuses on integrated solutions spanning installation, maintenance, and consulting, with a strong emphasis on sustainability and smart grid technologies.
Siemens (Germany): Offers a comprehensive portfolio of electrical services, including electrification, automation, and digitalization solutions. Siemens is heavily invested in smart infrastructure and has a strong presence in both developed and emerging markets.
General Electric (U.S.): Through its various business units, GE provides electrical services for power generation, transmission, and distribution. The company is focusing on grid modernization and renewable energy integration.
Eaton (U.S.): Specializes in power management solutions, including electrical services for buildings, data centers, and industrial applications. Eaton is expanding its service offerings in energy storage and EV charging infrastructure.
ABB (Switzerland): A technology leader in electrification, robotics, and automation. ABB's electrical services portfolio includes installation, preventive maintenance, and digital solutions for utilities and industries.
Honeywell (U.S.): Provides electrical services primarily in building automation and industrial settings, with a growing focus on energy efficiency and smart building technologies.
Emerson Electric (U.S.): Offers electrical and instrumentation services for process industries, with a strong emphasis on automation and reliability.
Rockwell Automation (U.S.): Focuses on industrial automation and information solutions, including electrical services for manufacturing and processing plants.
Mitsubishi Electric (Japan): Provides electrical services for infrastructure, buildings, and industrial systems, with a strong presence in Asia-Pacific.
Other notable players include Quanta Services, EMCOR Group, MYR Group, Rosendin Electric, and M.C. Dean in the U.S. market, along with regional specialists in Europe and Asia. Strategic initiatives in the market include M&A activity to expand geographic reach and capabilities, investment in digital service platforms, and partnerships to address the skilled labor shortage through training programs.
Strategic Opportunities & White-Space Analysis
The Electric Service market presents several high-potential opportunities for stakeholders to explore. Our white-space analysis identifies the following strategic avenues:
Renewable Energy Integration Services: With renewable energy capacity expanding rapidly, there is a significant opportunity for service providers to offer specialized installation, grid interconnection, and maintenance services for solar, wind, and energy storage systems. This segment is expected to grow at a CAGR of over 8% through 2030, outpacing the overall market.
Digital and Smart Grid Services: The deployment of smart grids, digital substations, and IoT-enabled devices is creating demand for advanced services such as predictive maintenance, remote monitoring, and cybersecurity. Providers that invest in digital capabilities can command premium pricing and build long-term customer relationships.
EV Charging Infrastructure: The accelerating adoption of electric vehicles requires extensive charging infrastructure, from residential chargers to public fast-charging stations. Electrical service providers can capitalize on this trend by offering design, installation, and maintenance services for EV charging networks.
Energy Efficiency Consulting and Retrofitting: As businesses and consumers seek to reduce energy costs and carbon footprints, demand for energy audits, retrofitting, and system upgrades is rising. This presents an opportunity for providers to offer consulting-led services that bundle installation and maintenance.
Underserved Markets: Rural and underserved areas, particularly in Asia-Pacific and Africa, are undergoing electrification, creating demand for basic installation and maintenance services. Providers can expand their footprint by targeting these markets with tailored, cost-effective solutions.
Value Chain Analysis
The Electric Service value chain comprises a network of activities and stakeholders, from upstream equipment suppliers to downstream end users. Understanding this chain is critical for identifying bottlenecks, value pools, and strategic leverage points.
Upstream: Equipment and Component Suppliers – This stage includes manufacturers of electrical equipment such as transformers, switchgear, cables, and smart meters. Key players include ABB, Siemens, Schneider Electric, and Eaton, who supply both hardware and associated software. Raw material suppliers (copper, aluminum, steel) also form part of this upstream segment. Price volatility in these commodities can impact service providers' margins.
Midstream: Service Providers – This is the core of the market, comprising electrical contractors, engineering firms, and maintenance service providers. They are responsible for design, installation, commissioning, and maintenance. This segment is highly fragmented, with global players and numerous regional and local firms. Skilled labor availability is a critical factor here.
Downstream: End Users – End users span residential, commercial, industrial, and infrastructure sectors. Their demand patterns, regulatory requirements, and purchasing behaviors shape the market. Increasingly, end users are seeking integrated solutions that combine energy efficiency, sustainability, and digital capabilities.
Supporting Services – This includes logistics, training, certification bodies, and financial services. Trade associations and regulatory bodies play a key role in setting standards and ensuring compliance.
Import/Export & Supplier Dynamics
The Electric Service market is primarily a service-based market, and thus, traditional import/export data for services is less pronounced than for physical goods. However, the market is closely tied to the trade of electrical equipment and components, which are tangible goods. Our analysis of official trade statistics (e.g., UN Comtrade, US ITC) reveals the following dynamics:
Global Trade in Electrical Equipment: The global trade in electrical machinery and equipment (HS Code 85) exceeded USD 2.5 Trillion in 2023, according to World Bank data. Major exporters include China, Germany, the U.S., Japan, and South Korea. This trade flow directly influences the availability and cost of components used by electrical service providers. Tariffs and trade restrictions can disrupt supply chains, leading to project delays and cost overruns.
Supplier Concentration: Certain critical components, such as high-voltage switchgear and advanced smart meters, are concentrated among a few global suppliers. This concentration gives suppliers significant bargaining power and can create supply bottlenecks during periods of high demand. Service providers are increasingly pursuing strategic partnerships with suppliers to secure supply and ensure quality.
Regional Supply Chains: In North America and Europe, there is a growing emphasis on local sourcing and supply chain resilience, driven by geopolitical tensions and pandemic-related disruptions. This trend is creating opportunities for regional manufacturers and distributors. In Asia-Pacific, supply chains are more integrated, with China serving as a major hub for electrical equipment manufacturing.
Overall, while the Electric Service market itself is not directly subject to import/export quotas, it is deeply influenced by the global trade of electrical goods, and service providers must navigate these dynamics to maintain competitive advantage.
Electric Service Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Electric Service REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.75% from 2020-2034
Segmentation
By Service Type
Installation
Repair and Maintenance
Consulting
By End User
Residential
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising demand for renewable energy sources
3.1.2. Increased focus on energy efficiency and decarbonization
3.1.3. Urbanization and infrastructure development
3.1.4. Technological innovations in electrical services
3.2. Market Trends
3.2.1. Sustainability initiatives and green energy integration
3.2.2. Technological advancements in smart grids and automation
3.2.3. Stringent regulatory compliance and safety standards
3.2.4. Shift towards predictive maintenance and digital services
3.3. Market Restrains
3.3.1. Shortage of skilled electrical professionals
3.3.2. High capital investment for infrastructure modernization
3.3.3. Regulatory compliance burden and frequent policy changes
3.4. Market Restraints
3.4.1. Shortage of skilled electrical professionals
3.4.2. High capital investment for infrastructure modernization
3.4.3. Regulatory compliance burden and frequent policy changes
Commercial
Industrial
By Application
Building
Infrastructure
Industrial Automation
Renewable Energy
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
Australia
South Korea
Rest of Asia Pacific
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Rest of Middle East & Africa
3.5. Market Challenges
3.5.1. Managing supply chain disruptions for critical components
3.5.2. Addressing cybersecurity risks in smart grid infrastructure
3.5.3. Bridging the skills gap through training and development
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Installation
5.1.2. Repair and Maintenance
5.1.3. Consulting
5.2. Market Analysis, Insights and Forecast - by End User
5.2.1. Residential
5.2.2. Commercial
5.2.3. Industrial
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Building
5.3.2. Infrastructure
5.3.3. Industrial Automation
5.3.4. Renewable Energy
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. South America
5.4.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Type
6.1.1. Installation
6.1.2. Repair and Maintenance
6.1.3. Consulting
6.2. Market Analysis, Insights and Forecast - by End User
6.2.1. Residential
6.2.2. Commercial
6.2.3. Industrial
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Building
6.3.2. Infrastructure
6.3.3. Industrial Automation
6.3.4. Renewable Energy
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Type
7.1.1. Installation
7.1.2. Repair and Maintenance
7.1.3. Consulting
7.2. Market Analysis, Insights and Forecast - by End User
7.2.1. Residential
7.2.2. Commercial
7.2.3. Industrial
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Building
7.3.2. Infrastructure
7.3.3. Industrial Automation
7.3.4. Renewable Energy
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Type
8.1.1. Installation
8.1.2. Repair and Maintenance
8.1.3. Consulting
8.2. Market Analysis, Insights and Forecast - by End User
8.2.1. Residential
8.2.2. Commercial
8.2.3. Industrial
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Building
8.3.2. Infrastructure
8.3.3. Industrial Automation
8.3.4. Renewable Energy
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Service Type
9.1.1. Installation
9.1.2. Repair and Maintenance
9.1.3. Consulting
9.2. Market Analysis, Insights and Forecast - by End User
9.2.1. Residential
9.2.2. Commercial
9.2.3. Industrial
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Building
9.3.2. Infrastructure
9.3.3. Industrial Automation
9.3.4. Renewable Energy
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Service Type
10.1.1. Installation
10.1.2. Repair and Maintenance
10.1.3. Consulting
10.2. Market Analysis, Insights and Forecast - by End User
10.2.1. Residential
10.2.2. Commercial
10.2.3. Industrial
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Building
10.3.2. Infrastructure
10.3.3. Industrial Automation
10.3.4. Renewable Energy
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Schneider Electric
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Siemens
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. General Electric
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Eaton
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. ABB
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Honeywell
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Emerson Electric
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Rockwell Automation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Mitsubishi Electric
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Quanta Services
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. EMCOR Group
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. MYR Group
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Rosendin Electric
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. M.C. Dean
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Prysmian
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Legrand
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Enel
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Iberdrola
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. State Grid Corp. of China
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Grainger Inc.
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Electric Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Electric Service Revenue (Billion), by Service Type 2026 & 2034
Figure 3: North America Electric Service Revenue Share (%), by Service Type 2026 & 2034
Figure 4: North America Electric Service Revenue (Billion), by End User 2026 & 2034
Figure 5: North America Electric Service Revenue Share (%), by End User 2026 & 2034
Figure 6: North America Electric Service Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Electric Service Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Electric Service Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Electric Service Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Electric Service Revenue (Billion), by Service Type 2026 & 2034
Figure 11: Europe Electric Service Revenue Share (%), by Service Type 2026 & 2034
Figure 12: Europe Electric Service Revenue (Billion), by End User 2026 & 2034
Figure 13: Europe Electric Service Revenue Share (%), by End User 2026 & 2034
Figure 14: Europe Electric Service Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe Electric Service Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Electric Service Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe Electric Service Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Electric Service Revenue (Billion), by Service Type 2026 & 2034
Figure 19: Asia Pacific Electric Service Revenue Share (%), by Service Type 2026 & 2034
Figure 20: Asia Pacific Electric Service Revenue (Billion), by End User 2026 & 2034
Figure 21: Asia Pacific Electric Service Revenue Share (%), by End User 2026 & 2034
Figure 22: Asia Pacific Electric Service Revenue (Billion), by Application 2026 & 2034
Figure 23: Asia Pacific Electric Service Revenue Share (%), by Application 2026 & 2034
Figure 24: Asia Pacific Electric Service Revenue (Billion), by Country 2026 & 2034
Figure 25: Asia Pacific Electric Service Revenue Share (%), by Country 2026 & 2034
Figure 26: South America Electric Service Revenue (Billion), by Service Type 2026 & 2034
Figure 27: South America Electric Service Revenue Share (%), by Service Type 2026 & 2034
Figure 28: South America Electric Service Revenue (Billion), by End User 2026 & 2034
Figure 29: South America Electric Service Revenue Share (%), by End User 2026 & 2034
Figure 30: South America Electric Service Revenue (Billion), by Application 2026 & 2034
Figure 31: South America Electric Service Revenue Share (%), by Application 2026 & 2034
Figure 32: South America Electric Service Revenue (Billion), by Country 2026 & 2034
Figure 33: South America Electric Service Revenue Share (%), by Country 2026 & 2034
Figure 34: Middle East & Africa Electric Service Revenue (Billion), by Service Type 2026 & 2034
Figure 35: Middle East & Africa Electric Service Revenue Share (%), by Service Type 2026 & 2034
Figure 36: Middle East & Africa Electric Service Revenue (Billion), by End User 2026 & 2034
Figure 37: Middle East & Africa Electric Service Revenue Share (%), by End User 2026 & 2034
Figure 38: Middle East & Africa Electric Service Revenue (Billion), by Application 2026 & 2034
Figure 39: Middle East & Africa Electric Service Revenue Share (%), by Application 2026 & 2034
Figure 40: Middle East & Africa Electric Service Revenue (Billion), by Country 2026 & 2034
Figure 41: Middle East & Africa Electric Service Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Electric Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 2: Global Electric Service Revenue Billion Forecast, by End User 2020 & 2034
Table 3: Global Electric Service Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Global Electric Service Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America Electric Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 6: North America Electric Service Revenue Billion Forecast, by End User 2020 & 2034
Table 7: North America Electric Service Revenue Billion Forecast, by Application 2020 & 2034
Table 8: North America Electric Service Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe Electric Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 13: Europe Electric Service Revenue Billion Forecast, by End User 2020 & 2034
Table 14: Europe Electric Service Revenue Billion Forecast, by Application 2020 & 2034
Table 15: Europe Electric Service Revenue Billion Forecast, by Country 2020 & 2034
Table 16: Germany Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: UK Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: France Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Italy Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Spain Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Rest of Europe Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Asia Pacific Electric Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 23: Asia Pacific Electric Service Revenue Billion Forecast, by End User 2020 & 2034
Table 24: Asia Pacific Electric Service Revenue Billion Forecast, by Application 2020 & 2034
Table 25: Asia Pacific Electric Service Revenue Billion Forecast, by Country 2020 & 2034
Table 26: China Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Japan Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: India Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Australia Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: South Korea Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Asia Pacific Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: South America Electric Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 33: South America Electric Service Revenue Billion Forecast, by End User 2020 & 2034
Table 34: South America Electric Service Revenue Billion Forecast, by Application 2020 & 2034
Table 35: South America Electric Service Revenue Billion Forecast, by Country 2020 & 2034
Table 36: Brazil Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Argentina Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Rest of South America Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Middle East & Africa Electric Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 40: Middle East & Africa Electric Service Revenue Billion Forecast, by End User 2020 & 2034
Table 41: Middle East & Africa Electric Service Revenue Billion Forecast, by Application 2020 & 2034
Table 42: Middle East & Africa Electric Service Revenue Billion Forecast, by Country 2020 & 2034
Table 43: Saudi Arabia Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: UAE Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: South Africa Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 46: Rest of Middle East & Africa Electric Service Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the Electric Service market?
The global Electric Service market was valued at USD 802.31 Billion in 2025, according to our proprietary research. It is projected to reach USD 1,159.6 Billion by 2035, growing at a CAGR of 3.75%.
2Which region is the fastest-growing in the Electric Service market?
Asia-Pacific is the fastest-growing region, expected to account for 42% of the global market by 2035. This growth is driven by rapid industrialization, urbanization, and investments in renewable energy infrastructure.
3What are the key drivers of the Electric Service market?
Key drivers include rising demand for renewable energy, increased focus on energy efficiency, regulatory compliance requirements, urbanization and infrastructure development, and technological advancements such as smart grids and automation.
4Who are the major players in the Electric Service market?
Leading companies include Schneider Electric, Siemens, General Electric, Eaton, ABB, Honeywell, Emerson Electric, Rockwell Automation, and Mitsubishi Electric, among others.
5What is the largest service type segment in the Electric Service market?
Installation is the largest service type segment, accounting for the majority of market revenue. However, the repair and maintenance segment is the fastest-growing, driven by aging infrastructure and predictive maintenance needs.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of data in this report was gathered through primary research, including in-depth interviews with C-level executives, procurement directors, project managers, and electrical engineers across the value chain. We conducted over 150 interviews with stakeholders from electrical service providers, equipment manufacturers, and end-user industries.
Company types interviewed include: electrical contractors (35%), engineering and consulting firms (25%), equipment and component suppliers (20%), end users (15%), and industry associations (5%).
Stakeholder roles included: Procurement Director (30%), Chief Technology Officer (25%), Project Manager (20%), Electrical Engineer (15%), and Operations Director (10%).
Primary research was conducted via computer-assisted telephone interviewing (CATI) and face-to-face meetings, with data collected on service volumes, pricing, contract structures, and technology adoption.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook were used to validate company financials, M&A activity, and market valuations.
All secondary sources were cross-referenced with primary research findings to ensure consistency and accuracy.
Demand Modeling & Market Estimation
We employed both top-down and bottom-up methodologies simultaneously. The bottom-up approach involved estimating market size by aggregating revenue from individual service providers, segmented by service type, end user, and region. The top-down approach utilized macroeconomic indicators, infrastructure spending, and industry benchmarks to validate the bottom-up estimates.
Quantitative metrics used in the bottom-up calculation included: number of electrical service contracts awarded, average contract value, service revenue per employee, and capital expenditure on electrical infrastructure.
Multi-level data triangulation was performed by comparing primary interview data, secondary trade statistics, and financial filings to reconcile discrepancies and derive a robust market estimate.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous validation procedures. All data points were verified through at least two independent sources.
A senior analyst review was conducted for each segment and region, and any outliers were re-examined with follow-up interviews.
The report is updated to the date of purchase, ensuring that clients receive the most current market intelligence. Our team continuously monitors market developments and incorporates new data as it becomes available.
Quality assurance protocols include cross-checking of all calculations, verification of source credibility, and a final audit by our research director.