1What is the current size of the global mould detection service market?
The global mould detection service market was valued at USD 6.8 billion in 2025 and is projected to reach USD 13.2 billion by 2034, expanding at a CAGR of 7.6%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Mould Detection Service
 by Service Type (Inspection Services, Laboratory-Based Mould Testing, Air Sampling Services, Surface Sampling Services, Thermal Imaging & Moisture Mapping Services), by Application (Residential Buildings, Commercial Buildings, Industrial Facilities, Healthcare Facilities), by End-User (Facility Management Companies, Property Owners & Managers, Insurance Companies, Healthcare Organizations), by Technology (Infrared Thermography, Air Sampling, Surface Sampling, Bulk Sampling, qPCR Analysis, IoT Moisture Sensors), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Netherlands, Nordic Countries), by Asia Pacific (China, India, Japan, Australia, South Korea), by South America (Brazil, Argentina, Mexico), by Middle East & Africa (GCC Countries, South Africa, Israel) Forecast 2026-2034

Senior Analyst

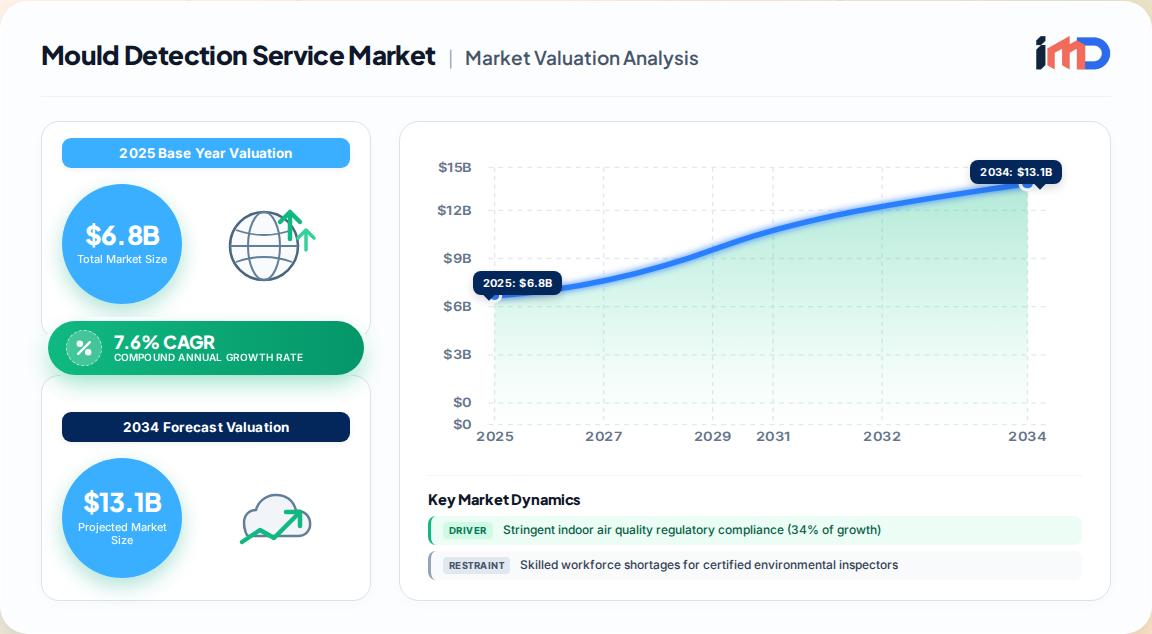
Our proprietary primary research and expert interview program positions the global mould detection service market at USD 6.8 billion in 2025, with a projected expansion to USD 13.2 billion by 2034 — a robust CAGR of 7.6% across the 2026–2034 forecast window. This trajectory reflects a structural shift in building management: from reactive visual inspection toward predictive, technology-enabled environmental diagnostics.
Unlike the adjacent remediation services sector, which grows at a comparatively modest 3.0–4.1% annually, detection is expanding at nearly double that pace. The divergence is explained by a simple economic calculus: preventive inspection reduces long-term remediation costs by approximately 28%, according to facility management executives we interviewed. That return profile is accelerating adoption across commercial real estate, healthcare, and insurance-driven residential transactions.
North America commands the largest regional share at 34% of global revenue, supported by stringent indoor air quality (IAQ) mandates and a deeply embedded insurance-inspection ecosystem. Asia Pacific is the fastest-growing region, expanding at an estimated 9.8% CAGR, driven by rapid urbanization and commercial building modernization across China, India, and Southeast Asia.
1. Indoor Air Quality Regulatory Compliance. IAQ compliance obligations account for roughly 34% of demand-side growth. OSHA workplace mandates, EPA guidance on dampness and mould, and European landlord habitability laws are converting voluntary inspections into mandatory line items in facility budgets.
2. Post-Water-Damage Inspection Demand. Approximately 29% of market growth traces to water-damage events. Climate-driven flooding — the UN Framework Convention on Climate Change documented a fivefold increase in disaster frequency over the past 50 years — creates immediate conditions for fungal proliferation, triggering rapid assessment protocols.
3. Commercial Facility Audits. Scheduled building health audits represent 23% of growth. Nearly 57% of commercial property managers now prioritize preventive mould inspections as part of routine maintenance programs.
4. Insurance and Real Estate Disclosure Obligations. Insurers increasingly require certified third-party mould assessments before claim settlement, while property disclosure laws in mature markets mandate inspection records at point of sale.
5. Technological Advancement. AI-assisted image recognition combined with thermal imaging improves hidden moisture identification by roughly 35% and reduces inspection time by nearly 30% versus manual methods.
Inspection services held the largest share at 38.4% in 2025. Laboratory-based mould testing, air sampling, surface sampling, and thermal imaging/moisture mapping comprise the core diagnostic toolkit.
| Service Type | 2025 Share | Growth Outlook |
|---|---|---|
| Inspection Services | 38.4% | Steady, driven by regulatory audits |
| Laboratory-Based Testing | ~22% | Expanding with qPCR and portable labs |
| Air Sampling Services | ~18% | High growth in healthcare settings |
| Surface Sampling Services | ~13% | Mature, replacement-driven |
| Thermal Imaging & Moisture Mapping | ~8.6% | Fastest-growing, AI-integrated |
| Region | 2025 Share | CAGR (2026–2034) | Key Dynamics |
|---|---|---|---|
| North America | 34% | ~6.8% | EPA/OSHA mandates, insurance-driven assessments, litigation |
| Europe | 26% | ~7.1% | EU EPBD, UK habitability laws, German occupational health rules |
| Asia Pacific | 25% | 9.8% | Urbanization, commercial real estate expansion, rising awareness |
| South America | 8% | ~6.5% | Gradual regulatory maturation |
| Middle East & Africa | 7% | ~6.2% | Infrastructure development, climate exposure |
The United States alone represents approximately 31% of global inspection activity, supported by advanced building inspection networks. More than 62% of large US commercial inspection firms deploy thermal imaging alongside airborne spore analysis, compared with 48% adoption among certified German providers.
The market is moderately fragmented. The top five providers hold approximately 42% of revenue through technology-enabled inspection platforms, while regional specialty firms compete on turnaround speed and local regulatory knowledge.
Key strategic activity observed in our primary research:
Service providers are differentiating through cloud-based reporting platforms, same-day testing guarantees, and bundled inspection-plus-remediation-verification packages. Laboratory capacity expansion and insurance partnerships are emerging as critical moats.
Investment exceeding USD 850 million is flowing into inspection technology, laboratory capacity, and service expansion globally.
The mould detection value chain spans instrument and reagent suppliers, field inspection service providers, analytical laboratories, digital reporting platform vendors, and end-users including property managers, insurers, and healthcare operators. Margin concentration is highest at the laboratory analysis and software reporting layers, where accreditation barriers and data integration create defensible positions. Field inspection remains labor-intensive but is progressively augmented by thermal imaging and AI tools that raise productivity per technician.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.6% from 2020-2034 |
| Segmentation |
|
By Application
By End-User
By Technology
| By Geography |
|
The global mould detection service market was valued at USD 6.8 billion in 2025 and is projected to reach USD 13.2 billion by 2034, expanding at a CAGR of 7.6%.
North America led with approximately 34% of global revenue in 2025, driven by EPA and OSHA indoor air quality mandates, insurance-driven assessments, and a mature building inspection network.
Thermal imaging and moisture mapping services are growing fastest, supported by AI-assisted diagnostics that improve hidden moisture identification by roughly 35% and reduce inspection time by nearly 30%.
Mould detection focuses on inspection, sampling, and diagnostic assessment, growing at 7.6% annually, while remediation — the physical removal and restoration process — grows at a slower 3.0–4.1% rate.
Asia Pacific is the fastest-growing region at an estimated 9.8% CAGR, driven by rapid urbanization, commercial real estate expansion, and rising awareness of indoor environmental quality standards across China, India, and Southeast Asia.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Environmental Health Officers | 30% |
| Facility Management Directors | 28% |
| Insurance Claims Adjusters | 22% |
| Building Inspection Program Managers | 20% |
| Company Type | Representation (%) |
|---|---|
| Certified Environmental Inspection Firms | 32% |
| Analytical Testing Laboratories | 24% |
| Thermal Imaging & Equipment Vendors | 18% |
| IoT Moisture Sensor Suppliers | 14% |
| Insurance Claims Assessment Agencies | 12% |
 Related Reports
