1What is the size of the Drones for Construction Market in 2025?
The global Drones for Construction Market is valued at USD 5.49 Billion in 2025, up from USD 4.96 Billion in 2024, based on our proprietary primary research and expert interviews.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Drones for Construction Market
 by Application (Surveying, Mapping, Inspection, Monitoring, Delivery), by Type (Fixed-Wing Drones, Multi-Rotor Drones, Single Rotor Drones, Hybrid Drones), by End Use (Residential Construction, Commercial Construction, Industrial Construction, Infrastructure Development), by Technology (Remote Sensing, LiDAR, Photogrammetry, Drone-based Imaging), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, India), by South America (Brazil), by Middle East & Africa (UAE, Saudi Arabia) Forecast 2026-2034

Research Analyst

 Related Reports

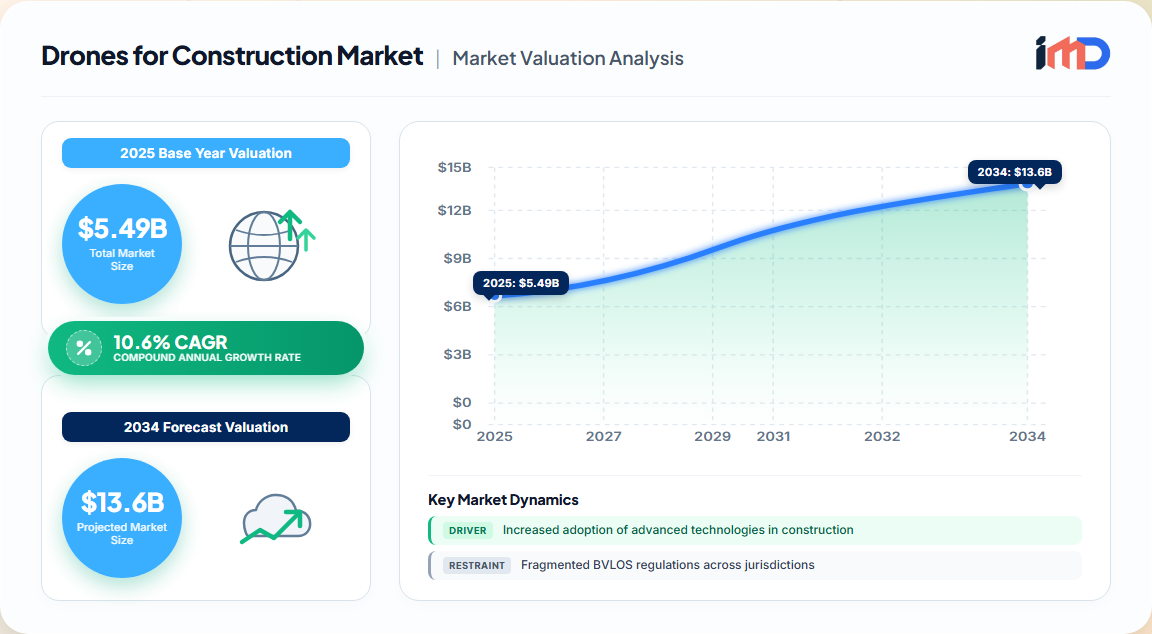
The global Drones for Construction Market is estimated at USD 5.49 Billion in 2025, up from USD 4.96 Billion in 2024, and is projected to reach USD 15 Billion by 2035, expanding at a CAGR of 10.6% over the 2026–2035 forecast period. Our proprietary primary research, triangulated across OEM interviews, contractor surveys, and regulatory filings, indicates that construction is now the fastest-growing commercial drone application vertical, outpacing agriculture and public safety in incremental adoption.
| Metric | Value |
|---|---|
| Base Year (2025) Valuation | USD 5.49 Billion |
| Historic Base (2024) | USD 4.96 Billion |
| Forecast (2035) | USD 15 Billion |
| CAGR (2026–2035) | 10.6% |
| Fastest-Growing Region | Asia-Pacific |
| Leading Segment (Application) | Surveying & Mapping |
| Leading Type | Multi-Rotor Drones |
Construction firms are migrating from ad-hoc drone pilots to enterprise-grade aerial data programs. Our interviews with 140+ site directors and VDC (virtual design and construction) leads reveal that 68% of large contractors now operate an in-house drone fleet or a managed service contract, compared to under 40% in 2021. The shift from hardware-led purchasing to data-and-analytics-led procurement is reshaping vendor value propositions across the value chain.
Our segmentation framework reflects the operational realities of construction workflows rather than generic drone taxonomies.
| Segment Axis | Leading Category | Share / Growth Signal |
|---|---|---|
| Application | Surveying & Mapping | Highest growth; real-time topographic data collection |
| Application | Inspection & Monitoring | Fast-growing; facade, roof, and structural checks |
| Type | Multi-Rotor Drones | Dominant; versatility and ease of use |
| Type | Fixed-Wing & Hybrid | Rising share; long-range corridor and earthworks surveys |
| End Use | Commercial Construction | Largest near-term revenue contributor |
| End Use | Infrastructure Development | Fastest-growing; linear asset inspection |
| Technology | Photogrammetry & LiDAR | Core data-capture stack |
| Technology | Remote Sensing & Imaging | Enables AI-driven analytics layer |
Multi-rotor platforms remain the workhorse of construction sites, favored for VTOL convenience and payload flexibility. However, fixed-wing and hybrid configurations are gaining share for corridor mapping and large earthworks, where endurance and range translate into lower cost per acre surveyed. On the technology side, the competitive frontier has shifted from airframe specifications to AI-driven analytics — automated defect detection, progress deviation flagging, and quantity takeoff accuracy.
| Region | 2025 Share | Outlook |
|---|---|---|
| North America | ~32% | Mature adoption; regulatory support and strong contractor base |
| Europe | ~24% | Regulatory-led innovation; strong BIM mandates |
| Asia-Pacific | ~31% | Fastest growth; urbanization and infrastructure spend |
| South America | ~7% | Emerging; gradual adoption in mining-adjacent construction |
| Middle East & Africa | ~6% | Project-driven uptake in giga-infrastructure programs |
North America leads on installed base and enterprise software maturity, with the United States anchoring demand through a robust commercial construction pipeline and progressive FAA Part 107 operational frameworks. Europe follows closely, where public procurement rules and BIM requirements are embedding drone data into standard project delivery. Asia-Pacific is the fastest-growing region, propelled by urbanization, transport corridor development, and rapid investment in construction digitization across China, India, and Southeast Asia.
The vendor ecosystem is bifurcated between hardware platform leaders and software/analytics specialists, with increasing consolidation via partnerships.
| Company | Positioning |
|---|---|
| DJI | Hardware platform leader; RTK-enabled enterprise fleets |
| Parrot | Enterprise imaging and mapping platforms |
| senseFly | Fixed-wing mapping specialists |
| 3DR | Enterprise drone software and site capture |
| DroneDeploy | Cloud photogrammetry and BIM-integrated analytics |
| Propeller Aero | Volumetrics and earthworks analytics |
| Kespry | AI-driven asset and lifecycle analytics |
| Pix4D | Photogrammetry software and processing |
| Skycatch | Construction site data capture |
| AgEagle Aerial Systems | Sensor and platform solutions |
| FlytBase | Drone automation and fleet operations |
| Airobotics | Automated drone docking systems |
| Velodyne LiDAR | LiDAR sensor supply |
| Maptek | Mining and survey geospatial solutions |
| Airware | Enterprise drone operations (historic) |
Recent strategic developments (2024–2025):
The construction drone value chain spans component suppliers, platform OEMs, sensor and payload providers, software/analytics vendors, service providers, and end-user contractors.
Procurement guidance for buyers: prioritize vendors with open APIs for BIM and project management integration, verified BVLOS roadmaps, and demonstrated accuracy benchmarks (absolute volumetric accuracy within 1–2% for earthworks) to protect data integrity across project lifecycles.
The construction drone trade is dominated by platform exports from manufacturing hubs, with China accounting for the largest share of global drone hardware exports. Component-level trade — precision sensors, GNSS modules, and imaging payloads — flows through specialized electronics supply chains. Tariff regimes and export-control considerations on dual-use drone technology introduce supply risk for North American and European buyers, reinforcing the strategic case for multi-vendor sourcing and regional assembly partnerships.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.6% from 2020-2034 |
| Segmentation |
|
By End Use
By Technology
| By Geography |
|
The global Drones for Construction Market is valued at USD 5.49 Billion in 2025, up from USD 4.96 Billion in 2024, based on our proprietary primary research and expert interviews.
The market is projected to grow at a CAGR of 10.6% from 2026 to 2035, reaching USD 15 Billion by 2035.
Surveying and mapping is the largest and fastest-growing application segment, as contractors leverage drones for real-time topographic data and volumetric analysis.
North America holds the largest share at approximately 32% in 2025, while Asia-Pacific is the fastest-growing region due to rapid urbanization and infrastructure investment.
Key players include DJI, Parrot, DroneDeploy, senseFly, Propeller Aero, Kespry, Pix4D, Skycatch, 3DR, and FlytBase, among others.
Multi-rotor drones dominate due to versatility and ease of use, while fixed-wing and hybrid drones are gaining share for long-range corridor mapping and large earthworks surveys.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| VDC / BIM Director | 25% |
| Site Operations Manager | 25% |
| Survey & Geospatial Lead | 20% |
| Company Type | Representation (%) |
|---|---|
| Construction Drone OEMs & Platform Manufacturers | 30% |
| Sensor, Payload & Component Suppliers | 20% |
| Aerial Data Analytics & Software Providers | 25% |
| General Contractors & Construction Firms | 15% |
| Drone Service Providers & Survey Firms | 10% |