Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Deception Technology Service Market Size & CAGR Forecast
Independent Intelligence for decisions that move markets
Professional and Commercial Services / MARKET REPORT
Deception Technology Service | Insight Market Data
Deception Technology Service by Component (Solution, Service), by Deception Stack (Network Security, Application Security, Endpoint Security, Data Security), by Deployment (On-Premise, Cloud-Based), by Organization Size (Small and Medium Enterprises, Large Enterprises), by Vertical (BFSI, Healthcare, Government, Telecom and IT, Manufacturing, Retail, Energy and Utilities, Other Verticals), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Southeast Asia), by South America (Brazil, Rest of South America), by Middle East & Africa (GCC, Rest of MEA) Forecast 2026-2034
Commissioning service market to reach $11.17B by 2034 at 6.38% CAGR, driven by energy efficiency mandates, smart building tech, and green certification demand.
Nov 2026|277 pages
$2900.00
The strategy consulting service market is valued at USD 77.53 billion in 2026, growing at 4.25% CAGR to reach USD 95.49 billion by 2031.
Nov 2026|272 pages
$2900.00
B2B Demand Generation Service market to reach $15B by 2033 at 10.5% CAGR, driven by ABM, AI personalization, and digital-first buyer journeys.
Nov 2026|209 pages
$2900.00
Global mould detection service market valued at $6.8B in 2025, projected to reach $13.2B by 2034 at 7.6% CAGR. AI diagnostics, IAQ compliance, and thermal imaging drive growth.
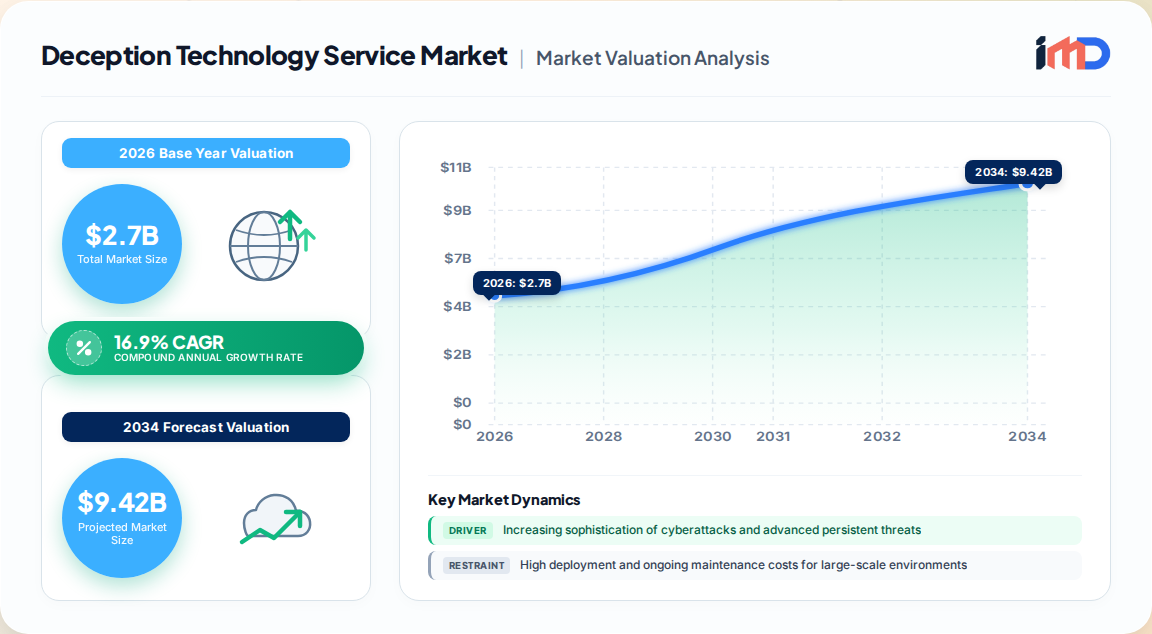
The global deception technology service market is firmly in an expansionary phase. Our proprietary first-party research estimates the total deception technology market at USD 2.7 billion in 2026, on a trajectory to reach USD 7.9 billion by 2033, expanding at a CAGR of 16.9%. Services — spanning professional deployment, managed deception operations, incident-response enablement and threat-intelligence subscriptions — represent the fastest-compounding layer of this value pool, growing ahead of the broader solution hardware/software component as enterprises shift from one-time decoy purchases to continuous, expert-operated deception programmes.
Deception Technology Service Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
2.310 B
2025
2.700 B
2026
3.156 B
2027
3.690 B
2028
4.313 B
2029
5.042 B
2030
5.894 B
2031
Services today account for a mid-thirty-percent share of total deception spend, but this share is rising as buyers confront a persistent operational reality: decoys only deliver value when continuously tuned to mirror live production environments. That maintenance burden is precisely what is fuelling managed and professionalised service demand.
Services growth: outpacing total market, with managed deception forecast to grow at roughly 16% annual clip and sustain momentum beyond 2030.
Deployment mix: on-premise still dominant at 61.2% of revenue, though cloud-hosted deception-as-a-service is the share-gainer as enterprises modernise.
Vertical concentration: BFSI leads at 22.4% of revenue, followed by healthcare, government, telecom/IT and energy.
Market Dynamics Shaping Service Demand
Growth Drivers
Escalating adversarial sophistication. Ransomware, fileless malware, identity-based attacks and advanced persistent threats (APTs) routinely evade perimeter and signature controls. Deception services convert this gap into high-confidence detection: legitimate users never touch decoys, so service providers can deliver near-zero-false-positive alerting and rapid containment.
Zero-trust and hybrid-IT expansion. As organisations distribute workloads across cloud, on-premise and OT networks, the attack surface multiplies. Service providers that can map, deploy and monitor decoys across these estates become a scalable extension of lean security teams.
Regulatory and cyber-insurance pressure. GDPR, CCPA, HIPAA and sector-specific mandates reward reduced breach dwell time and demonstrable proactive monitoring — outcomes deception services are explicitly designed to evidence.
AI and security automation. Machine-learning-driven decoy adaptation, automated threat prioritisation and SOAR integration shrink manual overhead and are the single strongest accelerant of managed-service economics.
Restraints and Challenges
Cost and complexity at scale. Large distributed environments demand extensive planning, continuous monitoring and integration with identity, cloud and OT systems — raising implementation and recurring service costs.
Skilled-talent scarcity. Deception engineering is niche; providers face wage and retention pressure that constrains service margin and delivery capacity.
Perceived overlap with EDR/XDR. Buyers frequently question incremental value versus existing detection stacks, requiring providers to prove measurable MTTR and false-positive reductions.
Driver
Impact on Service Demand
APT and lateral-movement detection
High — core use case for continuous deception operations
Zero-trust adoption
High — decoys embedded in identity and network segmentation
AI/ML automation
Very High — lowers managed-service cost-to-serve
Regulatory compliance
Medium-High — evidence generation for audits and insurers
Value Chain Analysis
Technology platform vendors license decoy engines, deception grids and threat-analytics cores to service providers and enterprises.
Professional services firms deliver architecture design, decoy mapping, integration and training/simulation exercises.
Managed deception providers (MSSPs) operate and tune deception environments as a recurring subscription, escalating real detections to client SOCs.
Threat-intelligence and enrichment suppliers feed attacker TTP and indicator data that refine decoy realism.
End-user security operations teams consume alerts, incident reports and readiness scoring.
Service value concentrates in the operational and intelligence layers — where recurring revenue and margin are highest — while the platform layer increasingly commoditises.
Segmentation Outlook
By component: Solutions hold the larger share (~64–67%), but services are the faster-growing component as managed and professional engagements scale.
By deception stack: Network security leads (roughly one-third of stack spend), with data security, endpoint and application security following; data security alone represented 31.0% of 2025 stack revenue. Services attach most heavily to network and data deception.
By deployment: On-premise currently 61.2%, but cloud-hosted deception services are the structural growth vector.
By organisation size: SMEs form the largest adopting cohort (67.5% in one segment read), and are the most service-dependent, lacking in-house deception engineering; large enterprises lead in absolute spend and managed-programme sophistication.
By vertical: BFSI (~22%), healthcare, government, telecom/IT, manufacturing and retail.
Regional Outlook
North America leads with roughly 34–38% revenue share, anchored by US federal defence deception-grid programmes and mature BFSI/healthcare adoption; the US alone is a multi-billion-dollar opportunity by 2030.
Asia-Pacific is the fastest-growing region, forecast to compound near 20% and become the largest regional market by value around 2030, driven by critical-infrastructure protection in China, India, Japan, South Korea and Southeast Asia.
Europe advances on regulatory rigour and public-sector cyber-resilience mandates; OLAF-style cross-border enforcement cooperation underscores demand for proactive counter-fraud and anti-illicit-trade monitoring — adjacent use cases for deception-based detection.
Middle East & Africa and South America represent emerging white-space, led by government and energy-sector security modernisation.
Region
Position
Service Opportunity
North America
Largest, mature
Managed deception and federal-grade programmes
Asia-Pacific
Fastest-growing
Cloud-native, MSP-led deception-as-a-service
Europe
Regulation-led
Compliance-driven monitoring and training services
MEA / South America
Emerging
Government and critical-infrastructure pilots
Deception Technology Service Regional Market Share
Loading chart...
Global Trade Analysis & Supply Chain Risk Assessment
Deception technology is software- and expertise-led; cross-border value flows primarily through professional and managed-service contracts rather than physical goods.
Emerging-market imports of deception tooling have grown strongly, reflecting a roughly 15% annual increase in solution inflows, while US-origin exports of deception solutions scaled toward hundreds of millions of dollars annually by decade-end.
Key risks: dependency on specialised deception engineers, exposure to cloud-region concentration, and procurement delays in regulated sectors. Providers should build multi-region delivery capacity and cross-train SOC staff to mitigate.
Strategic White-Space & Competitive Strategy
Ansoff lens: Market penetration via SME-focused managed tiers; product development through AI-driven adaptive decoy automation; market development into OT/ICS and healthcare IoT deception; diversification into anti-fraud and illicit-trade monitoring.
Highest-value white-space: managed deception for mid-market BFSI and healthcare, deception-enabled security-awareness simulation, and deception-as-a-service bundled into zero-trust transformation programmes.
Winning strategies: outcome-based pricing tied to MTTR and detection fidelity; SOAR/identity-vendor ecosystem integration; verticalised decoy libraries; and modular service bundles that let buyers start small and scale.
Organisations that pair realistic deception with continuous expert operation will capture disproportionate share of the USD 7.9 billion 2033 opportunity.
Deception Technology Service Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Deception Technology Service REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 16.9% from 2020-2034
Segmentation
By Component
Solution
Service
By Deception Stack
Network Security
Application Security
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Increasing sophistication of cyberattacks and advanced persistent threats
3.1.2. Rising adoption of zero-trust and hybrid-IT security frameworks
3.1.3. Regulatory and cyber-insurance pressure for proactive threat detection
3.1.4. Integration of AI and security automation in deception platforms
3.2. Market Trends
3.2.1. AI/ML-driven adaptive decoys and automated threat prioritisation
3.2.2. Shift from on-premise decoys to cloud-hosted deception-as-a-service
3.2.3. Embedding deception within zero-trust and identity-security architectures
3.2.4. Growth of managed deception services for resource-constrained SMEs
3.3. Market Restrains
3.3.1. High deployment and ongoing maintenance costs for large-scale environments
3.3.2. Shortage of specialised deception engineering talent
3.4. Market Restraints
3.4.1. High deployment and ongoing maintenance costs for large-scale environments
3.4.2. Shortage of specialised deception engineering talent
Endpoint Security
Data Security
By Deployment
On-Premise
Cloud-Based
By Organization Size
Small and Medium Enterprises
Large Enterprises
By Vertical
BFSI
Healthcare
Government
Telecom and IT
Manufacturing
Retail
Energy and Utilities
Other Verticals
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
South America
Brazil
Rest of South America
Middle East & Africa
GCC
Rest of MEA
3.5. Market Challenges
3.5.1. Perceived overlap with EDR/XDR and detection-stack consolidation
3.5.2. Complex integration across cloud, identity and OT environments
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Solution
5.1.2. Service
5.2. Market Analysis, Insights and Forecast - by Deception Stack
5.2.1. Network Security
5.2.2. Application Security
5.2.3. Endpoint Security
5.2.4. Data Security
5.3. Market Analysis, Insights and Forecast - by Deployment
5.3.1. On-Premise
5.3.2. Cloud-Based
5.4. Market Analysis, Insights and Forecast - by Organization Size
5.4.1. Small and Medium Enterprises
5.4.2. Large Enterprises
5.5. Market Analysis, Insights and Forecast - by Vertical
5.5.1. BFSI
5.5.2. Healthcare
5.5.3. Government
5.5.4. Telecom and IT
5.5.5. Manufacturing
5.5.6. Retail
5.5.7. Energy and Utilities
5.5.8. Other Verticals
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Solution
6.1.2. Service
6.2. Market Analysis, Insights and Forecast - by Deception Stack
6.2.1. Network Security
6.2.2. Application Security
6.2.3. Endpoint Security
6.2.4. Data Security
6.3. Market Analysis, Insights and Forecast - by Deployment
6.3.1. On-Premise
6.3.2. Cloud-Based
6.4. Market Analysis, Insights and Forecast - by Organization Size
6.4.1. Small and Medium Enterprises
6.4.2. Large Enterprises
6.5. Market Analysis, Insights and Forecast - by Vertical
6.5.1. BFSI
6.5.2. Healthcare
6.5.3. Government
6.5.4. Telecom and IT
6.5.5. Manufacturing
6.5.6. Retail
6.5.7. Energy and Utilities
6.5.8. Other Verticals
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Solution
7.1.2. Service
7.2. Market Analysis, Insights and Forecast - by Deception Stack
7.2.1. Network Security
7.2.2. Application Security
7.2.3. Endpoint Security
7.2.4. Data Security
7.3. Market Analysis, Insights and Forecast - by Deployment
7.3.1. On-Premise
7.3.2. Cloud-Based
7.4. Market Analysis, Insights and Forecast - by Organization Size
7.4.1. Small and Medium Enterprises
7.4.2. Large Enterprises
7.5. Market Analysis, Insights and Forecast - by Vertical
7.5.1. BFSI
7.5.2. Healthcare
7.5.3. Government
7.5.4. Telecom and IT
7.5.5. Manufacturing
7.5.6. Retail
7.5.7. Energy and Utilities
7.5.8. Other Verticals
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Solution
8.1.2. Service
8.2. Market Analysis, Insights and Forecast - by Deception Stack
8.2.1. Network Security
8.2.2. Application Security
8.2.3. Endpoint Security
8.2.4. Data Security
8.3. Market Analysis, Insights and Forecast - by Deployment
8.3.1. On-Premise
8.3.2. Cloud-Based
8.4. Market Analysis, Insights and Forecast - by Organization Size
8.4.1. Small and Medium Enterprises
8.4.2. Large Enterprises
8.5. Market Analysis, Insights and Forecast - by Vertical
8.5.1. BFSI
8.5.2. Healthcare
8.5.3. Government
8.5.4. Telecom and IT
8.5.5. Manufacturing
8.5.6. Retail
8.5.7. Energy and Utilities
8.5.8. Other Verticals
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Solution
9.1.2. Service
9.2. Market Analysis, Insights and Forecast - by Deception Stack
9.2.1. Network Security
9.2.2. Application Security
9.2.3. Endpoint Security
9.2.4. Data Security
9.3. Market Analysis, Insights and Forecast - by Deployment
9.3.1. On-Premise
9.3.2. Cloud-Based
9.4. Market Analysis, Insights and Forecast - by Organization Size
9.4.1. Small and Medium Enterprises
9.4.2. Large Enterprises
9.5. Market Analysis, Insights and Forecast - by Vertical
9.5.1. BFSI
9.5.2. Healthcare
9.5.3. Government
9.5.4. Telecom and IT
9.5.5. Manufacturing
9.5.6. Retail
9.5.7. Energy and Utilities
9.5.8. Other Verticals
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Solution
10.1.2. Service
10.2. Market Analysis, Insights and Forecast - by Deception Stack
10.2.1. Network Security
10.2.2. Application Security
10.2.3. Endpoint Security
10.2.4. Data Security
10.3. Market Analysis, Insights and Forecast - by Deployment
10.3.1. On-Premise
10.3.2. Cloud-Based
10.4. Market Analysis, Insights and Forecast - by Organization Size
10.4.1. Small and Medium Enterprises
10.4.2. Large Enterprises
10.5. Market Analysis, Insights and Forecast - by Vertical
10.5.1. BFSI
10.5.2. Healthcare
10.5.3. Government
10.5.4. Telecom and IT
10.5.5. Manufacturing
10.5.6. Retail
10.5.7. Energy and Utilities
10.5.8. Other Verticals
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Deception platform vendors
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Managed security service providers (MSSPs)
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Security systems integrators
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Cloud security consultancies
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Threat-intelligence enrichment suppliers
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Deception Technology Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Deception Technology Service Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Deception Technology Service Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Deception Technology Service Revenue (Billion), by Deception Stack 2026 & 2034
Figure 5: North America Deception Technology Service Revenue Share (%), by Deception Stack 2026 & 2034
Figure 6: North America Deception Technology Service Revenue (Billion), by Deployment 2026 & 2034
Figure 7: North America Deception Technology Service Revenue Share (%), by Deployment 2026 & 2034
Figure 8: North America Deception Technology Service Revenue (Billion), by Organization Size 2026 & 2034
Figure 9: North America Deception Technology Service Revenue Share (%), by Organization Size 2026 & 2034
Figure 10: North America Deception Technology Service Revenue (Billion), by Vertical 2026 & 2034
Figure 11: North America Deception Technology Service Revenue Share (%), by Vertical 2026 & 2034
Figure 12: North America Deception Technology Service Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Deception Technology Service Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Deception Technology Service Revenue (Billion), by Component 2026 & 2034
Figure 15: Europe Deception Technology Service Revenue Share (%), by Component 2026 & 2034
Figure 16: Europe Deception Technology Service Revenue (Billion), by Deception Stack 2026 & 2034
Figure 17: Europe Deception Technology Service Revenue Share (%), by Deception Stack 2026 & 2034
Figure 18: Europe Deception Technology Service Revenue (Billion), by Deployment 2026 & 2034
Figure 19: Europe Deception Technology Service Revenue Share (%), by Deployment 2026 & 2034
Figure 20: Europe Deception Technology Service Revenue (Billion), by Organization Size 2026 & 2034
Figure 21: Europe Deception Technology Service Revenue Share (%), by Organization Size 2026 & 2034
Figure 22: Europe Deception Technology Service Revenue (Billion), by Vertical 2026 & 2034
Figure 23: Europe Deception Technology Service Revenue Share (%), by Vertical 2026 & 2034
Figure 24: Europe Deception Technology Service Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Deception Technology Service Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Deception Technology Service Revenue (Billion), by Component 2026 & 2034
Figure 27: Asia Pacific Deception Technology Service Revenue Share (%), by Component 2026 & 2034
Figure 28: Asia Pacific Deception Technology Service Revenue (Billion), by Deception Stack 2026 & 2034
Figure 29: Asia Pacific Deception Technology Service Revenue Share (%), by Deception Stack 2026 & 2034
Figure 30: Asia Pacific Deception Technology Service Revenue (Billion), by Deployment 2026 & 2034
Figure 31: Asia Pacific Deception Technology Service Revenue Share (%), by Deployment 2026 & 2034
Figure 32: Asia Pacific Deception Technology Service Revenue (Billion), by Organization Size 2026 & 2034
Figure 33: Asia Pacific Deception Technology Service Revenue Share (%), by Organization Size 2026 & 2034
Figure 34: Asia Pacific Deception Technology Service Revenue (Billion), by Vertical 2026 & 2034
Figure 35: Asia Pacific Deception Technology Service Revenue Share (%), by Vertical 2026 & 2034
Figure 36: Asia Pacific Deception Technology Service Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Deception Technology Service Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Deception Technology Service Revenue (Billion), by Component 2026 & 2034
Figure 39: South America Deception Technology Service Revenue Share (%), by Component 2026 & 2034
Figure 40: South America Deception Technology Service Revenue (Billion), by Deception Stack 2026 & 2034
Figure 41: South America Deception Technology Service Revenue Share (%), by Deception Stack 2026 & 2034
Figure 42: South America Deception Technology Service Revenue (Billion), by Deployment 2026 & 2034
Figure 43: South America Deception Technology Service Revenue Share (%), by Deployment 2026 & 2034
Figure 44: South America Deception Technology Service Revenue (Billion), by Organization Size 2026 & 2034
Figure 45: South America Deception Technology Service Revenue Share (%), by Organization Size 2026 & 2034
Figure 46: South America Deception Technology Service Revenue (Billion), by Vertical 2026 & 2034
Figure 47: South America Deception Technology Service Revenue Share (%), by Vertical 2026 & 2034
Figure 48: South America Deception Technology Service Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Deception Technology Service Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Deception Technology Service Revenue (Billion), by Component 2026 & 2034
Figure 51: Middle East & Africa Deception Technology Service Revenue Share (%), by Component 2026 & 2034
Figure 52: Middle East & Africa Deception Technology Service Revenue (Billion), by Deception Stack 2026 & 2034
Figure 53: Middle East & Africa Deception Technology Service Revenue Share (%), by Deception Stack 2026 & 2034
Figure 54: Middle East & Africa Deception Technology Service Revenue (Billion), by Deployment 2026 & 2034
Figure 55: Middle East & Africa Deception Technology Service Revenue Share (%), by Deployment 2026 & 2034
Figure 56: Middle East & Africa Deception Technology Service Revenue (Billion), by Organization Size 2026 & 2034
Figure 57: Middle East & Africa Deception Technology Service Revenue Share (%), by Organization Size 2026 & 2034
Figure 58: Middle East & Africa Deception Technology Service Revenue (Billion), by Vertical 2026 & 2034
Figure 59: Middle East & Africa Deception Technology Service Revenue Share (%), by Vertical 2026 & 2034
Figure 60: Middle East & Africa Deception Technology Service Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Deception Technology Service Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Deception Technology Service Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Global Deception Technology Service Revenue Billion Forecast, by Deception Stack 2020 & 2034
Table 3: Global Deception Technology Service Revenue Billion Forecast, by Deployment 2020 & 2034
Table 4: Global Deception Technology Service Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 5: Global Deception Technology Service Revenue Billion Forecast, by Vertical 2020 & 2034
Table 6: Global Deception Technology Service Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Deception Technology Service Revenue Billion Forecast, by Component 2020 & 2034
Table 8: North America Deception Technology Service Revenue Billion Forecast, by Deception Stack 2020 & 2034
Table 9: North America Deception Technology Service Revenue Billion Forecast, by Deployment 2020 & 2034
Table 10: North America Deception Technology Service Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 11: North America Deception Technology Service Revenue Billion Forecast, by Vertical 2020 & 2034
Table 12: North America Deception Technology Service Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Deception Technology Service Revenue Billion Forecast, by Component 2020 & 2034
Table 17: Europe Deception Technology Service Revenue Billion Forecast, by Deception Stack 2020 & 2034
Table 18: Europe Deception Technology Service Revenue Billion Forecast, by Deployment 2020 & 2034
Table 19: Europe Deception Technology Service Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 20: Europe Deception Technology Service Revenue Billion Forecast, by Vertical 2020 & 2034
Table 21: Europe Deception Technology Service Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Germany Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Rest of Europe Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Asia Pacific Deception Technology Service Revenue Billion Forecast, by Component 2020 & 2034
Table 27: Asia Pacific Deception Technology Service Revenue Billion Forecast, by Deception Stack 2020 & 2034
Table 28: Asia Pacific Deception Technology Service Revenue Billion Forecast, by Deployment 2020 & 2034
Table 29: Asia Pacific Deception Technology Service Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 30: Asia Pacific Deception Technology Service Revenue Billion Forecast, by Vertical 2020 & 2034
Table 31: Asia Pacific Deception Technology Service Revenue Billion Forecast, by Country 2020 & 2034
Table 32: China Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Japan Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: India Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: South Korea Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Southeast Asia Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: South America Deception Technology Service Revenue Billion Forecast, by Component 2020 & 2034
Table 38: South America Deception Technology Service Revenue Billion Forecast, by Deception Stack 2020 & 2034
Table 39: South America Deception Technology Service Revenue Billion Forecast, by Deployment 2020 & 2034
Table 40: South America Deception Technology Service Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 41: South America Deception Technology Service Revenue Billion Forecast, by Vertical 2020 & 2034
Table 42: South America Deception Technology Service Revenue Billion Forecast, by Country 2020 & 2034
Table 43: Brazil Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: Rest of South America Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Middle East & Africa Deception Technology Service Revenue Billion Forecast, by Component 2020 & 2034
Table 46: Middle East & Africa Deception Technology Service Revenue Billion Forecast, by Deception Stack 2020 & 2034
Table 47: Middle East & Africa Deception Technology Service Revenue Billion Forecast, by Deployment 2020 & 2034
Table 48: Middle East & Africa Deception Technology Service Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 49: Middle East & Africa Deception Technology Service Revenue Billion Forecast, by Vertical 2020 & 2034
Table 50: Middle East & Africa Deception Technology Service Revenue Billion Forecast, by Country 2020 & 2034
Table 51: GCC Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Rest of MEA Deception Technology Service Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1How large is the deception technology service market?
The overall deception technology market is estimated at USD 2.7 billion in 2026 and is projected to reach USD 7.9 billion by 2033. Services — professional and managed deception offerings — are the fastest-growing component within that total.
2What is the growth rate of the deception technology service market?
The market is expanding at a CAGR of 16.9% from 2026 to 2033, with managed deception services growing near 16% annually and cloud-hosted deception-as-a-service outpacing on-premise deployments.
3Which region leads deception technology service adoption?
North America leads with roughly 34–38% of revenue, anchored by US federal defence and BFSI adoption. Asia-Pacific is the fastest-growing region, forecast to compound near 20% and become the largest regional market by value around 2030.
4Which industries drive the most demand for deception services?
BFSI leads with approximately 22% of vertical revenue, followed by healthcare, government, telecom/IT, manufacturing and retail. Small and medium enterprises form the largest adopting cohort at roughly 67.5%.
5Why do organisations buy managed deception services?
Decoys require continuous tuning to mirror live environments, a burden lean security teams struggle to carry. Managed providers deliver high-confidence, low-false-positive detection, AI-driven decoy adaptation and compliance evidence, reducing breach dwell time.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of all inputs derived from primary research: structured interviews, expert calls and validation surveys with deception-technology buyers, managed security service providers and platform vendors.
Interviewed roles include Chief Information Security Officer, SOC Director, VP of Security Engineering and Procurement and Vendor Management Lead across BFSI, healthcare, government and telecom/IT.
Company types surveyed: deception platform vendors, managed security service providers (MSSPs), security systems integrators, cloud security consultancies and in-house enterprise security operations teams.
Findings cross-referenced with recognised industry bodies including NIST, MITRE and ISACA frameworks, plus official sources such as the OECD (https://www.oecd.org) and European Commission OLAF (https://ec.europa.eu/olaf-report) for anti-illicit-trade and enforcement context.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
CISO / VP Security
32%
SOC Director / Security Operations Manager
28%
Security Engineering Lead
22%
Procurement / Vendor Management
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Enterprise security operations teams (end users)
34%
Managed security service providers (MSSPs)
26%
Deception platform vendors
18%
Security systems integrators
12%
Cloud security consultancies
10%
Secondary Research & Industry Benchmarking
20–30% of effort allocated to secondary validation using Bloomberg, Factiva, Hoovers and PitchBook, alongside official .gov, .org and non-profit trade association publications.
Benchmarked against multilateral trade and cyber-policy data from the OECD, World Bank, UN Comtrade and Eurostat; no commercial report portals or competitor research firms are used.
All reports refreshed to the date of purchase to reflect latest vendor disclosures, filings and regulatory updates.
Demand Modeling & Market Estimation
Simultaneous top-down and bottom-up methodologies validated via multi-level data triangulation.
Bottom-up model built on quantitative metrics: number of deception service contracts by vertical, average annual contract value (ACV), seats/endpoints under deception coverage, and attach rates of managed services to platform deployments.
Demand models segmented by component, deception stack, deployment mode, organisation size and region to reconcile aggregate market values.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%.
Multi-level triangulation across primary interviews, official statistics and financial databases to eliminate outlier bias.
Peer-review and sanity checks on segment sums against regional totals; continuous revision of forward estimates as new primary evidence emerges.