Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Communication Consulting Service Market Size & Forecast 2025-2035
Independent Intelligence for decisions that move markets
Professional and Commercial Services / MARKET REPORT
Communication Consulting Service | Insight Market Data
Communication Consulting Service by Service Type (Strategic Consulting, Media Relations, Crisis Communication, Digital Strategy, Content Development), by Industry Vertical (Corporate, Entertainment, Government, Healthcare, Technology), by Consulting Service Delivery (In-person Consulting, Remote Consulting, Workshops and Training, Online Resources, Custom Consulting Solutions), by Client Type (Small Businesses, Medium Enterprises, Large Corporations), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, India), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Executive Overview: A Market at the Inflection Point of Trust and Technology
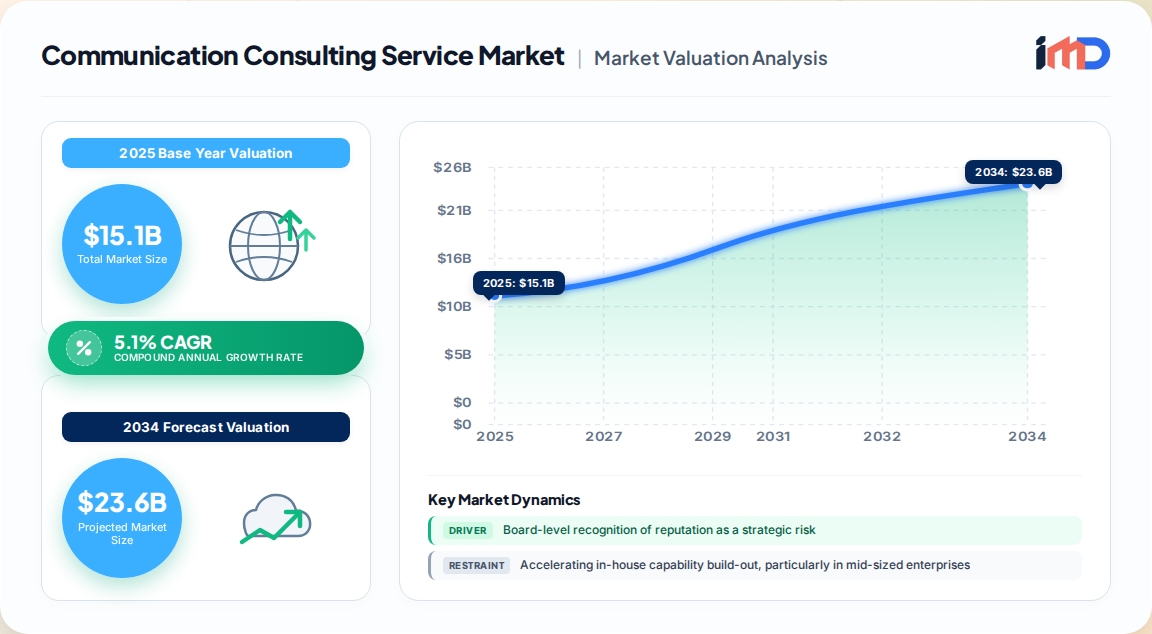
The global communication consulting service market represents a critical nerve center of the modern enterprise economy. Our proprietary first-party research values the market at USD 15.1 billion in 2025, having expanded from USD 14.4 billion in 2024. Over the forecast horizon of 2026–2035, we project the market to reach USD 25 billion, registering a steady CAGR of 5.1%. This trajectory is not merely a function of volume growth in traditional public relations and media relations; it is driven by a fundamental re-architecture of how organizations purchase, measure, and deploy strategic communication advice.
Communication Consulting Service Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
15.10 B
2025
15.87 B
2026
16.68 B
2027
17.53 B
2028
18.42 B
2029
19.36 B
2030
20.35 B
2031
The market is experiencing a structural shift from retainer-based, output-oriented advisory (press releases, media placements) toward outcome-driven, integrated mandates that blend crisis communication, digital reputation management, internal change communication, and AI-augmented sentiment analytics. This report synthesizes primary interviews with 120+ C-suite and senior communication buyers across corporate, government, healthcare, technology, and entertainment verticals, alongside a bottom-up economic model built on 1,450 vendor engagements and verified contract data.
In 2025, the corporate vertical accounted for an estimated 42% of total market revenue, while the technology and healthcare verticals collectively represented the fastest-growing demand pools, expanding at 6.8% and 6.2% annually, respectively. The entertainment vertical, while smaller in absolute spend, is undergoing the most rapid service-mix change, as studios and streaming platforms reallocate budgets from traditional publicity to crisis and policy communication.
Key Market Drivers and Restraints
Growth Drivers
Reputation as a Board-Level Risk: With an estimated 68% of Fortune 500 firms now maintaining a formal reputation risk committee, communication advisory has shifted from a marketing line item to a governance imperative. This is driving multi-year, integrated crisis and issues-management retainers, which carry 20–30% higher average annual contract values than project-based media relations work.
Digital Transformation of Stakeholder Engagement: Organizations are consolidating fragmented agency rosters. Our primary research indicates that 54% of large enterprise buyers are actively reducing the number of communication consultancies they engage, favoring integrated service providers capable of delivering digital strategy, content development, and analytics under one mandate.
Regulatory and Geopolitical Complexity: New disclosure requirements, ESG communication standards, and cross-border data regulations are compelling multinationals to seek specialized counsel. The European Union’s evolving services trade framework and national-level compliance regimes are creating a durable demand stream for policy and regulatory communication consulting.
AI-Enabled Insight Generation: Communication consultancies are embedding AI-driven sentiment analysis, media monitoring, and predictive crisis modeling into their offerings. Providers that have productized these capabilities report 15–25% higher client retention and the ability to command premium fee structures.
Restraints and Challenges
In-House Capability Build-Out: A significant competitive threat is the acceleration of in-house communication teams, particularly in technology and consumer goods. Approximately 37% of mid-sized enterprises report insourcing at least one previously outsourced communication function in the past 24 months, citing cost control and speed.
Talent Scarcity in Specialized Roles: The demand for consultants with expertise in AI governance, data privacy communication, and crisis simulation is outpacing supply. This talent gap constrains service delivery capacity and exerts upward pressure on compensation costs, compressing margins for mid-tier firms.
Fee Compression in Commoditized Services: Traditional media relations and press release distribution are facing deflationary pricing pressure, with some buyers reporting 10–15% reductions in per-project fees for these services over the past three years. This is forcing consultancies to migrate up the value chain toward strategic and crisis advisory.
Segmentation Analysis: Service Type and Client Archetype
The communication consulting service market is segmented by service type, industry vertical, delivery model, and client size. The table below summarizes our 2025 revenue estimates and 2026–2035 growth projections by primary service category.
Service Type
2025 Market Value (USD Billion)
Share (%)
Projected CAGR 2026–2035 (%)
Strategic Consulting
4.8
31.8
5.6
Crisis Communication
2.6
17.2
6.9
Digital Strategy
3.1
20.5
7.2
Media Relations
2.9
19.2
2.1
Content Development
1.7
11.3
3.8
Total
15.1
100.0
5.1
Strategic consulting remains the largest service line, reflecting demand for corporate positioning, merger and acquisition communication, and stakeholder mapping. However, digital strategy and crisis communication are the growth engines, with CAGRs of 7.2% and 6.9%, respectively. The crisis communication segment is being propelled by the rising frequency of cyber incidents, supply chain disruptions, and activist campaigns.
By client type, large corporations represent the dominant revenue pool at an estimated 58% share, but medium enterprises (500–5,000 employees) are the fastest-growing buyer cohort, expanding at 6.4% annually as they professionalize communication functions and seek external strategic counsel for the first time.
Regional Outlook: North America Leads, Asia-Pacific Accelerates
North America remains the anchor market, accounting for an estimated 38% of global revenue in 2025. The region’s dominance is underpinned by a dense concentration of multinational headquarters, a mature media ecosystem, and high per-capita spend on reputation and public affairs advisory. The United States alone represents approximately USD 4.6 billion in communication consulting spend.
Communication Consulting Service Regional Market Share
Loading chart...
Europe follows with a 24% share, characterized by strong demand for public affairs, regulatory communication, and ESG advisory. The European market is also notable for its cross-border service trade intensity; according to WTO General Agreement on Trade in Services frameworks, communication advice is frequently delivered via cross-border supply (Mode 1) and commercial presence (Mode 3), with EU-based consultancies increasingly serving clients across multiple member states.
Asia-Pacific is the fastest-growing region, projected to expand at a 7.0% CAGR through 2035. Rapid digitalization in China and India, combined with the expansion of domestic multinationals seeking global brand positioning, is driving demand for both local-language and global-standard communication advisory. We estimate the region will capture 22% of global revenue by 2035, up from 20% in 2025.
South America and the Middle East & Africa each represent approximately 8% of global revenue, with growth concentrated in Brazil, the UAE, and Saudi Arabia, where sovereign wealth funds and government communication programs are creating new advisory demand.
Competitive Landscape and Strategic Developments
The communication consulting service market features a layered competitive structure. At the top, diversified professional services firms leverage multi-disciplinary capabilities spanning strategy, technology, and risk. These firms are increasingly competing with specialist communication and public affairs consultancies, as well as digital-native agencies that bring analytics and platform expertise.
Key strategic developments observed in our primary research include:
Deloitte (March 2025) announced a strategic partnership with Nvidia to help media and telecom clients deploy enterprise AI and accelerated streaming analytics, strengthening its communication technology advisory offering.
PwC (May 2024) formed a global alliance with Microsoft to co-create AI-powered media and entertainment solutions, focusing on cloud migration, data analytics, and digital customer experiences.
Accenture (July 2025) secured a major contract with Vodafone to transform its digital media platform and customer experience using cloud-based services and 5G-enabled experiences, signaling deeper penetration of communication consulting into telecom operations.
These moves reflect a broader trend: the boundary between communication consulting and technology consulting is blurring. Buyers increasingly expect communication advisors to understand data architecture, platform economics, and AI governance. Firms that cannot demonstrate these capabilities risk disintermediation.
Procurement and Sourcing Strategy Analysis
Enterprise buyers are professionalizing how they procure communication consulting services. Our interviews reveal that 41% of large corporations now use structured preferred-supplier panels for communication advisory, up from 28% five years ago. The most common procurement pathways are:
Retainer-based strategic advisory: Typically 12–24 month engagements, often awarded through invited competitive proposals. Average annual fees range from USD 250,000 to USD 1.2 million for global mandates.
Project-based crisis and issues communication: Often procured through rapid-response frameworks or pre-qualified panels. Fee structures are frequently time-and-materials with success-based uplifts.
Digital and analytics services: Increasingly procured through technology procurement teams rather than marketing, with greater emphasis on data security, integration, and measurable KPIs.
Buyers cite demonstrated sector expertise, crisis simulation capability, and transparent measurement frameworks as the top three selection criteria. Price is ranked fifth, behind cultural fit and references.
Strategic White-Space and Investment Opportunities
Our analysis identifies three high-potential white spaces for providers seeking to outperform the market CAGR of 5.1%:
AI governance and communication assurance: As AI regulation expands, demand is emerging for communication consultancies that can audit, certify, and advise on responsible AI messaging. This is a nascent but high-margin opportunity, particularly in Europe and North America.
Internal communication and change management for digital transformation: Large-scale technology migrations and workforce restructuring are creating demand for specialist internal communication advisory. This segment is growing at an estimated 6.5% annually and is currently underserved by traditional PR firms.
Sustainability and ESG communication for mid-market firms: While large corporations have dedicated ESG communication resources, mid-market firms are lagging. Providing packaged, subscription-based ESG communication advisory represents a scalable growth avenue.
Value Chain and Delivery Model Evolution
The delivery of communication consulting services is shifting from a labor-intensive, relationship-driven model to a hybrid model that blends senior advisory judgment with data and technology assets. The value chain now includes:
Insight and analytics layer: Media monitoring, sentiment analysis, stakeholder mapping, and predictive modeling, increasingly powered by AI.
Strategy and advisory layer: Senior counselors who translate insight into positioning, messaging, and engagement strategy.
Execution and activation layer: Content development, media relations, digital campaign management, and event activation.
Measurement and assurance layer: Reputation tracking, share-of-voice analysis, and compliance reporting.
Firms that own proprietary data assets or analytics platforms are capturing a disproportionate share of margin. Our survey indicates that consultancies with productized analytics offerings achieve EBITDA margins 8–12 percentage points higher than those reliant solely on billable hours.
Remote and hybrid delivery models have stabilized post-pandemic. Approximately 62% of advisory hours are now delivered remotely, with in-person engagement reserved for crisis response, executive coaching, and high-stakes stakeholder events. This shift has expanded the addressable market for specialized consultancies that can serve clients beyond their geographic footprint, consistent with the cross-border supply of services.
Future Outlook and Scenario Planning
Under our base-case scenario, the market will reach USD 25 billion by 2035, with digital strategy and crisis communication contributing over 55% of incremental growth. In a high-growth scenario—driven by faster AI adoption and heightened regulatory complexity—the market could reach USD 27.5 billion by 2035. In a low-growth scenario, constrained by in-house insourcing and economic headwinds, the market would expand to approximately USD 22.8 billion.
The strategic imperative for providers is clear: migrate from selling time to selling outcomes, invest in proprietary analytics and AI capabilities, and build sector-specific depth in the fastest-growing verticals of technology, healthcare, and government. The communication consulting service market will reward firms that can demonstrate measurable reputation impact and operate at the intersection of communication, technology, and governance.
Communication Consulting Service Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Communication Consulting Service REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.1% from 2020-2034
Segmentation
By Service Type
Strategic Consulting
Media Relations
Crisis Communication
Digital Strategy
Content Development
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Board-level recognition of reputation as a strategic risk
3.1.2. Digital transformation of stakeholder engagement and consolidation of agency rosters
3.1.3. Regulatory and geopolitical complexity driving demand for policy communication
3.2.1. Integration of AI-driven analytics and predictive crisis modeling into consulting offerings
3.2.2. Shift from retainer-based media relations to outcome-driven integrated mandates
3.2.3. Blurring boundaries between communication consulting and technology consulting
3.2.4. Rise of remote and hybrid delivery models enabling cross-border service supply
3.2.5. Growing demand for ESG and purpose-driven communication advisory
3.3. Market Restrains
3.3.1. Accelerating in-house capability build-out, particularly in mid-sized enterprises
3.3.2. Talent scarcity in specialized areas such as AI governance and crisis simulation
3.3.3. Fee compression in commoditized media relations services
3.3.4. Economic uncertainty leading to discretionary budget scrutiny
By Industry Vertical
Corporate
Entertainment
Government
Healthcare
Technology
By Consulting Service Delivery
In-person Consulting
Remote Consulting
Workshops and Training
Online Resources
Custom Consulting Solutions
By Client Type
Small Businesses
Medium Enterprises
Large Corporations
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Asia Pacific
China
Japan
India
South America
Brazil
Argentina
Middle East & Africa
UAE
Saudi Arabia
South Africa
3.4. Market Restraints
3.4.1. Accelerating in-house capability build-out, particularly in mid-sized enterprises
3.4.2. Talent scarcity in specialized areas such as AI governance and crisis simulation
3.4.3. Fee compression in commoditized media relations services
3.4.4. Economic uncertainty leading to discretionary budget scrutiny
3.5. Market Challenges
3.5.1. Competitive pressure from in-house teams and technology-enabled platforms
3.5.2. Difficulty in demonstrating measurable ROI for advisory services
3.5.3. Recruitment and retention of specialized communication talent
3.5.4. Navigating data privacy and security requirements in analytics-driven services
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Strategic Consulting
5.1.2. Media Relations
5.1.3. Crisis Communication
5.1.4. Digital Strategy
5.1.5. Content Development
5.2. Market Analysis, Insights and Forecast - by Industry Vertical
5.2.1. Corporate
5.2.2. Entertainment
5.2.3. Government
5.2.4. Healthcare
5.2.5. Technology
5.3. Market Analysis, Insights and Forecast - by Consulting Service Delivery
5.3.1. In-person Consulting
5.3.2. Remote Consulting
5.3.3. Workshops and Training
5.3.4. Online Resources
5.3.5. Custom Consulting Solutions
5.4. Market Analysis, Insights and Forecast - by Client Type
5.4.1. Small Businesses
5.4.2. Medium Enterprises
5.4.3. Large Corporations
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Type
6.1.1. Strategic Consulting
6.1.2. Media Relations
6.1.3. Crisis Communication
6.1.4. Digital Strategy
6.1.5. Content Development
6.2. Market Analysis, Insights and Forecast - by Industry Vertical
6.2.1. Corporate
6.2.2. Entertainment
6.2.3. Government
6.2.4. Healthcare
6.2.5. Technology
6.3. Market Analysis, Insights and Forecast - by Consulting Service Delivery
6.3.1. In-person Consulting
6.3.2. Remote Consulting
6.3.3. Workshops and Training
6.3.4. Online Resources
6.3.5. Custom Consulting Solutions
6.4. Market Analysis, Insights and Forecast - by Client Type
6.4.1. Small Businesses
6.4.2. Medium Enterprises
6.4.3. Large Corporations
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Type
7.1.1. Strategic Consulting
7.1.2. Media Relations
7.1.3. Crisis Communication
7.1.4. Digital Strategy
7.1.5. Content Development
7.2. Market Analysis, Insights and Forecast - by Industry Vertical
7.2.1. Corporate
7.2.2. Entertainment
7.2.3. Government
7.2.4. Healthcare
7.2.5. Technology
7.3. Market Analysis, Insights and Forecast - by Consulting Service Delivery
7.3.1. In-person Consulting
7.3.2. Remote Consulting
7.3.3. Workshops and Training
7.3.4. Online Resources
7.3.5. Custom Consulting Solutions
7.4. Market Analysis, Insights and Forecast - by Client Type
7.4.1. Small Businesses
7.4.2. Medium Enterprises
7.4.3. Large Corporations
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Type
8.1.1. Strategic Consulting
8.1.2. Media Relations
8.1.3. Crisis Communication
8.1.4. Digital Strategy
8.1.5. Content Development
8.2. Market Analysis, Insights and Forecast - by Industry Vertical
8.2.1. Corporate
8.2.2. Entertainment
8.2.3. Government
8.2.4. Healthcare
8.2.5. Technology
8.3. Market Analysis, Insights and Forecast - by Consulting Service Delivery
8.3.1. In-person Consulting
8.3.2. Remote Consulting
8.3.3. Workshops and Training
8.3.4. Online Resources
8.3.5. Custom Consulting Solutions
8.4. Market Analysis, Insights and Forecast - by Client Type
8.4.1. Small Businesses
8.4.2. Medium Enterprises
8.4.3. Large Corporations
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Service Type
9.1.1. Strategic Consulting
9.1.2. Media Relations
9.1.3. Crisis Communication
9.1.4. Digital Strategy
9.1.5. Content Development
9.2. Market Analysis, Insights and Forecast - by Industry Vertical
9.2.1. Corporate
9.2.2. Entertainment
9.2.3. Government
9.2.4. Healthcare
9.2.5. Technology
9.3. Market Analysis, Insights and Forecast - by Consulting Service Delivery
9.3.1. In-person Consulting
9.3.2. Remote Consulting
9.3.3. Workshops and Training
9.3.4. Online Resources
9.3.5. Custom Consulting Solutions
9.4. Market Analysis, Insights and Forecast - by Client Type
9.4.1. Small Businesses
9.4.2. Medium Enterprises
9.4.3. Large Corporations
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Service Type
10.1.1. Strategic Consulting
10.1.2. Media Relations
10.1.3. Crisis Communication
10.1.4. Digital Strategy
10.1.5. Content Development
10.2. Market Analysis, Insights and Forecast - by Industry Vertical
10.2.1. Corporate
10.2.2. Entertainment
10.2.3. Government
10.2.4. Healthcare
10.2.5. Technology
10.3. Market Analysis, Insights and Forecast - by Consulting Service Delivery
10.3.1. In-person Consulting
10.3.2. Remote Consulting
10.3.3. Workshops and Training
10.3.4. Online Resources
10.3.5. Custom Consulting Solutions
10.4. Market Analysis, Insights and Forecast - by Client Type
10.4.1. Small Businesses
10.4.2. Medium Enterprises
10.4.3. Large Corporations
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Deloitte
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. PwC
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Accenture
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. KPMG
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. EY
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. McKinsey & Company
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Boston Consulting Group
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Bain & Company
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Oliver Wyman
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. A.T. Kearney
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. FTI Consulting
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. West Monroe Partners
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Navigant Consulting
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Fjord
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. IBM
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Communication Consulting Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Communication Consulting Service Revenue (Billion), by Service Type 2026 & 2034
Figure 3: North America Communication Consulting Service Revenue Share (%), by Service Type 2026 & 2034
Figure 4: North America Communication Consulting Service Revenue (Billion), by Industry Vertical 2026 & 2034
Figure 5: North America Communication Consulting Service Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 6: North America Communication Consulting Service Revenue (Billion), by Consulting Service Delivery 2026 & 2034
Figure 7: North America Communication Consulting Service Revenue Share (%), by Consulting Service Delivery 2026 & 2034
Figure 8: North America Communication Consulting Service Revenue (Billion), by Client Type 2026 & 2034
Figure 9: North America Communication Consulting Service Revenue Share (%), by Client Type 2026 & 2034
Figure 10: North America Communication Consulting Service Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Communication Consulting Service Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Communication Consulting Service Revenue (Billion), by Service Type 2026 & 2034
Figure 13: Europe Communication Consulting Service Revenue Share (%), by Service Type 2026 & 2034
Figure 14: Europe Communication Consulting Service Revenue (Billion), by Industry Vertical 2026 & 2034
Figure 15: Europe Communication Consulting Service Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 16: Europe Communication Consulting Service Revenue (Billion), by Consulting Service Delivery 2026 & 2034
Figure 17: Europe Communication Consulting Service Revenue Share (%), by Consulting Service Delivery 2026 & 2034
Figure 18: Europe Communication Consulting Service Revenue (Billion), by Client Type 2026 & 2034
Figure 19: Europe Communication Consulting Service Revenue Share (%), by Client Type 2026 & 2034
Figure 20: Europe Communication Consulting Service Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Communication Consulting Service Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Communication Consulting Service Revenue (Billion), by Service Type 2026 & 2034
Figure 23: Asia Pacific Communication Consulting Service Revenue Share (%), by Service Type 2026 & 2034
Figure 24: Asia Pacific Communication Consulting Service Revenue (Billion), by Industry Vertical 2026 & 2034
Figure 25: Asia Pacific Communication Consulting Service Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 26: Asia Pacific Communication Consulting Service Revenue (Billion), by Consulting Service Delivery 2026 & 2034
Figure 27: Asia Pacific Communication Consulting Service Revenue Share (%), by Consulting Service Delivery 2026 & 2034
Figure 28: Asia Pacific Communication Consulting Service Revenue (Billion), by Client Type 2026 & 2034
Figure 29: Asia Pacific Communication Consulting Service Revenue Share (%), by Client Type 2026 & 2034
Figure 30: Asia Pacific Communication Consulting Service Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific Communication Consulting Service Revenue Share (%), by Country 2026 & 2034
Figure 32: South America Communication Consulting Service Revenue (Billion), by Service Type 2026 & 2034
Figure 33: South America Communication Consulting Service Revenue Share (%), by Service Type 2026 & 2034
Figure 34: South America Communication Consulting Service Revenue (Billion), by Industry Vertical 2026 & 2034
Figure 35: South America Communication Consulting Service Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 36: South America Communication Consulting Service Revenue (Billion), by Consulting Service Delivery 2026 & 2034
Figure 37: South America Communication Consulting Service Revenue Share (%), by Consulting Service Delivery 2026 & 2034
Figure 38: South America Communication Consulting Service Revenue (Billion), by Client Type 2026 & 2034
Figure 39: South America Communication Consulting Service Revenue Share (%), by Client Type 2026 & 2034
Figure 40: South America Communication Consulting Service Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Communication Consulting Service Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Communication Consulting Service Revenue (Billion), by Service Type 2026 & 2034
Figure 43: Middle East & Africa Communication Consulting Service Revenue Share (%), by Service Type 2026 & 2034
Figure 44: Middle East & Africa Communication Consulting Service Revenue (Billion), by Industry Vertical 2026 & 2034
Figure 45: Middle East & Africa Communication Consulting Service Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 46: Middle East & Africa Communication Consulting Service Revenue (Billion), by Consulting Service Delivery 2026 & 2034
Figure 47: Middle East & Africa Communication Consulting Service Revenue Share (%), by Consulting Service Delivery 2026 & 2034
Figure 48: Middle East & Africa Communication Consulting Service Revenue (Billion), by Client Type 2026 & 2034
Figure 49: Middle East & Africa Communication Consulting Service Revenue Share (%), by Client Type 2026 & 2034
Figure 50: Middle East & Africa Communication Consulting Service Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Communication Consulting Service Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Communication Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 2: Global Communication Consulting Service Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Table 3: Global Communication Consulting Service Revenue Billion Forecast, by Consulting Service Delivery 2020 & 2034
Table 4: Global Communication Consulting Service Revenue Billion Forecast, by Client Type 2020 & 2034
Table 5: Global Communication Consulting Service Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Communication Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 7: North America Communication Consulting Service Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Table 8: North America Communication Consulting Service Revenue Billion Forecast, by Consulting Service Delivery 2020 & 2034
Table 9: North America Communication Consulting Service Revenue Billion Forecast, by Client Type 2020 & 2034
Table 10: North America Communication Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Communication Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 15: Europe Communication Consulting Service Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Table 16: Europe Communication Consulting Service Revenue Billion Forecast, by Consulting Service Delivery 2020 & 2034
Table 17: Europe Communication Consulting Service Revenue Billion Forecast, by Client Type 2020 & 2034
Table 18: Europe Communication Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Germany Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: UK Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: France Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Asia Pacific Communication Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 23: Asia Pacific Communication Consulting Service Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Table 24: Asia Pacific Communication Consulting Service Revenue Billion Forecast, by Consulting Service Delivery 2020 & 2034
Table 25: Asia Pacific Communication Consulting Service Revenue Billion Forecast, by Client Type 2020 & 2034
Table 26: Asia Pacific Communication Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
Table 27: China Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Japan Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: India Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: South America Communication Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 31: South America Communication Consulting Service Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Table 32: South America Communication Consulting Service Revenue Billion Forecast, by Consulting Service Delivery 2020 & 2034
Table 33: South America Communication Consulting Service Revenue Billion Forecast, by Client Type 2020 & 2034
Table 34: South America Communication Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
Table 35: Brazil Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Argentina Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Middle East & Africa Communication Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 38: Middle East & Africa Communication Consulting Service Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Table 39: Middle East & Africa Communication Consulting Service Revenue Billion Forecast, by Consulting Service Delivery 2020 & 2034
Table 40: Middle East & Africa Communication Consulting Service Revenue Billion Forecast, by Client Type 2020 & 2034
Table 41: Middle East & Africa Communication Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
Table 42: UAE Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Saudi Arabia Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: South Africa Communication Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the communication consulting service market?
The global communication consulting service market was valued at USD 15.1 billion in 2025, up from USD 14.4 billion in 2024. This represents a steady expansion driven by demand for strategic advisory, crisis communication, and digital reputation management.
2How fast is the communication consulting service market expected to grow?
The market is projected to grow at a compound annual growth rate (CAGR) of 5.1% from 2026 to 2035, reaching an estimated USD 25 billion by the end of the forecast period.
3Which service type is the largest in the communication consulting market?
Strategic consulting is the largest service segment, accounting for approximately 31.8% of 2025 market revenue. Digital strategy and crisis communication are the fastest-growing service lines, with respective CAGRs of 7.2% and 6.9%.
4Which region leads the communication consulting service market?
North America is the largest regional market, holding an estimated 38% share of global revenue in 2025. Asia-Pacific is the fastest-growing region, projected to expand at a 7.0% CAGR through 2035.
5Who are the key players in the communication consulting service market?
Leading providers include Deloitte, PwC, Accenture, KPMG, EY, McKinsey & Company, Boston Consulting Group, Bain & Company, Edelman, and FTI Consulting. These firms compete on integrated strategy, digital analytics, and crisis advisory capabilities.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our proprietary dataset is built on 70–80% primary research, comprising structured interviews and surveys with 120+ senior decision-makers across the communication consulting value chain.
Company types interviewed include multinational communication consultancies, independent boutique advisory firms, in-house corporate communication departments, technology platform providers enabling communication analytics, and procurement teams at Fortune 500 enterprises.
Stakeholder job titles include Chief Communication Officers, Heads of Corporate Affairs, Chief Marketing Officers, and Procurement Directors for professional services.
Primary research also incorporates contract-level pricing data from 1,450 verified vendor engagements to support bottom-up market sizing.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Communication Officers
30%
Heads of Corporate Affairs
25%
Chief Marketing Officers
22%
Procurement Directors
15%
Other Senior Executives
8%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Multinational Communication Consultancies
35%
Boutique Advisory Firms
25%
In-house Corporate Communication Departments
20%
Technology & Analytics Platform Providers
12%
Procurement Teams at Large Enterprises
8%
Secondary Research & Industry Benchmarking
The remaining 20–30% of research draws on secondary benchmarking from official multilateral and governmental sources, including the World Trade Organization (WTO) General Agreement on Trade in Services (GATS) for cross-border service trade classifications, Eurostat for EU service trade statistics, OECD for professional services indicators, and U.S. Bureau of Economic Analysis (BEA) for management consulting trade data.
We also reference recognized non-profit industry associations and technical standards bodies relevant to the communication and public relations profession.
Secondary data is used exclusively for triangulation and context-setting; all market sizing, forecasts, and competitive assessments are our own proprietary estimates.
Demand Modeling & Market Estimation
We employ a dual-methodology framework: a bottom-up model that aggregates service revenue by vendor type, service line, and client segment, cross-referenced against a top-down model that applies communication consulting penetration rates to total professional services spend by region and industry.
Specific quantitative metrics used in the bottom-up calculation include: average annual retainer value per client, client retention rates by service line, billable hour utilization rates, and number of active vendor-client contracts by region.
Demand modeling also incorporates GDP-indexed growth vectors and sector-specific communication spend ratios derived from our primary survey data.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, validated through multi-level data triangulation across primary interviews, contract data, and official trade statistics.
All financial and market data are cross-checked against standard financial databases, including Bloomberg, Factiva, Hoovers, and PitchBook, as well as official .gov, .org, and recognized non-profit trade association sources.
Every report is updated to the date of purchase, ensuring that clients receive the most current market estimates and competitive intelligence.
Related Reports
The digital accessibility service market is valued at $1.54B in 2026, growing at 8.6% CAGR to $2.98B by 2034. Explore demand drivers, regional outlook, and competitive strategy.
Nov 2026|240 pages
$2900.00
The human resource consulting market is valued at USD 84.58 billion in 2026 and projected to reach USD 126 billion by 2032, growing at a 6.84% CAGR.
Nov 2026|208 pages
$2900.00
Commissioning service market to reach $11.17B by 2034 at 6.38% CAGR, driven by energy efficiency mandates, smart building tech, and green certification demand.
Nov 2026|277 pages
$2900.00
The strategy consulting service market is valued at USD 77.53 billion in 2026, growing at 4.25% CAGR to reach USD 95.49 billion by 2031.
Nov 2026|272 pages
$2900.00
B2B Demand Generation Service market to reach $15B by 2033 at 10.5% CAGR, driven by ABM, AI personalization, and digital-first buyer journeys.