1What is the current size of the automotive Ethernet PHY chip market?
The market was estimated at USD 1.1 billion in 2025 and is projected to reach USD 4.6 billion by 2035, growing at a CAGR of 14.8%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Automotive Ethernet PHYs Chip Industry
 by Data Rate (10 Mbps, 100 Mbps, 1 Gbps, 2.5 Gbps and above), by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), by Application (Advanced Driver Assistance Systems (ADAS), Infotainment Systems, Powertrain and Chassis Systems, Body Electronics, Telematics and Connectivity), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Rest of Europe), by Asia Pacific (China, Japan, South Korea, India, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (UAE, Saudi Arabia, Rest of MEA) Forecast 2026-2034
Research Analyst

 Related Reports

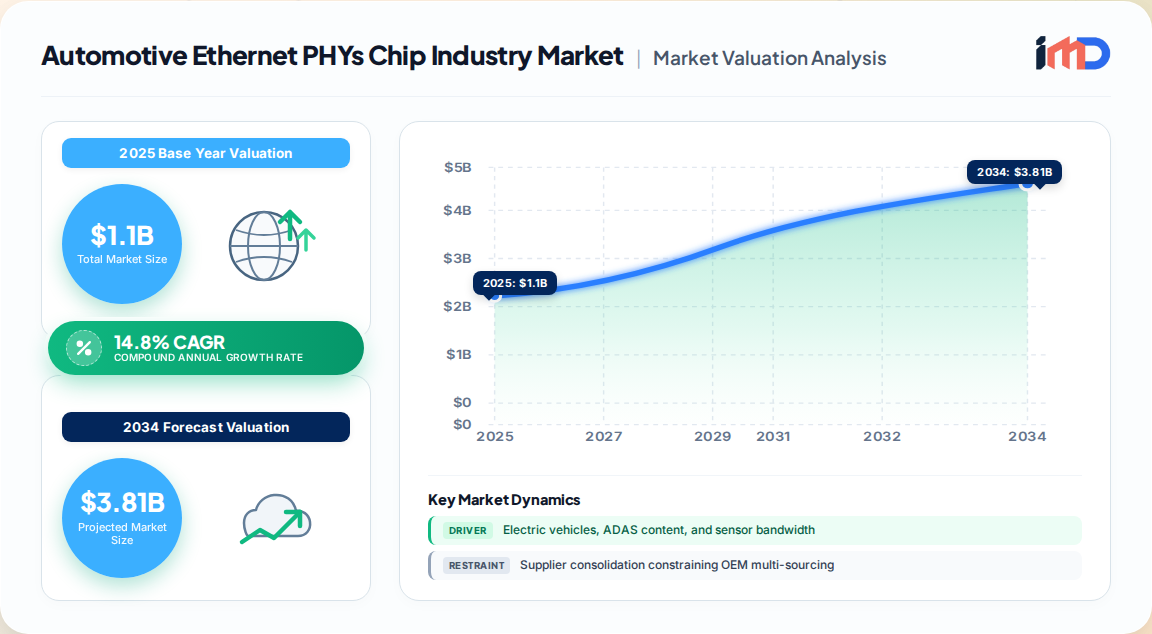
The global automotive Ethernet PHYs chip industry market was valued at USD 1.1 billion in 2025 and is projected to expand to USD 4.6 billion by 2035, registering a robust CAGR of 14.8% from 2026 to 2035. This growth is not merely a volume story; it represents a fundamental re-architecture of the vehicle's nervous system. Unit shipments are forecast to rise from 362 million units in 2025 to 903 million units by 2035, while the blended average selling price (ASP) increases from USD 2.99 to USD 4.55 over the same period. This dual expansion—volume and value—signals a market transitioning from simple connectivity substitution to an architecture-critical semiconductor category.
The product scope encompasses automotive-grade Ethernet physical-layer transceivers operating from 10 Mbps to multi-gigabit rates, including 10BASE-T1S, 100BASE-T1, 1000BASE-T1, and 2.5/5/10GBASE-T1 variants. These chips are the foundational hardware enabling deterministic, high-bandwidth in-vehicle communication for ADAS, infotainment, powertrain, body electronics, and zonal gateways. Asia Pacific dominates the market with approximately 54.9% share in 2025, driven by China's massive vehicle production base and rapid EV adoption, while North America is the fastest-growing region due to advanced ADAS and software-defined vehicle (SDV) investments.
The demand for automotive Ethernet PHYs is being reshaped by three interconnected forces: the electrification of powertrains, the sensor fusion requirements of advanced driver-assistance systems (ADAS), and the industry-wide shift toward software-defined, zonal vehicle architectures.
Despite the strong growth trajectory, the market faces notable restraints. Supplier consolidation is a double-edged sword: the acquisition of Marvell's Automotive Ethernet business by Infineon for USD 2.5 billion in August 2025 has concentrated critical PHY and switch portfolio ownership among fewer integrated suppliers. This raises procurement risk for OEMs and Tier-1s with long qualification cycles, potentially slowing adoption in cost-sensitive mass-market segments. Additionally, the large active ICE production base, which generated USD 0.84 billion in automotive Ethernet hardware revenue in 2025, limits per-vehicle Ethernet content and moderates overall hardware value per unit in regions where BEV penetration remains below 25%.
The market is segmented by data rate, vehicle type, and application. The data rate segmentation is witnessing a clear migration toward higher speeds, while application segmentation is dominated by ADAS and infotainment.
| Segment | Key Characteristics | Market Share Outlook (2025-2035) |
|---|---|---|
| 10BASE-T1S | Multidrop architecture for distributed sensors and body control; lowest cost per port. | Growing share in edge nodes; volumes increasing but lower ASP. |
| 100BASE-T1 | Workhorse for body, infotainment, and secondary gateways; single balanced pair. | Largest current volume; share eroding as 1 Gbps adoption rises. |
| 1000BASE-T1 | Backbone for ADAS sensor fusion, cameras, and zonal controllers. | Fastest-growing segment; projected to hold over 35% share by 2035. |
| Multi-Gigabit (2.5/5/10GBASE-T1) | Emerging for LiDAR, high-res cameras, and central compute aggregation. | High-value niche; critical for premium and autonomous platforms. |
By vehicle type, passenger cars dominate volume, but light and heavy commercial vehicles are emerging opportunities for cost-effective, automotive-qualified PHYs. By application, ADAS and infotainment systems are the largest demand pools, with powertrain and body electronics providing steady baseline demand.
Asia Pacific is the largest and most influential market, accounting for 54.9% of global revenue in 2025. China, Japan, and South Korea are the key manufacturing hubs, supported by domestic semiconductor suppliers like Renesas and Rohm. The region's dominance is underpinned by strong vehicle production, aggressive EV policies, and the rapid adoption of connected-car technologies.
North America is the fastest-growing region, driven by investments in ADAS, high-performance computing, and software-defined vehicles. The United States, Canada, and Mexico are important markets, with key players like Microchip Technology, Texas Instruments, and Broadcom driving innovation. Europe remains a significant market, with Germany, France, and the UK leading in premium vehicle production and zonal architecture adoption.
The automotive Ethernet PHY market is highly concentrated. NXP Semiconductors led with over 34% market share in 2025, and the top five players—Broadcom, Marvell/Infineon, NXP, Renesas, and Texas Instruments—collectively held 74% of the market. This concentration reflects the high barriers to entry, including stringent automotive qualification (AEC-Q100, ISO 26262), long design-in cycles, and the need for a broad portfolio spanning multiple speed tiers.
Recent industry developments underscore the strategic importance of this market. In February 2026, NXP introduced the TJA1410 10BASE-T1S PMD transceiver, extending Ethernet to edge nodes. Microchip launched its LAN878x and LAN888x Single Pair Ethernet PHY families in May 2026, featuring 100BASE-T1 and 1000BASE-T1 options with integrated MACsec security. Additionally, Microchip and Hyundai Motor Group announced a collaboration in February 2026 to explore 10BASE-T1S Single Pair Ethernet for future vehicles. These moves highlight the race to secure design wins in next-generation zonal architectures.
The value chain for automotive Ethernet PHYs spans from IP and EDA tool providers to semiconductor foundries, fabless designers, Tier-1 integrators, and OEMs. The fabless model dominates, with companies like Broadcom and Marvell designing chips fabricated at foundries such as TSMC. The supply chain is subject to geopolitical tensions and capacity constraints, particularly for advanced nodes. However, the shift to 28nm and 40nm processes for automotive PHYs has alleviated some pressure, as these mature nodes have ample capacity.
While PHYs are not typically traded as standalone commodities, import/export dynamics are embedded in the semiconductor supply chain. Key suppliers are concentrated in North America (Broadcom, Marvell, Texas Instruments, Microchip), Europe (NXP, Infineon), and Asia (Renesas, Rohm). China is a major importer of automotive semiconductors, but domestic players are emerging. The recent acquisition of Marvell's automotive Ethernet business by Infineon reshapes the supplier landscape, creating a European powerhouse that can offer integrated PHY-switch-controller solutions. This consolidation may lead to increased bargaining power for suppliers, potentially impacting pricing and availability for OEMs.
For investors and industry participants, the most promising opportunities lie in the multi-gigabit segment, where ASPs are significantly higher (USD 5+), and in the development of PHYs with integrated functional safety and security features. The commercial vehicle and off-highway equipment sectors present untapped potential for cost-effective PHYs. Furthermore, the integration of PHYs into SoCs and MCUs by dominant players like NXP and Infineon creates an opportunity for standalone PHY suppliers to differentiate through superior performance and interoperability.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.8% from 2020-2034 |
| Segmentation |
|
By Application
| By Geography |
|
The market was estimated at USD 1.1 billion in 2025 and is projected to reach USD 4.6 billion by 2035, growing at a CAGR of 14.8%.
Asia Pacific dominates with approximately 54.9% market share in 2025, driven by high vehicle production and EV adoption in China, Japan, and South Korea.
NXP Semiconductors leads with over 34% market share, followed by Broadcom, Marvell/Infineon, Renesas Electronics, and Texas Instruments, which collectively hold 74% of the market.
Key drivers include the rise of electric vehicles and ADAS content, the shift to software-defined vehicle architectures, vehicle production growth in emerging markets, and demand for deterministic, secure in-vehicle communication.
The market is expected to grow at a CAGR of 14.8% from 2026 to 2035.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product Line Manager | 30% |
| Vehicle Network Architect | 25% |
| Procurement Director | 25% |
| Functional Safety Engineer | 20% |
| Company Type | Representation (%) |
|---|---|
| Fabless PHY Semiconductor Designers | 35% |
| Tier-1 Automotive Integrators | 30% |
| Automotive OEMs E/E Architecture Teams | 20% |
| Semiconductor Foundries | 10% |
| Test and Certification Labs | 5% |