1What is the size of the automotive components market?
The global automotive components market is estimated at USD 116.7 billion in 2026 and is projected to reach USD 151.2 billion by 2032, growing at a 4.38% CAGR over the 2027–2032 forecast period.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Automotive Components Market
 by Propulsion (Internal Combustion Engine, Battery Electric, Hybrid), by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), by Sales Channel (OEM, Aftermarket), by Part Type (Powertrain, Chassis & Body, Interior, Electrical & Electronics, Lighting, Tires & Wheels, Filters & Fluids), by Asia-Pacific (China, Japan, India, South Korea), by Europe (Germany, UK, France, Netherlands), by North America (USA, Canada, Mexico), by South America (Brazil, Argentina), by Middle East & Africa (UAE, South Africa) Forecast 2026-2034
Research Analyst


 Related Reports

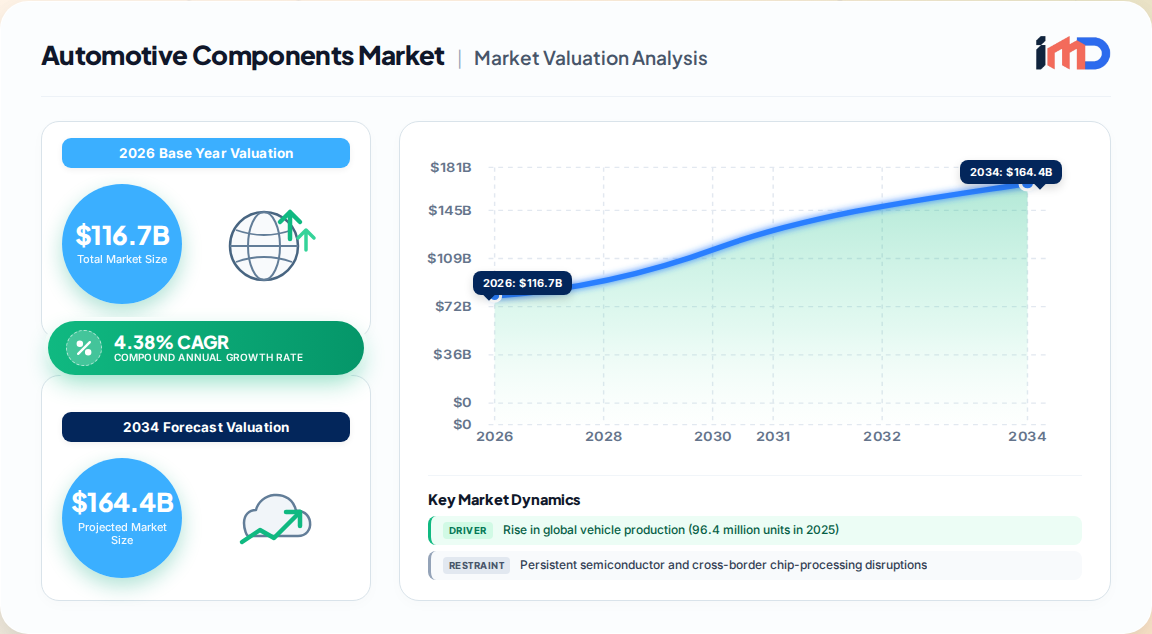
The global automotive components market is entering a phase of structural rebalancing. Our proprietary primary research estimates the market at USD 116.7 billion in 2026, expanding to USD 122.1 billion in 2027 and USD 151.2 billion by 2032, reflecting a 4.38% CAGR over the 2027–2032 forecast window. Volume-led assembly demand, software-defined vehicle (SDV) hardware content and a resilient aftermarket together underpin this trajectory.
This report synthesises in-depth interviews, plant-level sourcing audits and trade-flow triangulation to profile growth vectors, supply-chain risk and competitive positioning across the ecosystem.
Demand formation in the automotive components market is being reshaped by five high-conviction forces.
| Driver | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Rise in global vehicle production | +2.0% | Asia & Oceania | Short term (≤2 years) |
| Software-defined vehicles requiring upgradeable hardware | +1.6% | Germany (Rastatt cluster) | Medium term (2–4 years) |
| Aging vehicle fleet boosting aftermarket spend | +1.1% | United States | Long term (≥4 years) |
| Rapid growth of e-commerce parts platforms | +0.9% | Europe incl. UK | Medium term (2–4 years) |
| Right-to-repair legislation widening independent service share | +0.4% | Australia & EU | Medium term (2–4 years) |
| Lightweighting push for advanced material components | +0.3% | Germany, Netherlands, South Korea | Long term (≥4 years) |
Global motor vehicle production reached an estimated 96.4 million units in 2025, up 4% from 92.7 million in 2024, per OICA — directly expanding installation-part demand. Software-defined architectures, exemplified by OEMs deploying centralised supercomputers with over-the-air update capability across multi-million-unit fleets, are extending hardware-design relevance well beyond the production date.
On the restraint side, semiconductor and cross-border chip-processing disruptions remain the most acute headwind, with an estimated -0.8% CAGR impact concentrated in the EU and China. The 2025 Nexperia supply event — triggered by a Dutch ministerial order in September 2025 and subsequent Chinese export controls — demonstrated how a single failure at a border boundary can constrain finished-component supply despite upstream fabrication capability. Additional drags include ICE-specific component erosion (-0.6%), volatile raw-material pricing (-0.3%) and labour shortages in Mexican manufacturing hubs (-0.2%).
Our bottom-up segment model reveals a market in transition rather than disruption.
The component-type mix is similarly bifurcating. Chassis and body systems command the largest single part-category share at approximately 35.4%, consistent with structural-safety and lightweighting requirements; powertrain components follow at roughly 29.8%. Electrical and electronics components posted the fastest revenue growth among Tier-1 categories — approximately 30% between 2021 and 2024 — as ADAS, infotainment and zonal architectures scaled.
Asia-Pacific's 46% share reflects the concentration of vehicle assembly in China, Japan, India and South Korea, reinforced by a 5.92% CAGR outlook that outpaces all other regions. Europe follows with an estimated 24% share, supported by strict CO₂ and safety mandates and dense R&D clusters, while North America retains approximately 19% on the strength of aftermarket depth and localised investment.
| Region | 2026 Share (est.) | Growth Outlook |
|---|---|---|
| Asia-Pacific | 46% | Fastest, 5.92% CAGR |
| Europe | 24% | Moderate, EV policy-led |
| North America | 19% | Steady, aftermarket-led |
| South America | 6% | Emerging, localisation-driven |
| Middle East & Africa | 5% | Nascent, import-dependent |
Competitive concentration is medium. Major players including Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation and Hyundai Mobis anchor the landscape, but regional Tier-2 specialists and aftermarket distributors exert meaningful pricing influence. Recent strategic moves underscore a pivot toward electrification and localisation: Bosch formed a joint venture with a Korean battery startup in March 2024 to strengthen EV component capabilities, while Magna International announced a USD 450 million Alabama investment in July 2023 targeting chassis and electrified-system capacity.
Cross-border movement of automotive components is highly sensitive to regulatory and technical barriers. India's Quality Control Orders (QCOs) on wheel rims, safety glass and fasteners exemplify the compliance burden facing exporters: mandatory BIS Standard Marking, plant audits and India-specific conformity standards (IS 9436/IS 9438) add cost and lead-time friction for EU-origin components despite existing international certification.
These measures illustrate a broader pattern — technical regulations are becoming a determinant of supplier access in high-growth assembly markets. Suppliers with local certification capability and in-country audit readiness gain a structural first-mover advantage.
The value chain spans raw-material processing, Tier-2 component fabrication, Tier-1 integration, OEM assembly and aftermarket distribution. Two risk concentrations warrant board-level attention:
Mitigation strategies observed in our primary interviews include dual-sourcing of semiconductor content, regionalised inventory buffers and long-term hedging contracts for steel and aluminium.
Three opportunity clusters stand out for the 2027–2032 window:
For procurement teams, the strategic imperative is to shift from transactional sourcing to multi-year capacity reservations with electronics-capable suppliers, while building qualification pathways for aftermarket-grade components in growth regions.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.38% from 2020-2034 |
| Segmentation |
|
By Sales Channel
By Part Type
| By Geography |
|
The global automotive components market is estimated at USD 116.7 billion in 2026 and is projected to reach USD 151.2 billion by 2032, growing at a 4.38% CAGR over the 2027–2032 forecast period.
Asia-Pacific leads with a 46% revenue share in 2026 and is also the fastest-growing region at a 5.92% CAGR through 2032, driven by large-scale vehicle assembly in China, Japan and India.
Rising global vehicle production (+2.0% CAGR impact), software-defined vehicles requiring upgradeable hardware (+1.6%), aging vehicle fleets boosting aftermarket spend (+1.1%) and e-commerce parts platforms (+0.9%) are the principal growth drivers.
Battery-electric vehicle components are forecast to grow at a 31.8% CAGR over 2027–2032, even though internal combustion engine components retain a 72.87% share in 2026.
Leading suppliers include Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation and Hyundai Mobis Co. Ltd, alongside a fragmented Tier-2 and aftermarket specialist base.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Chief Engineer – Powertrain/Electronics | 25% |
| Supply Chain Manager | 25% |
| Aftermarket Category Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Tier-1 System Integrators | 35% |
| Tier-2 Component Fabricators | 25% |
| Semiconductor & Power Electronics Suppliers | 15% |
| Aftermarket Distributors & E-commerce Platforms | 15% |
| OEM Procurement Divisions | 10% |