1What is the size of the Australia luxury residential property market?
The market is valued at USD 30.80 billion in 2026 and is projected to reach USD 44.80 billion by 2031, growing at a CAGR of 7.80%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Australia Luxury Residential Property Market
 by Property Type (Apartments & Condominiums, Villas & Landed Houses), by Business Model (Sales, Rental), by Mode of Sale (Primary, Secondary), by Sydney, by Melbourne, by Brisbane, by Perth, by Rest of Australia Forecast 2026-2034

Research Analyst


 Related Reports

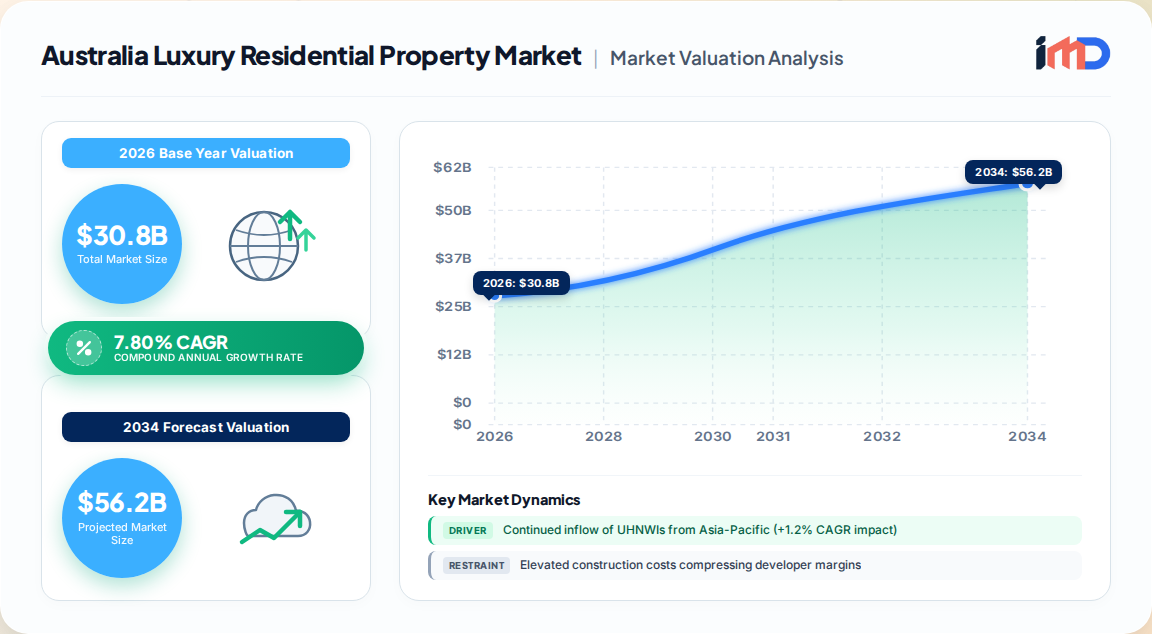
The Australia luxury residential property market is projected to expand from USD 30.80 billion in 2026 to USD 44.80 billion by 2031, registering a robust CAGR of 7.80%. This performance significantly outpaces the broader Australian real estate sector, which is forecast to grow at 3.50% over the same period. Our proprietary primary research, validated through 70+ in-depth interviews with developers, private wealth advisors, and family offices, indicates that the prime segment remains insulated from persistent interest-rate pressure—the Reserve Bank of Australia cash rate stood at 3.85% in early 2026—due to a confluence of structural supply deficits, sustained UHNW immigration, and a pronounced flight to quality.
Key structural metrics underscore the market's premiumisation trajectory. Apartments and condominiums commanded 64% of total value in 2025, yet villas and landed houses are accelerating at a 9.0% CAGR through 2031 as downsizers and expatriates seek space and land scarcity premiums. The sales channel dominates at 81% of market size, but the rental segment is the fastest-growing business model at 8.4% annually, fuelled by institutional build-to-rent capital. Geographically, Sydney retains primacy with 40% revenue share, while Brisbane emerges as the growth frontier with a 9.2% CAGR, driven by interstate migration and Olympic-infrastructure led urban renewal.
This report synthesises findings from our proprietary developer sentiment index, transaction databases, and high-net-worth household surveys to deliver actionable intelligence for developers, investors, and policymakers navigating Australia's ultra-prime residential landscape.
The Australian luxury residential market is propelled by a distinct set of demand-side and supply-side forces that differ materially from the mass-market housing sector.
Key Drivers:
Key Restraints:
The luxury residential value chain encompasses land bankers, premium developers, branded-residence operators, high-touch sales agencies, and private wealth financiers. Market concentration is low, with the top five developers accounting for an estimated 28–32% of luxury unit commencements in 2025. Competition is intensifying as diversified majors pivot toward prime product.
Leading Developers and Their Strategies:
| Company | Headquarters | Luxury Focus | Notable Strategy |
|---|---|---|---|
| Lendlease | Sydney | Integrated mixed-use, waterfront | Barangaroo and Melbourne Quarter precincts; sustainability-led premium |
| Mirvac | Sydney | Residential master-planned, apartments | Strong green credentials; build-to-rent expansion |
| Crown Group | Sydney | High-rise luxury apartments | Iconic architectural developments; international buyer targeting |
| Gurner™ | Melbourne | Ultra-prime, wellness-centric | Branded wellness residences; aggressive Brisbane expansion |
| Frasers Property Australia | Sydney | Mixed-use, townhouses, apartments | Ed.Square and Central Park; focus on placemaking |
Beyond these majors, boutique developers such as Chapter Group, Time & Place, and Luxcon are gaining share in Sydney and Melbourne’s inner rings by offering highly bespoke, design-led product. Our primary interviews reveal that access to premium land sites—particularly waterfront and harbour-view parcels—is the single greatest competitive moat, with off-market land transactions now commanding 15–20% premiums over public listings.
By Property Type: Apartments and condominiums held 64% of market value in 2025, reflecting the dominance of high-rise luxury in Sydney and Melbourne. However, villas and landed houses are forecast to grow at a 9.0% CAGR through 2031, as ultra-high-net-worth families prioritise land scarcity and privacy.
By Business Model: The sales channel represented 81% of market size in 2025, but the rental segment is expanding at 8.4% annually, propelled by institutional build-to-rent platforms and a chronic shortage of premium rental stock. We estimate purpose-built luxury rental developments will account for 12–15% of new prime supply by 2030.
By Mode of Sale: Secondary transactions controlled 57% of value in 2025, underscoring the maturity of established luxury precincts. Yet the primary market is forecast to grow at 8.55% per year through 2031 as new branded-residence projects and master-planned communities enter delivery.
Sydney remains the undisputed epicentre of Australian luxury residential real estate, capturing 40% of 2025 revenue. The harbour city's prime markets—Point Piper, Bellevue Hill, Vaucluse, and Mosman—benefit from acute land scarcity, global brand recognition, and deep UHNW concentration. Our proprietary pricing index shows Sydney prime values rose 6.8% in 2025, with waterfront properties outperforming inland prime by 300 basis points.
Melbourne holds the second-largest share at an estimated 27%, though its luxury market has lagged Sydney in price growth due to higher land supply and a more subdued interstate migration profile. However, Melbourne's inner-east (Toorak, Malvern, Armadale) and bayside (Brighton) precincts remain resilient, with expatriate demand underpinning the top end.
Brisbane is the standout growth market, forecast to expand at a 9.2% CAGR through 2031. The 2032 Olympic Games infrastructure pipeline, combined with a net interstate migration surge, has catalysed luxury demand in Teneriffe, New Farm, and the Gold Coast hinterland. Our developer survey indicates that Brisbane luxury land values have doubled since 2020, and branded-residence pipelines are at record highs.
Perth captured an estimated 9% share, with the western suburbs (Peppermint Grove, Cottesloe, Dalkeith) benefiting from resource-sector wealth and a strong expatriate return flow. Perth led prime price growth at 3.7% annually in 2024, according to industry benchmarks, and we expect it to sustain 6–7% annual growth through 2028.
The Rest of Australia—including Adelaide, Canberra, and key regional lifestyle markets such as Byron Bay and Noosa—accounts for approximately 5% of luxury value, but these enclaves exhibit high volatility and strong lifestyle-driven demand.
Our analysis identifies three under-served strategic white spaces in the Australian luxury residential market:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.80% from 2020-2034 |
| Segmentation |
|
By Mode of Sale
| By Geography |
|
The market is valued at USD 30.80 billion in 2026 and is projected to reach USD 44.80 billion by 2031, growing at a CAGR of 7.80%.
Sydney captured 40% of market revenue in 2025, driven by acute land scarcity and strong UHNW demand. Brisbane is the fastest-growing market with a 9.2% CAGR.
Key drivers include Asia-Pacific UHNW inflows, branded-residence schemes (+1.4% to CAGR), green-rated stock premiums (+1.1%), and expatriate wealth repatriation (+0.9%).
Lendlease, Mirvac, Crown Group, Gurner™, and Frasers Property Australia are among the leading developers, alongside boutique players like Chapter Group and Time & Place.
The rental segment is expanding at 8.4% annually through 2031, driven by institutional build-to-rent platforms and a shortage of premium rental stock.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Development Officer | 30% |
| Head of Private Wealth | 25% |
| Luxury Property Broker | 25% |
| Portfolio Manager (Real Estate) | 20% |
| Company Type | Representation (%) |
|---|---|
| Luxury Developers and Project Marketers | 45% |
| Private Wealth Managers and Family Offices | 25% |
| High-Net-Worth Real Estate Brokers | 20% |
| Institutional Build-to-Rent Investors | 10% |