1What is the market size of India facility management market in 2025?
The India facility management market was valued at USD 2.86 Billion in 2025 and is projected to reach USD 7.13 Billion by 2034, growing at a CAGR of 10.66% from 2026 to 2034.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Regional Dynamics of India Facility Management Market
 by Solution (Facility Operations and Security Management, Others), by Service (Deployment and Integration, Others), by Deployment Type (Cloud-based, On-premise), by Organization Size (Large Enterprises, SMEs), by Vertical (IT and Telecom, Commercial, Healthcare, Industrial, Infrastructure and Government, Others), by South India (Bengaluru, Chennai, Hyderabad), by North India (Delhi NCR, Punjab, Uttar Pradesh), by West India (Mumbai, Pune, Gujarat), by East India (Kolkata, Odisha, Jharkhand) Forecast 2026-2034

Research Analyst


 Related Reports

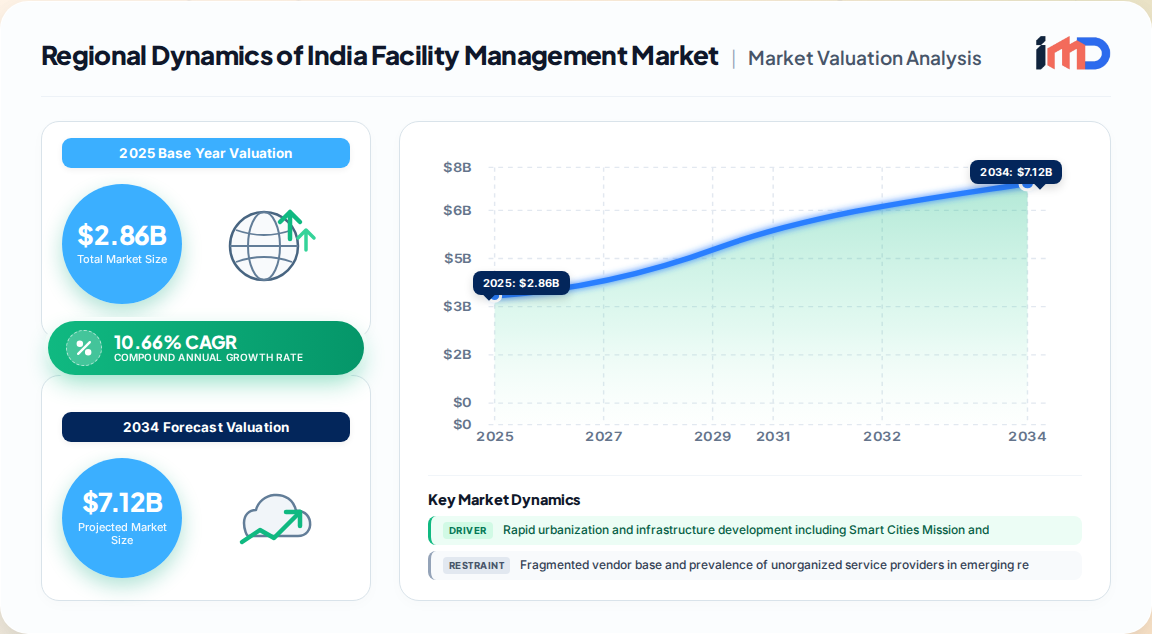
The India facility management market represents one of the most dynamic and geographically uneven service landscapes in the Asia-Pacific built-environment economy. Our proprietary primary research estimates the market at USD 2.86 Billion in 2025, expanding to USD 3.20 Billion in 2026 and projected to reach USD 7.13 Billion by 2034, registering a CAGR of 10.66% across the 2026–2034 forecast window.
Critically, this growth is not distributed uniformly. Regional dynamics are the single most important variable shaping competitive strategy, contract structures, workforce deployment, and technology adoption. South India commands 34% of national market value, followed by North India at 26%, West India at 22%, and East India at 18%. These shares are derived from our bottom-up municipal-level facility stock audits, cross-validated against commercial real estate absorption data and state infrastructure spending.
South India's 34% share is underpinned by a dense concentration of mission-critical facilities that demand integrated hard and soft services. Bengaluru alone accounts for a disproportionate share of India's Grade A office stock, with GCCs driving 35–40% of national office leasing in the first half of 2025, according to commercial real estate absorption tracking. Hyderabad's HITEC City and Chennai's industrial corridor add complementary demand profiles.
State government incentives—including Tamil Nadu's industrial policy and Telangana's IT expansion frameworks—continue to reinforce South India's leadership. Facility management providers operating here report higher contract values and greater willingness among clients to adopt outcome-based KPIs.
North India's 26% share reflects the National Capital Region's role as India's corporate and administrative nerve center. The region's demand profile is distinct: a mix of large enterprise headquarters, government and public infrastructure, healthcare institutions, and educational campuses.
North India also exhibits the highest concentration of large-enterprise clients, which account for a 54% share of the national market by organization size. These clients demand standardized multi-site service delivery and centralized compliance management.
West India holds 22% of national market value, anchored by Mumbai's financial services and media real estate, Pune's dual manufacturing-IT identity, and Gujarat's industrial and port-led infrastructure.
The West is also emerging as a sustainability leader, with green building certifications influencing service specifications across commercial and industrial portfolios.
East India's 18% share understates its strategic importance. The region is growing from a lower base but exhibits the steepest adoption curve for organized facility management, as historically in-house service models give way to professional outsourcing.
East India's challenge is the prevalence of unorganized service providers, which constrains pricing and quality standardization. However, this fragmentation also represents the largest white-space opportunity for organized players establishing regional hubs.
The regional variation in demand is closely coupled with solution and service segmentation. Nationally, facility operations and security management dominate with a 34% share, while deployment and integration services lead with 30%. Cloud-based deployment holds 58%, and IT/telecom is the largest vertical at 22%.
| Region | Dominant Vertical | Key Demand Characteristic | Cloud Adoption Posture |
|---|---|---|---|
| South India | IT & Telecom | Mission-critical uptime, predictive maintenance | High; real-time monitoring |
| North India | Commercial & Healthcare | Compliance, multi-site standardization | Moderate; centralized dashboards |
| West India | Financial & Industrial | Security integration, safety protocols | Moderate to high |
| East India | Healthcare & Industrial | Hard services, equipment reliability | Emerging; cost-sensitive |
Our regional attractiveness index weights market size, growth velocity, contract value, regulatory maturity, and technology-readiness.
| Region | Market Share (2025) | Attractiveness Score | Primary Opportunity |
|---|---|---|---|
| South India | 34% | Very High | Integrated FM contracts with ESG-linked KPIs |
| North India | 26% | High | Large-enterprise multi-site standardization |
| West India | 22% | High | Industrial safety and specialized hard services |
| East India | 18% | Medium-High | First-mover organized FM in healthcare and logistics |
South India warrants continued capital deployment for technology platforms and workforce training, while East India offers first-mover advantages for providers willing to invest in local supply chains and training infrastructure.
Several under-penetrated intersections emerge when regional data is crossed with segment data.
National providers must reconcile regional heterogeneity with service standardization. Our interviews with facility management executives reveal three predominant strategies.
The shift toward integrated facility management and outcome-based contracting is most advanced in South India, where clients demand measurable KPIs on energy efficiency and response times. Providers that build regional bench strength while maintaining national technology platforms will capture disproportionate share as the market nearly triples by 2034.
The India facility management market is services-led, with limited direct cross-border trade in facility services. However, the supply chain for facility management—spanning equipment, safety devices, software platforms, and consumables—exhibits significant import dependence.
Regionally, South India's ports (Chennai, Krishnapatnam) and West India's (JNPT, Mundra) serve as primary entry points for imported facility equipment, while East India remains more dependent on domestic supply chains.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.66% from 2020-2034 |
| Segmentation |
|
By Deployment Type
By Organization Size
By Vertical
| By Geography |
|
The India facility management market was valued at USD 2.86 Billion in 2025 and is projected to reach USD 7.13 Billion by 2034, growing at a CAGR of 10.66% from 2026 to 2034.
South India is the largest region with a 34% share in 2025, driven by the concentration of IT corridors, manufacturing hubs, and commercial real estate in Bengaluru, Chennai, and Hyderabad.
Key drivers include rapid urbanization, infrastructure development, government initiatives like Smart Cities Mission and Gati Shakti, growth of commercial real estate and Global Capability Centres, and increasing adoption of technology-enabled facility services.
By solution, facility operations and security management lead with 34% share; by service, deployment and integration lead with 30%; by deployment type, cloud-based holds 58%; and by organization size, large enterprises account for 54%.
Key players include CBRE Group, JLL, ISS A/S, Sodexo, Cushman & Wakefield, Compass Group, and other facility management providers expanding service portfolios with IoT, AI, and sustainable practices.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Operating Officer (Facility Management) | 30% |
| Head of Procurement and Contracts | 25% |
| Regional Facility Director | 25% |
| Energy and Sustainability Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Integrated Facility Management Providers | 30% |
| Hard Services Contractors | 25% |
| Soft Services Providers | 20% |
| FM Software & IoT Vendors | 15% |
| Industrial Safety Equipment Manufacturers | 10% |