About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
report thumbnailANZ Cloud Computing Market
Technology, Media and Telecom / MARKET REPORT

ANZ Cloud Computing Market | Insight Market Data

ANZ Cloud Computing Market by Deployment Type (Public Cloud, Hybrid Cloud, Private Cloud), by Service Model (Infrastructure as a Service (IaaS), Platform as a Service (PaaS), Software as a Service (SaaS)), by Organization Size (Small and Medium Enterprises (SMEs), Large Enterprises), by End-User Industry (BFSI, Healthcare, Manufacturing, Education, Government, Mining, Agriculture, Retail, Others), by Australia (Sydney, Melbourne, Canberra, Western Australia, Queensland, Northern Territory), by New Zealand (Auckland, Wellington, Rural Regions) Forecast 2026-2034

© Nov 2, 2026|Base Year: 2025|201 Pages
Srinwanti Kar

Srinwanti Kar

Senior Research Analyst

Main Logo

ANZ Cloud Computing Market Size, Growth & Forecast to 2031


/
/

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Buy Now
Home
Industries
Technology, Media and Telecom
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
Author
Srinwanti Kar

Srinwanti Kar

Senior Research Analyst

I am a Senior Research Analyst delivering high-impact market intelligence across Technology, Media, and Telecom (TMT), ICT, and Semiconductors & Electronics. My expertise spans Manufacturing Products and Services, Construction, Automation, Communication Services, and other emerging sectors. I specialize in market sizing and technological forecasting, translating complex industrial and digital trends into strategic insights that help global clients unlock new opportunities.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 02, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

Government ODM Platform Market Barriers: 2025 Analysis

Proprietary analysis of barriers in the Government Open Data Management platform market: $158.4M (2025), 8.2% CAGR, data privacy, legacy inertia & talent gaps.

Nov 2026|222 pages
$2900.00View report

Algeria telecom market at USD 2.73B in 2026, growing at 1.75% CAGR to USD 2.97B by 2031. Data, FTTH, and 5G drive MNO revenue.

Nov 2026|207 pages
$2900.00

SaaS Backup Software market to reach $5.12 Billion by 2035 at 15.61% CAGR. Explore key trends, top companies, and regional insights in this comprehensive report.

Nov 2026|190 pages
$2900.00

Morocco telecom market to reach USD 4.64 billion by 2031, growing at 3.72% CAGR. Data, 5G, fiber, and enterprise drive growth. Get full analysis.

Nov 2026|270 pages
$2900.00

The global gymnastics club management software market is valued at $1.24 billion in 2025 and is projected to grow at a CAGR of 14.2% through 2035.

Nov 2026|235 pages
$2900.00
Algeria Telecom Market Size 2026 & Growth Forecast to 2031
View report
SaaS Backup Software Market Size, Growth & Forecast 2025-2035
View report
Morocco Telecom Market Size, Share & Growth Forecast 2026-2031
View report
Gymnastics Club Management Software Market | 2025-2035
View report
ANZ Cloud Computing Market CAGR, market size, market share

Executive Overview: ANZ Cloud Computing Market

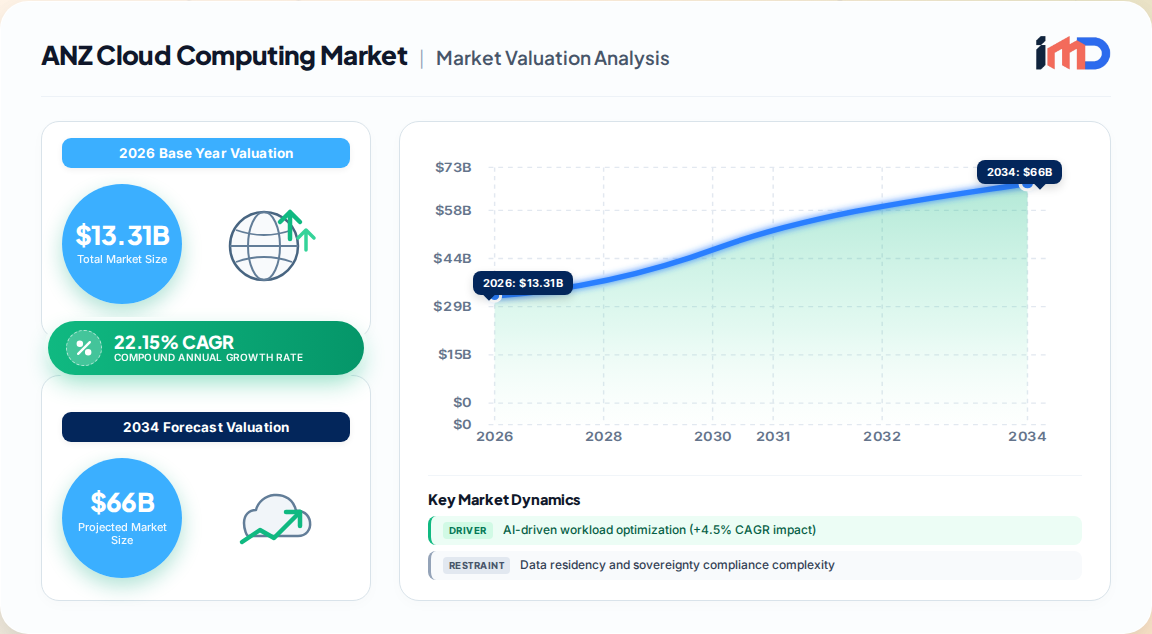
The Australia and New Zealand (ANZ) cloud computing market is undergoing a structural inflection, transitioning from a phase of broad-based adoption to one defined by sovereign compliance, AI workload optimization, and edge-cloud convergence. Our proprietary primary research estimates the market at USD 13.31 billion in 2026, expanding from USD 10.89 billion in 2025 and projected to reach USD 36.27 billion by 2031, representing a robust CAGR of 22.15% over the forecast period. This growth trajectory is not merely a continuation of historical trends but a rebalancing of public, hybrid, and edge deployments driven by regulatory mandates and enterprise modernization imperatives.

ANZ Cloud Computing Market Market Size (In Billion)

40.0B
30.0B
20.0B
10.0B
0
10.90 B
2025
13.31 B
2026
16.26 B
2027
19.86 B
2028
24.26 B
2029
29.63 B
2030
36.20 B
2031
Main Logo

Market concentration is assessed as medium, with hyperscale providers competing intensely alongside sovereign-cloud specialists and regional systems integrators. The competitive landscape is shaped by the need to satisfy data residency requirements under Australia's Cyber Security Act 2024 and New Zealand's Customer and Product Data Bill, while simultaneously delivering global performance advantages. Enterprises are accelerating platform modernization through containerized architectures, shortening release cycles, and aligning cloud investments with carbon-neutral commitments.

Metric 2025 (Base) 2026 (Estimated) 2031 (Forecast) CAGR (2026-2031)
Market Size (USD) 10.89 Billion 13.31 Billion 36.27 Billion 22.15%
Public Cloud Share 68.85% - - -
Large Enterprise Share 75.62% - - -
Australia Revenue Share 78.92% - - -
New Zealand Growth - - - 24.98%

Market Drivers: Sovereignty, AI, and Edge Convergence

The ANZ cloud market is propelled by a confluence of regulatory, technological, and operational drivers. Our impact analysis quantifies the relative contribution of each driver to the forecast CAGR, with AI-driven workload optimization emerging as the most potent long-term catalyst.

  • AI-Driven Workload Optimization (+4.5% impact on CAGR): The adoption of generative AI is driving demand for GPU-dense instances and custom accelerators. The local launch of AWS Trainium2 chips and Google TPUs in Sydney and Melbourne regions reduces training costs by approximately 30%, enabling enterprises to fine-tune large language models on domestic datasets without cross-border transfer penalties. This is a long-term driver (≥4 years) concentrated in hyperscaler regions.
  • Accelerated Adoption of Cloud-Native Technologies (+4.2% impact): Enterprises are decomposing monolithic systems into microservices to gain portability, reduce vendor lock-in, and meet audit controls under APRA CPS 234. Major banks have refactored payment platforms on container stacks, cutting latency by 30% and enabling real-time fraud monitoring. Managed Kubernetes services now mask cluster complexity, bringing 94% of Australian SMEs into the cloud in 2025, up from 78% two years earlier.
  • Surge in Enterprise Demand for Flexible IT Infrastructure (+3.8% impact): Hybrid adoption continues to swell as 72% of organizations orchestrate regulated data on-premises or in sovereign facilities while bursting variable workloads to public regions. Financial institutions anchor core ledgers in IRAP-certified sites while leveraging public-cloud analytics. Government policies classifying PROTECTED data force agencies to blend private and public footprints, reinforcing hybrid as the default.
  • Heightened Government Digital Transformation Programs (+3.5% impact): Australia's myGov and New Zealand's Te Whatu Ora migrations demonstrate how cloud-first mandates accelerate modernization. Funding pools exceeding USD 720 million in New Zealand, along with compliance frameworks such as ISO 27001, have raised the bar for security and observability. Consolidating legacy estates into unified cloud backbones reduces infrastructure overhead by up to 40%.
  • Edge-Cloud Convergence (+2.9% impact): Remote mining and agriculture operations in Western Australia, Queensland, the Northern Territory, and rural New Zealand require sub-50-millisecond latency for mission-critical workloads. Edge-cloud convergence is a long-term driver enabling real-time analytics and autonomous operations.
  • Rising Carbon-Offset Mandates (+2.4% impact): Climate Active and net-zero commitments are steering investments toward renewable-powered data centers.

Market Restraints and Challenges

Despite the robust growth outlook, the ANZ cloud market faces structural and operational headwinds that temper the pace of adoption.

  • Data Residency and Sovereignty Complexity: Regulatory mandates under Australia's Cyber Security Act 2024 and New Zealand's Customer and Product Data Bill increase compliance costs. Enterprises must maintain locally hosted hyperscale capacity that meets sovereignty requirements while retaining global performance, creating a complex dual-footprint architecture.
  • Skills Shortage and Talent Gap: The accelerated adoption of cloud-native technologies and AI workloads has intensified demand for specialized skills in Kubernetes, service mesh, and AI/ML operations. This talent gap is particularly acute in New Zealand and regional Australia.
  • Legacy System Integration: Consolidating fragmented legacy estates into unified cloud backbones remains a challenge, with interoperability issues and migration risks slowing time-to-value for some organizations.
  • Cost Optimization Pressures: While cloud offers elasticity, unmanaged consumption can lead to cost overruns. Organizations are increasingly shifting 15-25% of total workloads between providers each year to optimize price-performance profiles, indicating a need for better cost governance.

Segmentation Analysis: Deployment, Service Model, and End-User Dynamics

The ANZ cloud market exhibits distinct segment-level dynamics that inform strategic prioritization.

Segment 2025 Share / Growth Key Insight
Public Cloud (Deployment) 68.85% share Dominant deployment model; hyperscale regions in Sydney and Melbourne anchor demand.
Hybrid Cloud (Deployment) 22.40% CAGR (2026-2031) Fastest-growing deployment type; driven by regulated workloads and sovereign requirements.
SaaS (Service Model) 46.75% revenue share Largest service model; led by productivity, CRM, and ERP applications.
PaaS (Service Model) 24.89% CAGR (2026-2031) Fastest-growing service model; fueled by containerization and AI/ML platforms.
Large Enterprises (Organization Size) 75.62% share Dominant buyer segment; complex multi-cloud and hybrid architectures.
SMEs (Organization Size) 23.42% CAGR to 2031 Rapid growth driven by managed Kubernetes and as-a-service consumption models.
BFSI (End-User Industry) 20.88% revenue share Largest vertical; APRA CPS 234 compliance drives sovereign cloud adoption.
Healthcare (End-User Industry) 22.76% CAGR (2025-2031) Fastest-growing vertical; Te Whatu Ora migration and digital health records.

Regional Outlook: Australia and New Zealand

Geographic analysis reveals a market led by Australia, with New Zealand poised for accelerated growth.

ANZ Cloud Computing Market Regional Market Share

Loading chart...
Main Logo
  • Australia: Accounted for 78.92% of 2025 revenue. The market is concentrated in Sydney, Melbourne, and Canberra, driven by hyperscaler regions, government digital transformation, and a strong BFSI sector. Western Australia and Queensland are emerging as edge-cloud hubs for mining and agriculture.
  • New Zealand: Projected to grow at a 24.98% CAGR through 2031. The market is buoyed by the Te Whatu Ora healthcare migration, government cloud-first mandates, and a funding pool exceeding USD 720 million. Auckland is the primary hyperscale region, with rural regions benefiting from edge-cloud convergence.

Competitive Landscape and Strategic Developments

The ANZ cloud market is characterized by a mix of global hyperscalers, sovereign-cloud specialists, and regional integrators. Microsoft Corporation, Amazon Web Services (AWS), Google LLC (Alphabet Inc.), IBM Corporation, and Oracle Corporation are the major companies operating in this market, each with distinct sovereign and edge strategies.

  • Sovereign Cloud Investments: Hyperscalers are expanding local regions with IRAP-certified facilities to meet PROTECTED data requirements. Sovereign cloud offerings from Microsoft and AWS are gaining procurement preference.
  • AI Infrastructure Rollouts: The local launch of AWS Trainium2 chips and Google TPUs in 2026 is a key development, reducing training costs by approximately 30% and enabling domestic AI innovation.
  • Edge Partnerships: Cloud providers are partnering with mining and agricultural enterprises to deploy edge nodes in remote Western Australia and rural New Zealand, ensuring sub-50-millisecond latency.
  • Green Data Center Commitments: Rising carbon-offset mandates are driving investments in renewable-powered data centers, with Climate Active certification becoming a competitive differentiator.

Value Chain and Supply Dynamics

The ANZ cloud computing value chain spans infrastructure providers, platform vendors, service integrators, and end-users. Unlike physical commodities, cloud services are delivered via data center infrastructure, with supply dynamics shaped by energy availability, connectivity, and regulatory approvals.

  • Upstream: Data center real estate, power (renewable energy), and hardware (servers, GPUs, networking). Supply constraints include energy grid capacity, particularly in New Zealand, and land availability in Sydney and Melbourne.
  • Midstream: Cloud service providers (hyperscalers, sovereign providers) and platform vendors offering IaaS, PaaS, and SaaS. Managed service providers and systems integrators add value through migration, security, and optimization services.
  • Downstream: Enterprises across BFSI, healthcare, manufacturing, education, and government. Consumption models are shifting toward as-a-service and subscription-based pricing.
  • Supply Chain Risk: Hardware supply chain disruptions, energy price volatility, and skills shortages are key risks. The concentration of hyperscale capacity in Sydney and Melbourne creates geographic concentration risk.

Strategic White-Space Analysis

Our analysis identifies several underpenetrated opportunities within the ANZ cloud market.

  • SME Cloud Adoption in New Zealand: While Australian SMEs have reached 94% cloud adoption, New Zealand SMEs lag, presenting a growth opportunity for managed Kubernetes and as-a-service offerings.
  • Edge-Cloud for Agriculture and Mining: Remote operations in Western Australia, Queensland, and rural New Zealand require specialized edge solutions with low latency and ruggedized hardware.
  • Healthcare Cloud Modernization: New Zealand's Te Whatu Ora migration is a template for healthcare cloud adoption, with opportunities in data interoperability, telehealth, and AI-driven diagnostics.
  • Green Cloud Services: Carbon-offset mandates create demand for renewable-powered data centers and carbon-aware workload scheduling.

Methodology

This report is based on a rigorous research methodology combining primary and secondary research.

Primary Research

  • 70-80% of research effort, involving interviews with C-suite executives, cloud architects, procurement directors, and government IT leaders.
  • 4-5 specific company types: hyperscale cloud providers, sovereign cloud specialists, managed service providers (MSPs), independent software vendors (ISVs), and systems integrators.
  • 3-4 stakeholder job titles: Chief Information Officer (CIO), Chief Technology Officer (CTO), Head of Cloud Infrastructure, and Procurement Director.
  • 3-4 industry associations: Australian Information Industry Association (AIIA), New Zealand Computer Society (NZCS), Cloud Security Alliance (CSA), and Australian Cyber Security Centre (ACSC).
  • 3-4 quantitative metrics: cloud spend per employee, workload migration rates, data center capacity (MW), and contract values (ACV).

Secondary Research & Industry Benchmarking

  • 20-30% of research effort, leveraging financial databases (Bloomberg, Factiva, Hoovers, PitchBook) and official sources (.gov, .org).
  • Benchmarking against Australian Bureau of Statistics (ABS) and Statistics New Zealand data, and OECD digital economy indicators.

Demand Modeling & Market Estimation

  • Top-down and bottom-up methodologies validated via multi-level data triangulation.
  • Bottom-up estimation based on cloud consumption by enterprise size, vertical, and deployment type.
  • Demand modeling incorporates GDP growth, IT spending forecasts, and regulatory timelines.

Data Accuracy & Quality Check

  • Guaranteed estimated data accuracy level of 85-90%.
  • Every report updated to the date of purchase.
  • Multi-level data triangulation and expert review ensure reliability.

ANZ Cloud Computing Market Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

ANZ Cloud Computing Market REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2026
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 22.15% from 2020-2034
Segmentation
  • By Deployment Type

    • Public Cloud
    • Hybrid Cloud
    • Private Cloud
  • By Service Model

    • Infrastructure as a Service

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. AI-driven workload optimization (+4.5% CAGR impact)
      • 3.1.2. Accelerated adoption of cloud-native technologies (+4.2% CAGR impact)
      • 3.1.3. Surge in enterprise demand for flexible IT infrastructure (+3.8% CAGR impact)
      • 3.1.4. Heightened government digital transformation programs (+3.5% CAGR impact)
      • 3.1.5. Edge-cloud convergence for remote operations (+2.9% CAGR impact)
      • 3.1.6. Rising carbon-offset mandates promoting green data centers (+2.4% CAGR impact)
    • 3.2. Market Trends
      • 3.2.1. Sovereign-cloud strategies driven by data residency mandates
      • 3.2.2. AI workload optimization with local GPU and TPU instances
      • 3.2.3. Edge-cloud convergence for mining and agriculture operations
      • 3.2.4. Containerized architectures and platform modernization
      • 3.2.5. Carbon-neutral commitments steering green data center investments
    • 3.3. Market Restrains
      • 3.3.1. Data residency and sovereignty compliance complexity
      • 3.3.2. Skills shortage in cloud-native and AI technologies
      • 3.3.3. Legacy system integration challenges
  • IaaS
  • Platform as a Service
    • PaaS
  • Software as a Service
    • SaaS
  • By Organization Size

    • Small and Medium Enterprises
      • SMEs
    • Large Enterprises
  • By End-User Industry

    • BFSI
    • Healthcare
    • Manufacturing
    • Education
    • Government
    • Mining
    • Agriculture
    • Retail
    • Others
  • By Geography
    • Australia

      • Sydney
      • Melbourne
      • Canberra
      • Western Australia
      • Queensland
      • Northern Territory
    • New Zealand

      • Auckland
      • Wellington
      • Rural Regions
  • 3.3.4. Cost optimization pressures and cloud spend governance
  • 3.4. Market Restraints
    • 3.4.1. Data residency and sovereignty compliance complexity
    • 3.4.2. Skills shortage in cloud-native and AI technologies
    • 3.4.3. Legacy system integration challenges
    • 3.4.4. Cost optimization pressures and cloud spend governance
  • 3.5. Market Challenges
    • 3.5.1. Managing multi-cloud complexity and interoperability
    • 3.5.2. Attracting and retaining specialized cloud talent
    • 3.5.3. Balancing sovereignty requirements with global performance
    • 3.5.4. Mitigating energy supply constraints for data centers
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Deployment Type
      • 5.1.1. Public Cloud
      • 5.1.2. Hybrid Cloud
      • 5.1.3. Private Cloud
    • 5.2. Market Analysis, Insights and Forecast - by Service Model
      • 5.2.1. Infrastructure as a Service
        • 5.2.1.1. IaaS
      • 5.2.2. Platform as a Service
        • 5.2.2.1. PaaS
      • 5.2.3. Software as a Service
        • 5.2.3.1. SaaS
    • 5.3. Market Analysis, Insights and Forecast - by Organization Size
      • 5.3.1. Small and Medium Enterprises
        • 5.3.1.1. SMEs
      • 5.3.2. Large Enterprises
    • 5.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 5.4.1. BFSI
      • 5.4.2. Healthcare
      • 5.4.3. Manufacturing
      • 5.4.4. Education
      • 5.4.5. Government
      • 5.4.6. Mining
      • 5.4.7. Agriculture
      • 5.4.8. Retail
      • 5.4.9. Others
    • 5.5. Market Analysis, Insights and Forecast - by Region
      • 5.5.1. Australia
      • 5.5.2. New Zealand
  • 6. Australia Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Deployment Type
      • 6.1.1. Public Cloud
      • 6.1.2. Hybrid Cloud
      • 6.1.3. Private Cloud
    • 6.2. Market Analysis, Insights and Forecast - by Service Model
      • 6.2.1. Infrastructure as a Service
        • 6.2.1.1. IaaS
      • 6.2.2. Platform as a Service
        • 6.2.2.1. PaaS
      • 6.2.3. Software as a Service
        • 6.2.3.1. SaaS
    • 6.3. Market Analysis, Insights and Forecast - by Organization Size
      • 6.3.1. Small and Medium Enterprises
        • 6.3.1.1. SMEs
      • 6.3.2. Large Enterprises
    • 6.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 6.4.1. BFSI
      • 6.4.2. Healthcare
      • 6.4.3. Manufacturing
      • 6.4.4. Education
      • 6.4.5. Government
      • 6.4.6. Mining
      • 6.4.7. Agriculture
      • 6.4.8. Retail
      • 6.4.9. Others
  • 7. New Zealand Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Deployment Type
      • 7.1.1. Public Cloud
      • 7.1.2. Hybrid Cloud
      • 7.1.3. Private Cloud
    • 7.2. Market Analysis, Insights and Forecast - by Service Model
      • 7.2.1. Infrastructure as a Service
        • 7.2.1.1. IaaS
      • 7.2.2. Platform as a Service
        • 7.2.2.1. PaaS
      • 7.2.3. Software as a Service
        • 7.2.3.1. SaaS
    • 7.3. Market Analysis, Insights and Forecast - by Organization Size
      • 7.3.1. Small and Medium Enterprises
        • 7.3.1.1. SMEs
      • 7.3.2. Large Enterprises
    • 7.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 7.4.1. BFSI
      • 7.4.2. Healthcare
      • 7.4.3. Manufacturing
      • 7.4.4. Education
      • 7.4.5. Government
      • 7.4.6. Mining
      • 7.4.7. Agriculture
      • 7.4.8. Retail
      • 7.4.9. Others
  • 8. Competitive Analysis
    • 8.1. Company Profiles
      • 8.1.1. Microsoft Corporation
        • 8.1.1.1. Company Overview
        • 8.1.1.2. Products
        • 8.1.1.3. Company Financials
        • 8.1.1.4. SWOT Analysis
      • 8.1.2. Amazon Web Services (AWS)
        • 8.1.2.1. Company Overview
        • 8.1.2.2. Products
        • 8.1.2.3. Company Financials
        • 8.1.2.4. SWOT Analysis
      • 8.1.3. Google LLC (Alphabet Inc.)
        • 8.1.3.1. Company Overview
        • 8.1.3.2. Products
        • 8.1.3.3. Company Financials
        • 8.1.3.4. SWOT Analysis
      • 8.1.4. IBM Corporation
        • 8.1.4.1. Company Overview
        • 8.1.4.2. Products
        • 8.1.4.3. Company Financials
        • 8.1.4.4. SWOT Analysis
      • 8.1.5. Oracle Corporation
        • 8.1.5.1. Company Overview
        • 8.1.5.2. Products
        • 8.1.5.3. Company Financials
        • 8.1.5.4. SWOT Analysis
    • 8.2. Market Entropy
      • 8.2.1. Company's Key Areas Served
      • 8.2.2. Recent Developments
    • 8.3. Company Market Share Analysis, 2026
      • 8.3.1. Top 5 Companies Market Share Analysis
      • 8.3.2. Top 3 Companies Market Share Analysis
    • 8.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global ANZ Cloud Computing Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: Australia ANZ Cloud Computing Market Revenue (Billion), by Deployment Type 2026 & 2034
    3. Figure 3: Australia ANZ Cloud Computing Market Revenue Share (%), by Deployment Type 2026 & 2034
    4. Figure 4: Australia ANZ Cloud Computing Market Revenue (Billion), by Service Model 2026 & 2034
    5. Figure 5: Australia ANZ Cloud Computing Market Revenue Share (%), by Service Model 2026 & 2034
    6. Figure 6: Australia ANZ Cloud Computing Market Revenue (Billion), by Organization Size 2026 & 2034
    7. Figure 7: Australia ANZ Cloud Computing Market Revenue Share (%), by Organization Size 2026 & 2034
    8. Figure 8: Australia ANZ Cloud Computing Market Revenue (Billion), by End-User Industry 2026 & 2034
    9. Figure 9: Australia ANZ Cloud Computing Market Revenue Share (%), by End-User Industry 2026 & 2034
    10. Figure 10: Australia ANZ Cloud Computing Market Revenue (Billion), by Country 2026 & 2034
    11. Figure 11: Australia ANZ Cloud Computing Market Revenue Share (%), by Country 2026 & 2034
    12. Figure 12: New Zealand ANZ Cloud Computing Market Revenue (Billion), by Deployment Type 2026 & 2034
    13. Figure 13: New Zealand ANZ Cloud Computing Market Revenue Share (%), by Deployment Type 2026 & 2034
    14. Figure 14: New Zealand ANZ Cloud Computing Market Revenue (Billion), by Service Model 2026 & 2034
    15. Figure 15: New Zealand ANZ Cloud Computing Market Revenue Share (%), by Service Model 2026 & 2034
    16. Figure 16: New Zealand ANZ Cloud Computing Market Revenue (Billion), by Organization Size 2026 & 2034
    17. Figure 17: New Zealand ANZ Cloud Computing Market Revenue Share (%), by Organization Size 2026 & 2034
    18. Figure 18: New Zealand ANZ Cloud Computing Market Revenue (Billion), by End-User Industry 2026 & 2034
    19. Figure 19: New Zealand ANZ Cloud Computing Market Revenue Share (%), by End-User Industry 2026 & 2034
    20. Figure 20: New Zealand ANZ Cloud Computing Market Revenue (Billion), by Country 2026 & 2034
    21. Figure 21: New Zealand ANZ Cloud Computing Market Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global ANZ Cloud Computing Market Revenue Billion Forecast, by Deployment Type 2020 & 2034
    2. Table 2: Global ANZ Cloud Computing Market Revenue Billion Forecast, by Service Model 2020 & 2034
    3. Table 3: Global ANZ Cloud Computing Market Revenue Billion Forecast, by Organization Size 2020 & 2034
    4. Table 4: Global ANZ Cloud Computing Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
    5. Table 5: Global ANZ Cloud Computing Market Revenue Billion Forecast, by Region 2020 & 2034
    6. Table 6: Australia ANZ Cloud Computing Market Revenue Billion Forecast, by Deployment Type 2020 & 2034
    7. Table 7: Australia ANZ Cloud Computing Market Revenue Billion Forecast, by Service Model 2020 & 2034
    8. Table 8: Australia ANZ Cloud Computing Market Revenue Billion Forecast, by Organization Size 2020 & 2034
    9. Table 9: Australia ANZ Cloud Computing Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
    10. Table 10: Australia ANZ Cloud Computing Market Revenue Billion Forecast, by Country 2020 & 2034
    11. Table 11: Sydney ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034
    12. Table 12: Melbourne ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034
    13. Table 13: Canberra ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034
    14. Table 14: Western Australia ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034
    15. Table 15: Queensland ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034
    16. Table 16: Northern Territory ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034
    17. Table 17: New Zealand ANZ Cloud Computing Market Revenue Billion Forecast, by Deployment Type 2020 & 2034
    18. Table 18: New Zealand ANZ Cloud Computing Market Revenue Billion Forecast, by Service Model 2020 & 2034
    19. Table 19: New Zealand ANZ Cloud Computing Market Revenue Billion Forecast, by Organization Size 2020 & 2034
    20. Table 20: New Zealand ANZ Cloud Computing Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
    21. Table 21: New Zealand ANZ Cloud Computing Market Revenue Billion Forecast, by Country 2020 & 2034
    22. Table 22: Auckland ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034
    23. Table 23: Wellington ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034
    24. Table 24: Rural Regions ANZ Cloud Computing Market Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the size of the ANZ cloud computing market in 2026?

    The ANZ cloud computing market is estimated at USD 13.31 billion in 2026, growing from USD 10.89 billion in 2025, with a projected CAGR of 22.15% to reach USD 36.27 billion by 2031.

    2Which country dominates the ANZ cloud computing market?

    Australia accounted for 78.92% of the 2025 revenue, while New Zealand is projected to grow at a faster CAGR of 24.98% through 2031.

    3What are the key drivers of the ANZ cloud computing market?

    Key drivers include AI-driven workload optimization (+4.5% CAGR impact), accelerated adoption of cloud-native technologies (+4.2%), and enterprise demand for flexible IT infrastructure (+3.8%).

    4Which deployment type is fastest-growing in the ANZ cloud market?

    Hybrid cloud is expanding at a 22.40% CAGR during 2026-2031, driven by data residency requirements and regulated workloads.

    5Who are the major players in the ANZ cloud computing market?

    Major companies include Microsoft Corporation, Amazon Web Services (AWS), Google LLC (Alphabet Inc.), IBM Corporation, and Oracle Corporation, alongside sovereign cloud specialists.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • 70-80% of research effort, involving interviews with C-suite executives, cloud architects, procurement directors, and government IT leaders.
    • 4-5 specific company types: hyperscale cloud providers, sovereign cloud specialists, managed service providers (MSPs), independent software vendors (ISVs), and systems integrators.
    • 3-4 stakeholder job titles: Chief Information Officer (CIO), Chief Technology Officer (CTO), Head of Cloud Infrastructure, and Procurement Director.
    • 3-4 industry associations: Australian Information Industry Association (AIIA), New Zealand Computer Society (NZCS), Cloud Security Alliance (CSA), and Australian Cyber Security Centre (ACSC).
    • 3-4 quantitative metrics: cloud spend per employee, workload migration rates, data center capacity (MW), and contract values (ACV).

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Chief Information Officer (CIO)35%
    Chief Technology Officer (CTO)25%
    Head of Cloud Infrastructure25%
    Procurement Director15%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Hyperscale Cloud Providers35%
    Sovereign Cloud Specialists20%
    Managed Service Providers (MSPs)20%
    Independent Software Vendors (ISVs)15%
    Systems Integrators10%

    Secondary Research & Industry Benchmarking

    • 20-30% of research effort, leveraging financial databases (Bloomberg, Factiva, Hoovers, PitchBook) and official sources (.gov, .org).
    • Benchmarking against Australian Bureau of Statistics (ABS) and Statistics New Zealand data, and OECD digital economy indicators.

    Demand Modeling & Market Estimation

    • Top-down and bottom-up methodologies validated via multi-level data triangulation.
    • Bottom-up estimation based on cloud consumption by enterprise size, vertical, and deployment type.
    • Demand modeling incorporates GDP growth, IT spending forecasts, and regulatory timelines.

    Data Accuracy & Quality Check

    • Guaranteed estimated data accuracy level of 85-90%.
    • Every report updated to the date of purchase.
    • Multi-level data triangulation and expert review ensure reliability.