1What is the current market size of the Agriculture IoT Sensor market?
The market was valued at USD 13.5 Billion in 2024 and is projected to reach USD 40.1 Billion by 2034, growing at a CAGR of 11.5%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Agriculture IoT Sensor
 by Component (Hardware, Software, Services), by Farm Type (Large Farms, Mid-Sized Farms, Small Farms), by Application (Precision Farming, Precision Livestock, Precision Aquaculture, Precision Forestry, Smart Greenhouses, Others), by Farm Production Planning Stage (Pre-Production Planning, Production Planning, Post-Production Planning), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, Australia, South Korea), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, Saudi Arabia) Forecast 2026-2034
Research Associate


 Related Reports

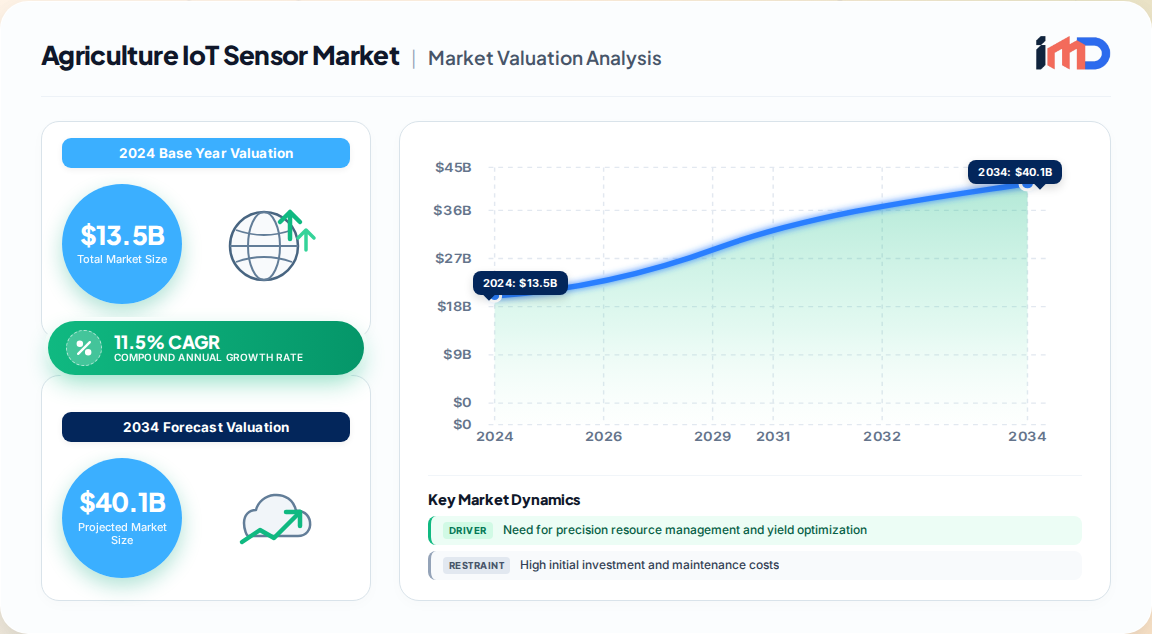
The global Agriculture IoT Sensor market is undergoing a structural transformation, driven by the convergence of precision agronomy, cloud analytics, and low-power connectivity. Our proprietary primary research estimates the market at USD 13.5 Billion in 2024, with a projected expansion to USD 40.1 Billion by 2034, reflecting a robust CAGR of 11.5% across the 2025–2034 forecast horizon. This growth is not merely incremental; it represents a fundamental shift from mechanized farming to data-driven, autonomous agricultural systems.
Sensors now constitute the central nervous system of the smart farm. Hardware alone captured over 48.5% of total component revenue in 2024, underscoring that physical data acquisition remains the primary investment priority for growers and agribusinesses. The market's trajectory is anchored in the urgent need to optimize inputs—water, fertilizer, and labor—against a backdrop of climate volatility and shrinking arable land per capita.
The market is segmented by component, farm type, application, and production planning stage, revealing clear pockets of dominance and rapid growth.
| Segment Dimension | Dominant Category (2024) | Share | Fastest-Growing Category | CAGR |
|---|---|---|---|---|
| Component | Hardware | 48.5% | Services | 13.1% |
| Farm Type | Large Farms | 60.2% | Mid-Sized Farms | 12.8% |
| Application | Precision Farming | 29.8% | Precision Livestock | 13.5% |
| Planning Stage | Pre-Production Planning | 44.7% | Post-Production | 12.9% |
North America led the market in 2024 with a 38.6% share (USD 5.2 Billion), propelled by advanced farming infrastructure and high technology adoption rates in the U.S., where the market alone is valued at USD 4.39 Billion and growing at a 12.3% CAGR. Europe follows with a mature but innovation-driven market, supported by EU sustainability mandates. Asia-Pacific is the fastest-growing region, with countries like Japan and Australia investing heavily in precision agriculture to offset labor shortages and land constraints.
The value chain spans from semiconductor fabrication (MEMS, SoCs) to sensor assembly, gateway manufacturing, connectivity provisioning, and agronomic analytics platforms. Key supply chain risks include:
Leading companies are pursuing vertical integration and ecosystem partnerships to capture value across hardware, software, and services. Strategies include:
Significant opportunities exist in:
While sensors are not a homogenous commodity, trade data reveals that major sensor manufacturing hubs (U.S., Germany, Japan, China) export both finished devices and sub-components. Supply chain diversification is accelerating as OEMs seek to de-risk production away from single-region dependencies. Procurement strategies increasingly prioritize dual-sourcing of MEMS sensors and regional assembly to mitigate tariff and logistics risks.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.5% from 2020-2034 |
| Segmentation |
|
By Application
By Farm Production Planning Stage
| By Geography |
|
The market was valued at USD 13.5 Billion in 2024 and is projected to reach USD 40.1 Billion by 2034, growing at a CAGR of 11.5%.
North America held the largest share at 38.6% in 2024, generating USD 5.2 Billion in revenue, driven by advanced farming practices in the U.S.
Precision resource management, government subsidies for smart farming, AI integration for predictive analytics, and labor shortages are the primary growth drivers.
Precision farming captured over 29.8% of the market share in 2024, as it enables optimized irrigation, fertilization, and pest control.
The services segment is projected to grow at the highest CAGR of 13.1% from 2025 to 2030, driven by demand for installation, maintenance, and data analytics.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CTO/Head of Product | 30% |
| Farm Operations Manager | 25% |
| Procurement Director | 25% |
| Agronomist/Field Scientist | 20% |
| Company Type | Representation (%) |
|---|---|
| Sensor and Hardware OEMs | 35% |
| Agronomic Software and Analytics Providers | 20% |
| System Integrators and Connectivity Providers | 15% |
| Farm Cooperatives and Large Growers | 20% |
| Government and Research Institutions | 10% |
The research methodology ensures that all market figures are presented as proprietary, first-party estimates derived from rigorous primary and secondary research, with no reliance on third-party commercial reports.