Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
US Commercial Office Construction Market | 2032 Forecast
US Commercial Office Construction Market
Real Estate and Construction / MARKET REPORT
US Commercial Office Construction Market | Insight Market Data
US Commercial Office Construction Market by Commercial Sector Type (Office, Industrial & Logistics, Retail, Others), by Construction Type (New Construction, Renovation), by Investment Source (Private, Public), by Contract Type (Design-Bid-Build, Design-Build, Construction Management at Risk), by Materials Used (Concrete, Steel, Wood, Glass), by United States (Texas, California, Florida, New York, Illinois, Rest of US) Forecast 2026-2034
Executive Overview: The US Commercial Office Construction Market
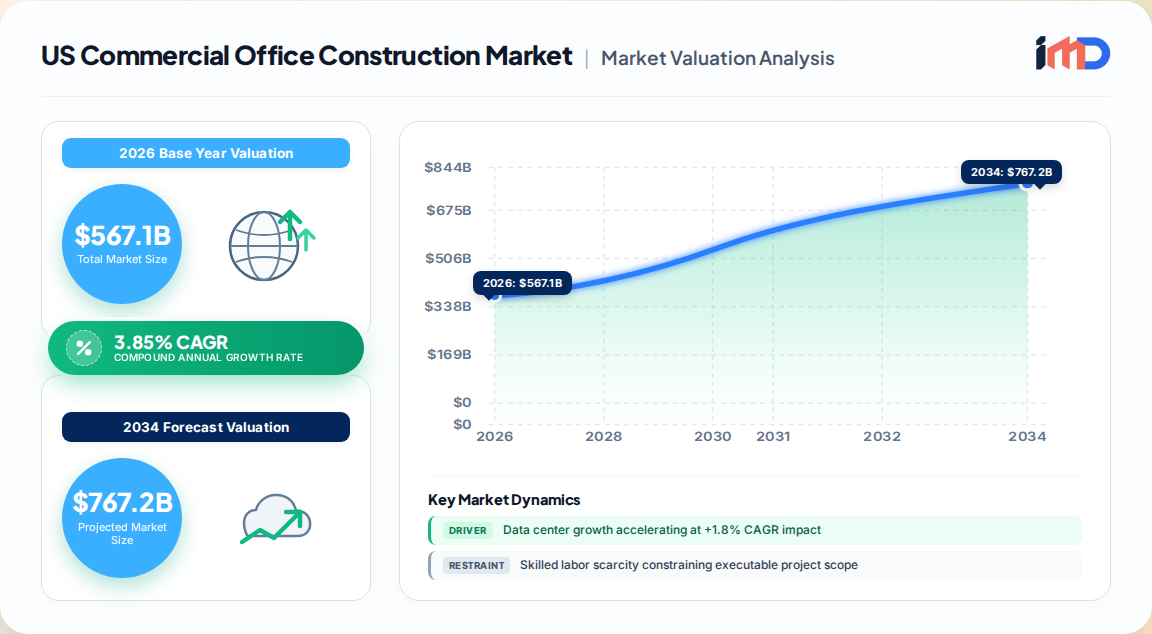
The US commercial construction market was valued at USD 567.1 billion in 2026 and is projected to reach USD 713.9 billion by 2032, expanding at a CAGR of 3.85% over 2027–2032. Office construction remains the single largest commercial sector, accounting for 34.99% of total market share in 2026.
US Commercial Office Construction Market Market Size (In Billion)
750.0B
600.0B
450.0B
300.0B
150.0B
0
546.1 B
2025
567.1 B
2026
588.9 B
2027
611.6 B
2028
635.2 B
2029
659.6 B
2030
685.0 B
2031
Our proprietary modeling indicates that office project revenue continues to rise even as core occupancy demand stays soft — a divergence that defines the current cycle.
Office building construction value advanced at a 4.3% CAGR from 2021 to 2025.
New office construction costs climbed 48.1% between January 2021 and April 2026.
Office vacancy remained elevated at 17.8% in March 2026, down from the 20.1% peak in Q2 2024.
This cost-driven revenue inflation, rather than a genuine recovery in new-build office demand, is the central analytical distinction buyers of this market must internalize.
Metric
2026
2027
2032
CAGR (2027–2032)
Commercial construction market
USD 567.1 Bn
USD 591.0 Bn
USD 713.9 Bn
3.85%
Office sector share
34.99%
—
—
—
New construction share
67.81%
—
—
—
Private investment share
85%
—
—
—
Market concentration
Medium
—
—
—
Segment Dynamics: Office vs. the Broader Commercial Mix
Office leads, but the growth center of gravity has shifted. Industrial and logistics is the fastest-growing sector at 5.1% CAGR, driven by e-commerce fulfillment build-outs. Renovation is the fastest-growing construction type at 4.85% CAGR, and public investment is the fastest-growing funding source at 5.25% CAGR.
Segment Parent
Leading Sub-Segment
Fastest-Growing Sub-Segment
Growth Rate
Commercial sector type
Office (34.99%)
Industrial & logistics
5.1%
Construction type
New construction (67.81%)
Renovation
4.85%
Investment source
Private (85%)
Public
5.25%
Geography
Texas (17.03%)
Florida
5.1%
For office specifically, the renovation segment carries outsized strategic importance: owners are converting functionally obsolete stock into "Premier Class A" inventory — buildings built or extensively renovated within the past decade.
Driver Impact Analysis
Our primary interviews with general contractors and developers quantify the following drivers as incremental contributions to sector CAGR.
Driver
Impact on CAGR
Geography
Timeline
Data center growth (AI, cloud, edge)
+1.8%
Nationwide
2–4 years
E-commerce warehouse/fulfillment build-outs
+1.35%
Nationwide
2–4 years
Office retrofit for hybrid-ready workplaces
+1.2%
Northern/Central New Jersey
2–4 years
Hospitality and mixed-use recovery
+1.05%
Nationwide
≤2 years
Public transit and civic investment
+0.75%
Greater Washington
≥4 years
Green-building and ESG certification
+0.55%
New York City
≥4 years
Private US data-center building construction hit a record USD 84.95 billion seasonally adjusted annualized pace in August 2026, up over 73% year over year. This is now a direct competitor for contractor capacity, labor, and MEP talent that would otherwise serve office projects.
Restraints, Challenges & Cost Structure
The principal constraint is not demand — it is executable capacity.
Skilled labor scarcity limits the volume of office work firms can staff, bid, and deliver on schedule.
Input price inflation (new office costs up 48.1% since January 2021) compresses developer feasibility at current financing costs.
Quality-gap bifurcation: 17.8% vacancy coexists with undersupply of Premier Class A space, stranding capital in non-competitive assets.
Interest-rate sensitivity on construction financing continues to gate marginal ground-up office starts.
Growth therefore accrues disproportionately to contractors able to price and staff phased scopes anchored to clearly defined occupier requirements, while poorly anchored speculative projects remain unfinanceable.
Regional Outlook: Office Construction Geography
Texas leads with a 17.03% share of 2026 market value, followed by California, Florida, New York, and Illinois. Florida is the fastest-growing geography at 5.1% CAGR, supported by in-migration, hospitality-linked mixed-use, and corporate relocation activity.
US Commercial Office Construction Market Regional Market Share
Loading chart...
Texas: Houston and Austin data-center and corporate campus activity; lowest regulatory friction.
Florida: Fastest-growing; mixed-use hospitality redevelopment (e.g., a 108,000 sq ft, 75-key hotel with ground-floor retail broke ground in Frisco, Colorado's mountain corridor) and coastal office repositioning.
New York: Highest green-building and ESG premium; retrofit-dominated office pipeline.
California and Illinois: Technology and professional-services tenancy; renovation-led rather than net-new office supply.
Value Chain and Delivery Models
Office delivery spans design-bid-build, design-build, construction management at risk, and integrated project delivery. Flexible frameworks are gaining share as projects grow more integrated and multi-use, compressing timelines and improving stakeholder alignment.
Design and preconstruction: BIM clash detection reduces rework by up to 15%.
Structural and envelope trades: Steel is the fastest-growing material category; concrete remains the largest by volume.
MEP coordination: The decisive bottleneck for phased data-center and hybrid-ready office scopes.
Fit-out and handover: Phased commissioning enables staged tenant onboarding.
Consolidation in building-products distribution — including multi-billion-dollar distributor acquisitions in 2025 — is deepening regional supply coverage and improving cost certainty for office contractors.
Competitive Landscape & Strategic Priorities
Market concentration is medium. Leading contractors include Turner Construction Company, Clark Construction Group, DPR Construction, STO Building Group, The Whiting-Turner Contracting Company, Bechtel, Fluor Corporation, Skanska, Kiewit Corporation, Balfour Beatty, Jacobs Engineering Group, Tishman Realty & Construction, Lendlease, and Belfor USA Group.
Strategic imperatives we observe across the contractor set:
Build dedicated mission-critical and data-center delivery benches to capture the +1.8% CAGR driver.
Secure multi-year development partnerships to convert lumpy bid pipelines into backlog visibility (e.g., long-term technology-campus partnerships signed in 2026).
Deploy digital twin, IoT site monitoring, and prefabrication to offset labor scarcity — modular delivery has shortened timelines by up to 30% on some projects.
Position for public-investment adjacency in transit and civic zones, the fastest-growing funding channel at 5.25% CAGR.
Strategic Outlook 2027–2032
The US commercial office construction market will grow at a steady but capacity-constrained 3.85% CAGR to 2032. Expect revenue growth to remain decoupled from vacancy recovery, with value concentrated in renovation, data-center-adjacent infrastructure, and Premier Class A repositioning rather than speculative new-build office towers. Contractors with phased-delivery capability and ESG credentials — green-building project management clients report utility savings roughly twice those of conventional builds — will capture disproportionate margin.
US Commercial Office Construction Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
US Commercial Office Construction Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.85% from 2020-2034
Segmentation
By Commercial Sector Type
Office
Industrial & Logistics
Retail
Others
By Construction Type
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Data center growth accelerating at +1.8% CAGR impact
3.1.2. E-commerce expansion fueling warehouse and fulfillment build-outs (+1.35%)
3.1.3. Office retrofit demand from hybrid workplace requirements (+1.2%)
3.1.4. Hospitality and mixed-use project recovery (+1.05%)
3.1.5. Public investment in transit and civic facilities (+0.75% CAGR, fastest-growing funding source at 5.25%)
3.2. Market Trends
3.2.1. Office retrofit and redevelopment toward Premier Class A hybrid-ready workplaces
3.2.2. Phased data-center construction for AI, cloud, and edge computing workloads
3.2.3. Mixed-use hospitality and retail-integrated commercial redevelopments
3.2.4. Prefabrication, modular delivery, and BIM-driven clash detection
3.2.5. Green-building and ESG-certified commercial design
3.4.2. Input and labor cost inflation compressing developer feasibility
3.4.3. Elevated office vacancy at 17.8% diluting new-build demand
3.4.4. Interest-rate sensitivity on construction financing
3.5. Market Challenges
3.5.1. Reconciling cost-inflated revenue growth with soft underlying office demand
3.5.2. Managing phased delivery and complex building interfaces for data centers
3.5.3. Mitigating material price volatility across structural and MEP scopes
3.5.4. Bridging the quality gap between obsolete and Premier Class A office stock
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Commercial Sector Type
5.1.1. Office
5.1.2. Industrial & Logistics
5.1.3. Retail
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Construction Type
5.2.1. New Construction
5.2.2. Renovation
5.3. Market Analysis, Insights and Forecast - by Investment Source
5.3.1. Private
5.3.2. Public
5.4. Market Analysis, Insights and Forecast - by Contract Type
5.4.1. Design-Bid-Build
5.4.2. Design-Build
5.4.3. Construction Management at Risk
5.5. Market Analysis, Insights and Forecast - by Materials Used
5.5.1. Concrete
5.5.2. Steel
5.5.3. Wood
5.5.4. Glass
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. United States
6. Competitive Analysis
6.1. Company Profiles
6.1.1. Turner Construction Company
6.1.1.1. Company Overview
6.1.1.2. Products
6.1.1.3. Company Financials
6.1.1.4. SWOT Analysis
6.1.2. Clark Construction Group
6.1.2.1. Company Overview
6.1.2.2. Products
6.1.2.3. Company Financials
6.1.2.4. SWOT Analysis
6.1.3. DPR Construction
6.1.3.1. Company Overview
6.1.3.2. Products
6.1.3.3. Company Financials
6.1.3.4. SWOT Analysis
6.1.4. STO Building Group
6.1.4.1. Company Overview
6.1.4.2. Products
6.1.4.3. Company Financials
6.1.4.4. SWOT Analysis
6.1.5. The Whiting-Turner Contracting Company
6.1.5.1. Company Overview
6.1.5.2. Products
6.1.5.3. Company Financials
6.1.5.4. SWOT Analysis
6.1.6. Bechtel
6.1.6.1. Company Overview
6.1.6.2. Products
6.1.6.3. Company Financials
6.1.6.4. SWOT Analysis
6.1.7. Fluor Corporation
6.1.7.1. Company Overview
6.1.7.2. Products
6.1.7.3. Company Financials
6.1.7.4. SWOT Analysis
6.1.8. Skanska
6.1.8.1. Company Overview
6.1.8.2. Products
6.1.8.3. Company Financials
6.1.8.4. SWOT Analysis
6.1.9. Kiewit Corporation
6.1.9.1. Company Overview
6.1.9.2. Products
6.1.9.3. Company Financials
6.1.9.4. SWOT Analysis
6.1.10. Balfour Beatty
6.1.10.1. Company Overview
6.1.10.2. Products
6.1.10.3. Company Financials
6.1.10.4. SWOT Analysis
6.1.11. Jacobs Engineering Group
6.1.11.1. Company Overview
6.1.11.2. Products
6.1.11.3. Company Financials
6.1.11.4. SWOT Analysis
6.1.12. Tishman Realty & Construction
6.1.12.1. Company Overview
6.1.12.2. Products
6.1.12.3. Company Financials
6.1.12.4. SWOT Analysis
6.1.13. Lendlease
6.1.13.1. Company Overview
6.1.13.2. Products
6.1.13.3. Company Financials
6.1.13.4. SWOT Analysis
6.1.14. Belfor USA Group
6.1.14.1. Company Overview
6.1.14.2. Products
6.1.14.3. Company Financials
6.1.14.4. SWOT Analysis
6.2. Market Entropy
6.2.1. Company's Key Areas Served
6.2.2. Recent Developments
6.3. Company Market Share Analysis, 2026
6.3.1. Top 5 Companies Market Share Analysis
6.3.2. Top 3 Companies Market Share Analysis
6.4. List of Potential Customers
List of Figures
Figure 1: Global US Commercial Office Construction Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: United States US Commercial Office Construction Market Revenue (Billion), by Commercial Sector Type 2026 & 2034
Figure 3: United States US Commercial Office Construction Market Revenue Share (%), by Commercial Sector Type 2026 & 2034
Figure 4: United States US Commercial Office Construction Market Revenue (Billion), by Construction Type 2026 & 2034
Figure 5: United States US Commercial Office Construction Market Revenue Share (%), by Construction Type 2026 & 2034
Figure 6: United States US Commercial Office Construction Market Revenue (Billion), by Investment Source 2026 & 2034
Figure 7: United States US Commercial Office Construction Market Revenue Share (%), by Investment Source 2026 & 2034
Figure 8: United States US Commercial Office Construction Market Revenue (Billion), by Contract Type 2026 & 2034
Figure 9: United States US Commercial Office Construction Market Revenue Share (%), by Contract Type 2026 & 2034
Figure 10: United States US Commercial Office Construction Market Revenue (Billion), by Materials Used 2026 & 2034
Figure 11: United States US Commercial Office Construction Market Revenue Share (%), by Materials Used 2026 & 2034
Figure 12: United States US Commercial Office Construction Market Revenue (Billion), by Country 2026 & 2034
Figure 13: United States US Commercial Office Construction Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global US Commercial Office Construction Market Revenue Billion Forecast, by Commercial Sector Type 2020 & 2034
Table 2: Global US Commercial Office Construction Market Revenue Billion Forecast, by Construction Type 2020 & 2034
Table 3: Global US Commercial Office Construction Market Revenue Billion Forecast, by Investment Source 2020 & 2034
Table 4: Global US Commercial Office Construction Market Revenue Billion Forecast, by Contract Type 2020 & 2034
Table 5: Global US Commercial Office Construction Market Revenue Billion Forecast, by Materials Used 2020 & 2034
Table 6: Global US Commercial Office Construction Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: United States US Commercial Office Construction Market Revenue Billion Forecast, by Commercial Sector Type 2020 & 2034
Table 8: United States US Commercial Office Construction Market Revenue Billion Forecast, by Construction Type 2020 & 2034
Table 9: United States US Commercial Office Construction Market Revenue Billion Forecast, by Investment Source 2020 & 2034
Table 10: United States US Commercial Office Construction Market Revenue Billion Forecast, by Contract Type 2020 & 2034
Table 11: United States US Commercial Office Construction Market Revenue Billion Forecast, by Materials Used 2020 & 2034
Table 12: United States US Commercial Office Construction Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Texas US Commercial Office Construction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: California US Commercial Office Construction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Florida US Commercial Office Construction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: New York US Commercial Office Construction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Illinois US Commercial Office Construction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Rest of US US Commercial Office Construction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1How big is the US commercial office construction market?
The US commercial construction market was valued at USD 567.1 billion in 2026, with office buildings accounting for 34.99% of that value. The overall market is forecast to reach USD 713.9 billion by 2032.
2What is the growth rate of the US commercial office construction market?
The broader US commercial construction market is forecast to grow at a 3.85% CAGR from 2027 to 2032. Within it, renovation is the fastest-growing construction type at 4.85% CAGR and industrial/logistics the fastest-growing sector at 5.1%.
3Why is office construction revenue rising while office vacancies remain high?
New office construction costs rose 48.1% from January 2021 to April 2026, so revenue growth reflects price inflation rather than volume recovery. Vacancy stood at 17.8% in March 2026 even as demand concentrated in Premier Class A buildings.
4Which region leads US commercial office construction?
Texas led with a 17.03% share of 2026 market value. Florida is the fastest-growing geography at a 5.1% CAGR through 2032.
5Who are the leading contractors in US commercial construction?
Turner Construction Company, Clark Construction Group, DPR Construction, STO Building Group, and The Whiting-Turner Contracting Company are among the major players, alongside Bechtel, Fluor, Skanska, and Kiewit.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is derived from primary intelligence, spanning structured interviews, bid-level cost validation, and contractor backlog verification across the US commercial office construction value chain.
Company types surveyed: general contractors and construction managers, design-build and integrated project delivery firms, commercial real estate developers and owner-representatives, MEP and structural subcontractors, and building-products distributors and suppliers.
Stakeholder roles interviewed: Vice President of Preconstruction, Director of Project Delivery, Chief Development Officer, and Head of Procurement and Supply Chain.
Trade association and regulatory bodies consulted: the Associated General Contractors of America (AGC), the American Institute of Architects (AIA), the U.S. Green Building Council (USGBC), and OSHA for compliance-cost inputs.
Bottom-up quantification relies on square footage under construction and permit issuance, verified contract value per square foot by metro, office vacancy and absorption rates, and backlog-to-billings ratios submitted by surveyed contractors.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Vice President of Preconstruction
30%
Director of Project Delivery
28%
Chief Development Officer
24%
Head of Procurement & Supply Chain
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
General Contractors & Construction Managers
38%
Design-Build & Integrated Delivery Firms
18%
Developers & Owner-Representatives
20%
MEP & Structural Subcontractors
14%
Building-Products Distributors & Suppliers
10%
Secondary Research & Industry Benchmarking
20–30% of research effort draws on audited public benchmarks, including U.S. Census Bureau construction spending series (census.gov), U.S. Bureau of Labor Statistics producer and employment data (bls.gov), and Federal Reserve interest-rate and credit conditions.
Financial and ownership data are cross-validated against Bloomberg, Factiva, Hoovers, and PitchBook for contractor revenue, M&A, and capital structure.
Official multilateral and non-profit sources only — no commercial research portals are referenced.
All report datasets and forecasts are updated to the date of purchase, with rolling refresh of permit, cost, and vacancy series.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously and reconciled through multi-level data triangulation: national spend, metro-level permit value, and company-level backlog are cross-checked for convergence.
Top-down validation uses the office sector's 34.99% share of the USD 567.1 billion 2026 commercial construction base.
Bottom-up build-up aggregates project-level scope by sector, construction type (new vs. renovation), and investment source (private 85% / public 15%).
Scenario modeling applies driver impact coefficients — such as +1.8% CAGR from data-center growth and +1.2% from office retrofit — to derive 2027–2032 trajectories.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through consistent-response filtering and outlier trimming in survey samples.
Every market size figure undergoes three-way triangulation across primary interviews, official government statistics, and contractor financial disclosures.
Segment shares are re-verified quarterly against permit and spending releases; material deviations trigger model recalibration.
Final figures are reviewed by senior analysts for internal consistency across geography, sector, and investment-source dimensions before publication.
Independent Intelligence for decisions that move markets
The global residential real estate market is valued at USD 11.6 trillion in 2026 and is projected to reach USD 15.53 trillion by 2031, growing at a 6.05% CAGR.
Nov 2026|243 pages
$2900.00
Post-construction cleaning demand patterns: a $24.6B niche growing at 7.4% CAGR to 2035, driven by handover cycles, green certification and labor shifts.
Nov 2026|241 pages
$2900.00
India construction equipment market at $9.98B in 2027 to reach $14.46B by 2032, CAGR 7.70%. Earthmoving leads; electric/hybrid fastest-growing.
Nov 2026|255 pages
$2900.00
Home elevator installation service market to reach $6.5B by 2036 at 5.5% CAGR, driven by retrofit demand and aging population trends.