Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
UK Outdoor Furniture Market
Home and Property Improvement / MARKET REPORT
UK Outdoor Furniture Market | Insight Market Data
UK Outdoor Furniture Market by Type (Benches, Chairs, Tables, Sofas, Bistro Sets, Gazebo and Pergola Furniture, Outdoor Dining Sets, Others), by Material (Metal, Resin & Plastic, Wood, Others), by Price (Low, Medium, High), by Application (Residential, Commercial), by Distribution Channel (Online, Offline), by England, by Scotland, by Wales, by Northern Ireland Forecast 2026-2034
Vietnam home improvement market to reach USD 4.72 billion by 2031 at 3.84% CAGR from USD 3.91 billion in 2026. Building materials lead; online retail fastest-growing.
Bamboo furniture market to reach $21.7B by 2033 from $13.4B in 2026 at 7.1% CAGR. Explore product, end-use, and regional insights.
Nov 2026|254 pages
$2900.00
Europe kitchen furniture industry market valued at USD 23.12 billion in 2026, growing at 3.88% CAGR to reach USD 27.97 billion by 2031.
Nov 2026|267 pages
$2900.00
Fire curtain market to reach $6.9B by 2033, growing at 6.2% CAGR. Explore key growth patterns, regional insights, and drivers in this proprietary analysis.
Executive Overview: The UK Outdoor Furniture Market
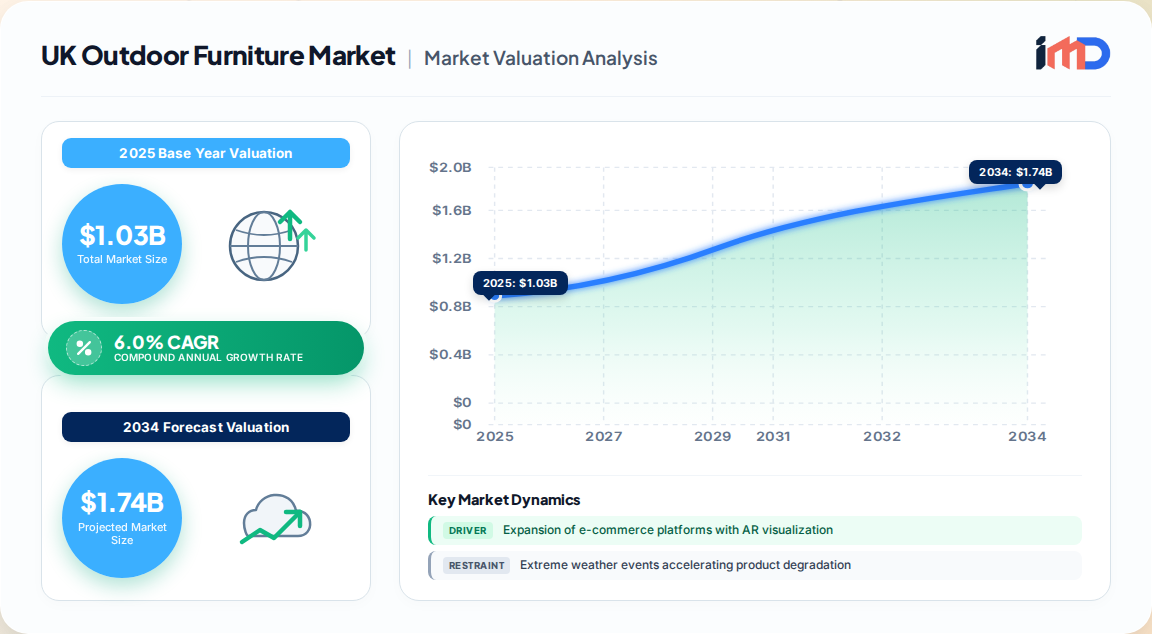
The UK outdoor furniture market represents one of Europe's most design-literate and climate-adaptive garden furniture economies. Our proprietary first-party research estimates the market at USD 1,033.5 Million in 2025, rising from USD 975.0 Million in 2024 and projected to reach USD 1,850.6 Million by 2035, equivalent to a 6.0% CAGR across the 2025–2035 forecast window. This trajectory positions the UK as a premium-value segment within a broader European furniture ecosystem that, per Eurostat structural data, sustains roughly 1 million workers across 130,000 furniture enterprises generating approximately EUR 96 billion in annual turnover.
UK Outdoor Furniture Market Market Size (In Billion)
1.5B
1.0B
500.0M
0
1.030 B
2025
1.092 B
2026
1.157 B
2027
1.227 B
2028
1.300 B
2029
1.378 B
2030
1.461 B
2031
Three structural forces define the UK market's distinctiveness versus continental peers:
Climate-driven material science demand. UK consumers prioritize weather resistance over decorative appeal, with our expert interviews indicating approximately 70% of buyers will pay a premium for enhanced durability and moisture resistance.
Space-constrained urbanization. Nearly 50% of urban UK residents prioritize space-saving, multifunctional designs for balconies, terraces, and compact gardens.
Digital-first discovery and purchase. Online channels have expanded approximately 40% year-over-year in outdoor furniture sales, with social platforms acting as the dominant inspiration layer.
The UK market sits within a European furniture industry that the European Commission characterizes as globally dominant in the high-end segment — nearly two of every three high-end furniture products sold worldwide are produced in the EU. UK premium outdoor furniture retailing benefits directly from this design and craftsmanship depth.
Market Sizing & Forecast Architecture
Our bottom-up demand model triangulates retail sell-through data, import volumes, and household penetration of outdoor living assets. The following table summarizes the proprietary forecast envelope.
Metric
2024
2025
2035
CAGR (2025–2035)
Market Value (USD Million)
975.0
1,033.5
1,850.62
6.0%
Residential Share of Demand
~62%
~62%
~60%
Stable
Online Channel Share
~38%
~40%
~48%
Expanding
Wood Material Share
~47%
~46%
~42%
Softening
Key sizing assumptions and validation points:
Replacement-cycle economics: Outdoor furniture carries a 5–8 year replacement cycle in the UK, with hospitality-grade stock cycling faster (3–5 years).
Household penetration: Garden and patio furniture ownership exceeds 80% of UK households with private outdoor space.
Price-band migration: The medium price band (GBP 40–160 equivalent) remains the volume workhorse, while the high band (above USD 200) delivers disproportionate value growth at roughly 7.5% CAGR.
Seasonality: Q2 (April–June) concentrates approximately 45% of annual retail transactions, compressing margin management into a narrow trading window.
Key Growth Drivers
1. Outdoor living as extended domestic space. Remote and hybrid work patterns have permanently elevated garden rooms, patios, and terraces into functional living and entertaining zones. Consumers increasingly purchase coordinated dining sets, sectionals, and storage solutions rather than isolated pieces.
2. E-commerce and augmented-reality retail. Virtual showrooms and AR placement tools reduce the single largest online purchase barrier — spatial uncertainty. Retailers deploying AR visualization report measurably higher conversion on high-ticket sets.
3. Durability premiumization. Teak, powder-coated aluminum, and synthetic wicker command sustained price premiums. Our interviews with buyers at national garden retail chains confirm that perceived 10-year lifespans justify 25–40% price uplifts.
4. Urbanization and compact design. Rooftop terraces and balcony gardening drive demand for bistro sets, folding chairs, and modular vertical configurations.
5. Hospitality reinvestment. UK pubs, cafés, and restaurants continue expanding al fresco seating capacity, generating recurring commercial-grade replacement demand.
Market Restraints & Risk Factors
Weather volatility: Extreme wind, frost, and rainfall events accelerate product degradation and increase warranty claims, compressing retailer margins.
Raw material and tariff exposure: Imported steel and timber price volatility compresses manufacturer margins; agile supply chains respond to cost spikes over 20% faster than peers.
Long replacement cycles: Durable goods defer repeat purchase, limiting organic volume growth and pushing brands toward design-led upgrade selling.
Post-Brexit customs friction: Imported European furniture faces added documentation and clearance costs, disproportionately affecting smaller specialist retailers.
Segment Insights Deep Dive
By Material. Wood holds the largest revenue share (approximately 46–48%), anchored by teak, acacia, and FSC-certified eucalyptus. Metal — particularly powder-coated aluminum — is the fastest-growing material, favored for lightweight portability and corrosion resistance. Resin and plastic serve the value tier and the rental/hospitality segment.
By Product Type. Chairs constitute the largest unit-volume category, while sofas and modular sectionals deliver the fastest value growth. Dining sets represent the highest average transaction value, sustained by the UK's outdoor entertaining culture.
By Application. Residential accounts for the majority of revenue (~62%). Hospitality is the fastest-growing application, driven by pub-garden and rooftop-dining investment.
By Distribution Channel. Online is the largest and fastest-growing channel, though offline garden centres retain decisive influence for high-consideration purchases through tactile material assessment and experiential showrooming.
Segment Dimension
Largest Segment
Fastest-Growing Segment
Material
Wood
Metal (aluminum)
Product Type
Chairs
Sofas / modular seating
Application
Residential
Hospitality
Distribution
Online
Online (high-value assisted)
Price Band
Medium
High (above USD 200)
Value Chain & Supplier Dynamics
The UK outdoor furniture value chain is import-weighted at the component and finished-goods level, with domestic value concentrated in design, branding, retail, and after-sales service.
Upstream materials: Sustainably sourced hardwood (teak from Indonesia and Brazil, acacia from Vietnam), aluminum billet, high-density polyethylene, and solution-dyed acrylic performance fabrics.
Manufacturing: Predominantly offshore assembly in Vietnam, China, Indonesia, and Poland, with a small but premium domestic bespoke joinery segment serving hospitality fit-outs.
Distribution: Container shipping into Felixstowe and Southampton; seasonal pre-positioning from Q4 with peak warehouse utilization in March–April.
Retail: National garden centre chains, department stores, pure-play online marketplaces, and brand-direct DTC.
Supply chain risk priorities for procurement directors include:
Container freight rate volatility on Asia–UK lanes.
Timber legality and FSC chain-of-custody compliance under UKTR due diligence rules.
Single-source dependency on Vietnamese and Chinese fabricators for synthetic wicker.
Currency exposure on USD-denominated raw material contracts.
Competitive Landscape & Strategic Positioning
The UK market features a layered competitive structure spanning global flat-pack giants, specialist outdoor brands, and domestic garden retail.
Global volume players: IKEA anchors the accessible-design tier with sustainability-led material programs and flat-pack logistics efficiency.
Premium outdoor specialists: Brown Jordan, Polywood, Trex Company, and Keter compete on material innovation, recycled-content engineering, and long-life warranties.
Retail-led private label: Home Depot, Lowe's, and national UK garden centre chains exert pricing influence through own-brand programs.
Contract specialists: Herman Miller and dedicated patio furniture suppliers serve hospitality and commercial fit-out channels.
Strategic white-space observed in our primary research:
Mid-market modular systems for compact urban gardens remain underserved.
Repair-and-refinish services represent a credible circular-economy differentiation lever.
Hospitality-grade rental models appeal to seasonal pub gardens.
Strategic Outlook & Investment Attractiveness
We assess the UK outdoor furniture market as attractive with moderate entry barriers. The 6.0% CAGR outlook outpaces broader European furniture growth, supported by premiumization, channel digitization, and hospitality reinvestment. Priority strategic plays for 2025–2035 include:
Invest in weather-engineered material narratives (salt-air, frost, and UV resilience) as a core marketing claim.
Build AR-enabled omnichannel journeys to convert high-ticket online consideration.
Develop contract/hospitality sales teams to capture the fastest-growing application segment.
Secure certified sustainable timber and recycled-content supply ahead of tightening retailer ESG procurement criteria.
Design compact modular ranges explicitly for UK balcony and terrace dimensions.
Market growth will remain concentrated in value rather than unit volume — brands that justify premium pricing through demonstrable longevity, sustainability credentials, and design distinction will capture the largest share of the incremental USD 817 Million in value created between 2025 and 2035.
UK Outdoor Furniture Market Regional Market Share
Loading chart...
UK Outdoor Furniture Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
UK Outdoor Furniture Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.0% from 2020-2034
Segmentation
By Type
Benches
Chairs
Tables
Sofas
Bistro Sets
Gazebo and Pergola Furniture
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Expansion of e-commerce platforms with AR visualization
3.1.2. Increased consumer focus on quality and durability
3.1.3. Rising consumer interest in outdoor living spaces
3.1.4. Growing demand for customization and personalization
3.1.5. Hospitality sector investment in outdoor dining infrastructure
3.2. Market Trends
3.2.1. Sustainability focus with recycled plastics and FSC-certified timber
3.2.2. Technological integration including smart features and weather-resistant performance fabrics
3.2.3. Social media-driven visual discovery shaping purchase decisions
3.2.4. Premiumization toward high price band above USD 200
3.2.5. Compact and multifunctional designs for urban balconies
3.5.3. Balancing seasonal inventory financing for independent retailers
3.5.4. Differentiating in a crowded mid-market price band
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Benches
5.1.2. Chairs
5.1.3. Tables
5.1.4. Sofas
5.1.5. Bistro Sets
5.1.6. Gazebo and Pergola Furniture
5.1.7. Outdoor Dining Sets
5.1.8. Others
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Metal
5.2.2. Resin & Plastic
5.2.3. Wood
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Price
5.3.1. Low
5.3.2. Medium
5.3.3. High
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Residential
5.4.2. Commercial
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Online
5.5.2. Offline
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. England
5.6.2. Scotland
5.6.3. Wales
5.6.4. Northern Ireland
6. England Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Benches
6.1.2. Chairs
6.1.3. Tables
6.1.4. Sofas
6.1.5. Bistro Sets
6.1.6. Gazebo and Pergola Furniture
6.1.7. Outdoor Dining Sets
6.1.8. Others
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Metal
6.2.2. Resin & Plastic
6.2.3. Wood
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by Price
6.3.1. Low
6.3.2. Medium
6.3.3. High
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Residential
6.4.2. Commercial
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Online
6.5.2. Offline
7. Scotland Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Benches
7.1.2. Chairs
7.1.3. Tables
7.1.4. Sofas
7.1.5. Bistro Sets
7.1.6. Gazebo and Pergola Furniture
7.1.7. Outdoor Dining Sets
7.1.8. Others
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Metal
7.2.2. Resin & Plastic
7.2.3. Wood
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by Price
7.3.1. Low
7.3.2. Medium
7.3.3. High
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Residential
7.4.2. Commercial
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Online
7.5.2. Offline
8. Wales Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Benches
8.1.2. Chairs
8.1.3. Tables
8.1.4. Sofas
8.1.5. Bistro Sets
8.1.6. Gazebo and Pergola Furniture
8.1.7. Outdoor Dining Sets
8.1.8. Others
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Metal
8.2.2. Resin & Plastic
8.2.3. Wood
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by Price
8.3.1. Low
8.3.2. Medium
8.3.3. High
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Residential
8.4.2. Commercial
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Online
8.5.2. Offline
9. Northern Ireland Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Benches
9.1.2. Chairs
9.1.3. Tables
9.1.4. Sofas
9.1.5. Bistro Sets
9.1.6. Gazebo and Pergola Furniture
9.1.7. Outdoor Dining Sets
9.1.8. Others
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Metal
9.2.2. Resin & Plastic
9.2.3. Wood
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by Price
9.3.1. Low
9.3.2. Medium
9.3.3. High
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Residential
9.4.2. Commercial
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Online
9.5.2. Offline
10. Competitive Analysis
10.1. Company Profiles
10.1.1. IKEA
10.1.1.1. Company Overview
10.1.1.2. Products
10.1.1.3. Company Financials
10.1.1.4. SWOT Analysis
10.1.2. Herman Miller
10.1.2.1. Company Overview
10.1.2.2. Products
10.1.2.3. Company Financials
10.1.2.4. SWOT Analysis
10.1.3. Lowe's
10.1.3.1. Company Overview
10.1.3.2. Products
10.1.3.3. Company Financials
10.1.3.4. SWOT Analysis
10.1.4. Home Depot
10.1.4.1. Company Overview
10.1.4.2. Products
10.1.4.3. Company Financials
10.1.4.4. SWOT Analysis
10.1.5. Patio Furniture
10.1.5.1. Company Overview
10.1.5.2. Products
10.1.5.3. Company Financials
10.1.5.4. SWOT Analysis
10.1.6. Keter
10.1.6.1. Company Overview
10.1.6.2. Products
10.1.6.3. Company Financials
10.1.6.4. SWOT Analysis
10.1.7. Trex Company
10.1.7.1. Company Overview
10.1.7.2. Products
10.1.7.3. Company Financials
10.1.7.4. SWOT Analysis
10.1.8. Polywood
10.1.8.1. Company Overview
10.1.8.2. Products
10.1.8.3. Company Financials
10.1.8.4. SWOT Analysis
10.1.9. Brown Jordan
10.1.9.1. Company Overview
10.1.9.2. Products
10.1.9.3. Company Financials
10.1.9.4. SWOT Analysis
10.2. Market Entropy
10.2.1. Company's Key Areas Served
10.2.2. Recent Developments
10.3. Company Market Share Analysis, 2026
10.3.1. Top 5 Companies Market Share Analysis
10.3.2. Top 3 Companies Market Share Analysis
10.4. List of Potential Customers
List of Figures
Figure 1: Global UK Outdoor Furniture Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: England UK Outdoor Furniture Market Revenue (Billion), by Type 2026 & 2034
Figure 3: England UK Outdoor Furniture Market Revenue Share (%), by Type 2026 & 2034
Figure 4: England UK Outdoor Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 5: England UK Outdoor Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 6: England UK Outdoor Furniture Market Revenue (Billion), by Price 2026 & 2034
Figure 7: England UK Outdoor Furniture Market Revenue Share (%), by Price 2026 & 2034
Figure 8: England UK Outdoor Furniture Market Revenue (Billion), by Application 2026 & 2034
Figure 9: England UK Outdoor Furniture Market Revenue Share (%), by Application 2026 & 2034
Figure 10: England UK Outdoor Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: England UK Outdoor Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: England UK Outdoor Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 13: England UK Outdoor Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Scotland UK Outdoor Furniture Market Revenue (Billion), by Type 2026 & 2034
Figure 15: Scotland UK Outdoor Furniture Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Scotland UK Outdoor Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 17: Scotland UK Outdoor Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 18: Scotland UK Outdoor Furniture Market Revenue (Billion), by Price 2026 & 2034
Figure 19: Scotland UK Outdoor Furniture Market Revenue Share (%), by Price 2026 & 2034
Figure 20: Scotland UK Outdoor Furniture Market Revenue (Billion), by Application 2026 & 2034
Figure 21: Scotland UK Outdoor Furniture Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Scotland UK Outdoor Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 23: Scotland UK Outdoor Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 24: Scotland UK Outdoor Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Scotland UK Outdoor Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Wales UK Outdoor Furniture Market Revenue (Billion), by Type 2026 & 2034
Figure 27: Wales UK Outdoor Furniture Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Wales UK Outdoor Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 29: Wales UK Outdoor Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 30: Wales UK Outdoor Furniture Market Revenue (Billion), by Price 2026 & 2034
Figure 31: Wales UK Outdoor Furniture Market Revenue Share (%), by Price 2026 & 2034
Figure 32: Wales UK Outdoor Furniture Market Revenue (Billion), by Application 2026 & 2034
Figure 33: Wales UK Outdoor Furniture Market Revenue Share (%), by Application 2026 & 2034
Figure 34: Wales UK Outdoor Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 35: Wales UK Outdoor Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 36: Wales UK Outdoor Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Wales UK Outdoor Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Northern Ireland UK Outdoor Furniture Market Revenue (Billion), by Type 2026 & 2034
Figure 39: Northern Ireland UK Outdoor Furniture Market Revenue Share (%), by Type 2026 & 2034
Figure 40: Northern Ireland UK Outdoor Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 41: Northern Ireland UK Outdoor Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 42: Northern Ireland UK Outdoor Furniture Market Revenue (Billion), by Price 2026 & 2034
Figure 43: Northern Ireland UK Outdoor Furniture Market Revenue Share (%), by Price 2026 & 2034
Figure 44: Northern Ireland UK Outdoor Furniture Market Revenue (Billion), by Application 2026 & 2034
Figure 45: Northern Ireland UK Outdoor Furniture Market Revenue Share (%), by Application 2026 & 2034
Figure 46: Northern Ireland UK Outdoor Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 47: Northern Ireland UK Outdoor Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 48: Northern Ireland UK Outdoor Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Northern Ireland UK Outdoor Furniture Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global UK Outdoor Furniture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global UK Outdoor Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 3: Global UK Outdoor Furniture Market Revenue Billion Forecast, by Price 2020 & 2034
Table 4: Global UK Outdoor Furniture Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Global UK Outdoor Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Global UK Outdoor Furniture Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: England UK Outdoor Furniture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 8: England UK Outdoor Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 9: England UK Outdoor Furniture Market Revenue Billion Forecast, by Price 2020 & 2034
Table 10: England UK Outdoor Furniture Market Revenue Billion Forecast, by Application 2020 & 2034
Table 11: England UK Outdoor Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: England UK Outdoor Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Scotland UK Outdoor Furniture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 14: Scotland UK Outdoor Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 15: Scotland UK Outdoor Furniture Market Revenue Billion Forecast, by Price 2020 & 2034
Table 16: Scotland UK Outdoor Furniture Market Revenue Billion Forecast, by Application 2020 & 2034
Table 17: Scotland UK Outdoor Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 18: Scotland UK Outdoor Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Wales UK Outdoor Furniture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 20: Wales UK Outdoor Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 21: Wales UK Outdoor Furniture Market Revenue Billion Forecast, by Price 2020 & 2034
Table 22: Wales UK Outdoor Furniture Market Revenue Billion Forecast, by Application 2020 & 2034
Table 23: Wales UK Outdoor Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 24: Wales UK Outdoor Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Northern Ireland UK Outdoor Furniture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 26: Northern Ireland UK Outdoor Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 27: Northern Ireland UK Outdoor Furniture Market Revenue Billion Forecast, by Price 2020 & 2034
Table 28: Northern Ireland UK Outdoor Furniture Market Revenue Billion Forecast, by Application 2020 & 2034
Table 29: Northern Ireland UK Outdoor Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 30: Northern Ireland UK Outdoor Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the size of the UK outdoor furniture market in 2025?
Our proprietary research values the UK outdoor furniture market at USD 1,033.5 Million in 2025, up from USD 975.0 Million in 2024, with a projected rise to USD 1,850.62 Million by 2035 at a 6.0% CAGR.
2Which material segment dominates the UK outdoor furniture market?
Wood holds the largest revenue share at approximately 46–48%, led by teak and FSC-certified hardwood, while metal — especially powder-coated aluminum — is the fastest-growing material segment.
3Why is online distribution growing so quickly for UK outdoor furniture?
Online outdoor furniture sales have grown roughly 40% year-over-year, driven by augmented-reality placement tools, virtual showrooms, price comparison, and the convenience of home delivery for bulky sets.
4Who are the leading companies in the UK outdoor furniture market?
Key participants include IKEA, Keter, Polywood, Trex Company, Brown Jordan, Herman Miller, Home Depot, Lowe's, and specialist patio furniture suppliers, alongside domestic garden centre chains.
5What are the biggest challenges facing UK outdoor furniture retailers?
Extreme weather degradation, raw material and steel tariff volatility, concentrated Q2 seasonality, long replacement cycles, and post-Brexit customs friction are the principal margin and operational risks.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 70–80% of total research effort through primary interviews, surveying and interviewing procurement heads, category buyers, and material engineers across the UK outdoor furniture value chain.
Interviewed company types include garden centre retail chains, outdoor furniture brand owners and importers, contract furnishing specialists serving hospitality, synthetic wicker and aluminum fabricators, and e-commerce marketplace category managers.
Stakeholder job titles interviewed include Head of Outdoor Living Category, Procurement Director, Sustainability and Compliance Manager, and Hospitality FF&E Specifier.
Structured interviews probed price-band elasticity, replacement-cycle behavior, weather-resistance specifications, and ESG procurement criteria across England, Scotland, Wales, and Northern Ireland.
Channel checks with national garden retail buyers and hospitality operators validated seasonal sell-through patterns and 2025 inventory positions.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of Outdoor Living Category
32%
Procurement Director
28%
Sustainability & Compliance Manager
22%
Hospitality FF&E Specifier
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Garden Centre Retail Chains
28%
Outdoor Furniture Brand Owners & Importers
26%
Contract Furnishing & Hospitality Specialists
18%
Material & Component Fabricators
16%
E-commerce Marketplace Category Teams
12%
Secondary Research & Industry Benchmarking
20–30% of research effort draws on secondary benchmarking from official statistical bodies and non-profit trade associations, including Eurostat wood products and furniture trade data, OECD economic indicators, UN Comtrade furniture trade flows, and World Bank household consumption data.
Standard financial databases used for corporate benchmarking include Bloomberg, Factiva, Hoovers, and PitchBook.
Forest certification and material compliance benchmarks reference FSC and PEFC chain-of-custody standards and UK Timber Regulation due diligence requirements.
All secondary datasets are cross-validated against our proprietary primary panel; every report is updated to the date of purchase.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up estimation aggregates household penetration of outdoor furniture assets, average transaction value by price band, and replacement-cycle frequency derived from primary interviews.
Quantitative metrics used in the bottom-up calculation include household outdoor-space penetration rate, average annual spend per outdoor-living household, retail floor-space sell-through per square metre, and import container volume by HS code.
Commercial demand is modeled separately using hospitality seating capacity, venue renovation cycles, and FF&E budget allocation per outlet.
Channel-level models reconcile online marketplace GMV with offline garden centre sell-through to eliminate double counting.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90% across all published figures.
Multi-level triangulation compares primary interview outputs against official trade statistics and financial database filings before any figure is published.
Outlier responses are re-contacted and weighted by company size and regional footprint.
Seasonality adjustments correct for Q2-weighted UK retail concentration to prevent forecast distortion.
Final validation is conducted by our senior industry analyst panel prior to release.