Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
Europe Kitchen Furniture Industry | Insight Market Data
Europe Kitchen Furniture Industry by Product (Kitchen Cabinets, Kitchen Chairs, Others), by Material (Wood, Metal, Plastic & Polymer, Other Materials), by End-User (Residential, Commercial), by Distribution Channel (B2C Retail, B2B Project), by Germany, by United Kingdom, by France, by Spain, by Italy, by BENELUX, by NORDICS, by Rest of Europe Forecast 2026-2034
Vietnam home improvement market to reach USD 4.72 billion by 2031 at 3.84% CAGR from USD 3.91 billion in 2026. Building materials lead; online retail fastest-growing.
UK outdoor furniture market valued at $1.03 Billion in 2025, growing at 6% CAGR to $1.85 Billion by 2035, driven by sustainable and smart garden furniture.
Nov 2026|198 pages
$2900.00
Bamboo furniture market to reach $21.7B by 2033 from $13.4B in 2026 at 7.1% CAGR. Explore product, end-use, and regional insights.
Nov 2026|254 pages
$2900.00
Fire curtain market to reach $6.9B by 2033, growing at 6.2% CAGR. Explore key growth patterns, regional insights, and drivers in this proprietary analysis.
Executive Overview: Europe Kitchen Furniture Industry Market
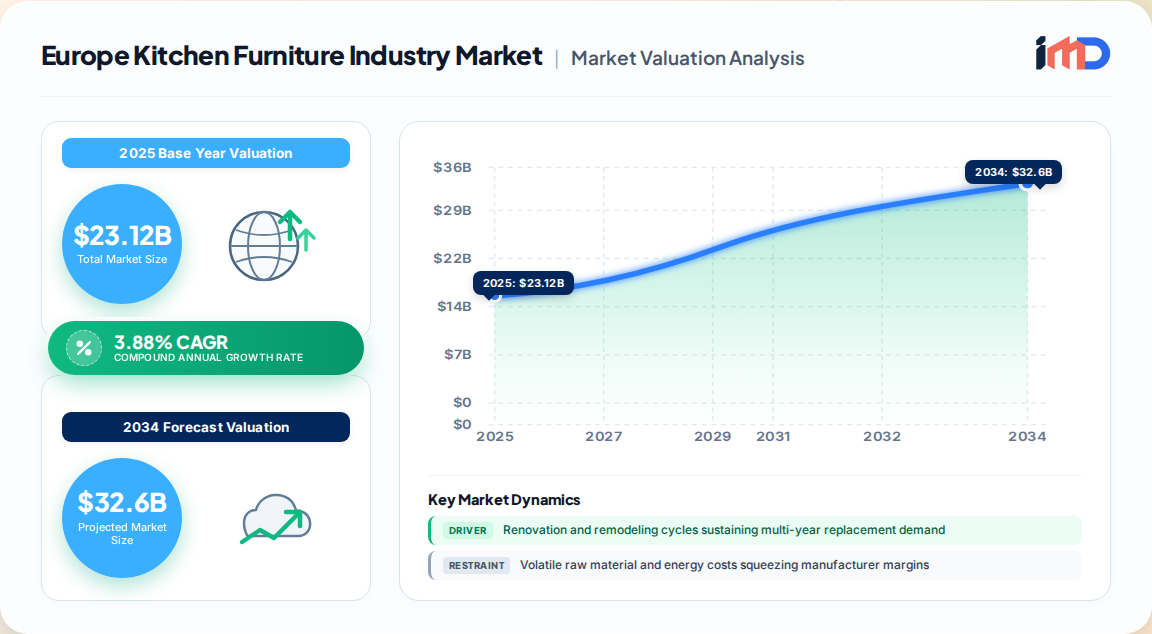
The Europe kitchen furniture industry market reached USD 21.96 billion in 2025 and is estimated at USD 23.12 billion in 2026. Our proprietary demand model projects the market to expand to USD 27.97 billion by 2031, registering a CAGR of 3.88% over the forecast period (2026–2031). This growth is anchored by renovation-driven replacement cycles, compliance-led retrofit activity, and a structural shift toward modular, space-efficient cabinetry across Western and Northern Europe.
Europe Kitchen Furniture Industry Market Size (In Billion)
30.0B
20.0B
10.0B
0
23.12 B
2025
24.02 B
2026
24.95 B
2027
25.92 B
2028
26.92 B
2029
27.97 B
2030
29.05 B
2031
Market concentration remains low, with the top five manufacturers holding an estimated 22.5% combined share when benchmarked against broader European wooden furniture trade flows. The competitive field is populated by vertically integrated German and French cabinetry specialists, Nordic flat-pack giants, and a long tail of regional joinery firms.
Base year (2025): USD 21.96 billion
Forecast year (2026): USD 23.12 billion
Forecast year (2031): USD 27.97 billion
CAGR (2026–2031): 3.88%
Largest country market (2025): Germany (16.34% share)
Fastest-growing country: France (4.62% CAGR through 2031)
Market Drivers and Restraints
Key Growth Drivers
Renovation and remodeling cycles sustain multi-year replacement demand, contributing an estimated +1.8% to the CAGR. Europe's aging housing stock keeps kitchen replacements on a steady cadence, decoupled from new housing starts.
Preference for modular, space-efficient, frameless kitchens adds +1.2% to forecast growth, particularly in Germany, BENELUX, and Spain, where compact urban dwellings demand higher load-bearing base units and integrated storage.
Omnichannel retail and digitized showrooms lift conversion by an estimated +0.9%, compressing design-to-manufacture lead times in trade-focused and hybrid retail environments.
Certified wood and circular materials gain share under EU sustainability norms, contributing +0.7% as the EU Deforestation Regulation (EUDR) mandates geolocation traceability for timber inputs.
EPBD-led energy renovations bundle kitchen upgrades into whole-home retrofits, adding +0.6% in France, Germany, and Flanders.
Build-to-rent and senior-living specify turnkey modular kitchens at scale, contributing +0.4% in the UK, Germany, and Spain.
Key Restraints
Volatile raw material and energy costs burden profit margins, particularly for small workshops lacking scale to hedge input costs. Solid beech lumber prices in the EU rose sharply between 2021 and 2023, and UK softwood sawlog prices increased 38.5% in nominal terms.
Stringent environmental regulations increase compliance complexity. The Ecodesign for Sustainable Products Regulation requires repairable, recyclable furniture with a digital product passport by 2030, disproportionately affecting SMEs.
Intensifying import competition from low-cost Asian manufacturers places a ceiling on attainable pricing in economy and mid-range categories. Chinese furniture exports to the EU reached €13.254 billion in 2024, while EU wood furniture imports from outside the region rose 17% to USD 6.64 billion.
Structural skilled labor shortage limits bespoke and premium production capacity across Germany, Italy, and France as artisan apprenticeship pipelines fail to replace aging craftspeople.
Import/Export & Supplier Dynamics
Europe is the world's largest export hub for wooden kitchen furniture. In 2022, Germany led global exports of wooden kitchen furniture (HS 940340) with USD 2.87 billion (45.6 million items), followed by the European Union aggregate at USD 1.92 billion, Italy at USD 1.09 billion, and Poland at USD 212.8 million. Vietnam (USD 1.09 billion) and China (USD 885.2 million) are the principal non-European exporters to the region.
Country
2022 Export Value (USD 000s)
Quantity (Items)
Germany
2,867,916
45,571,700
Italy
1,091,423
17,342,900
Denmark
328,622
5,221,860
Spain
216,290
—
Poland
212,810
3,381,590
France
99,380
1,579,160
UK
52,870
840,112
EU import dynamics have shifted markedly. In 2018, EU imports of wooden kitchen furniture totalled USD 101.3 million, dominated by China (USD 30.5 million), Serbia (USD 15.1 million), and Russia (USD 13.7 million). By 2024, the wider EU wooden furniture import basket had grown to USD 6.64 billion, reflecting both volume growth and supply-chain diversification toward Eastern European and Asian sources. Serbia, Bosnia, Ukraine, and Turkey have emerged as near-shore manufacturing hubs for German and Italian OEMs seeking cost efficiency without sacrificing EUDR traceability.
Segmentation Analysis
By Product
Kitchen Cabinets led with 58.64% revenue share in 2025.
Kitchen Chairs are projected to expand at the fastest rate, 4.08% CAGR through 2031.
Others (tables, worktops, islands) complete the segment.
By Material
Wood held a 65.85% share in 2025, supported by FSC/PEFC certified supply chains and EUDR compliance investment.
Metal is projected to grow at 4.98%, the fastest rate among materials, driven by industrial-style designs and durable hardware.
Plastic & Polymer and Other Materials (glass, stone, composites) account for the balance.
By End-User
Residential accounted for 73.10% of 2025 sales.
Commercial (hospitality, build-to-rent, senior living, offices) is set to grow at a 5.48% CAGR through 2031.
By Distribution Channel
B2C Retail captured 69.72% in 2025, including specialist kitchen showrooms and flat-pack retail.
B2B Project channels are expanding at a 5.05% CAGR, driven by developer specifications and BIM-ready catalogues.
Regional Outlook
Country/Region
2025 Share
Growth Outlook (CAGR to 2031)
Germany
16.34%
3.9% (mature, replacement-led)
United Kingdom
~14.9%
3.7% (renovation-driven)
France
~13.2%
4.62% (fastest)
Italy
~11.6%
4.1% (design-led premium)
Spain
~9.3%
4.2% (modular demand)
BENELUX
~8.2%
3.5%
NORDICS
~7.1%
3.3%
Rest of Europe
~19.4%
3.8%
Germany remains the anchor market at 16.34% share, supported by a dense installer network, strong trade channels, and nationwide energy-efficiency programs that bundle kitchen upgrades. France is the standout growth market at 4.62% CAGR, underpinned by national renovation initiatives that incorporate built-in furniture and a progressive circular-economy framework. Poland, while not a top-five kitchen market, is the fastest-growing wooden furniture manufacturing base in Europe, benefiting from German near-shoring.
Europe Kitchen Furniture Industry Regional Market Share
Loading chart...
Competitive Landscape
The Europe kitchen furniture industry is characterized by low concentration and intense competition across price bands. Leading players include:
Nobilia (Germany) — volume leader in frameless modular cabinetry.
Howdens Joinery Group (UK) — trade-focused B2B distribution model.
Schmidt Groupe (France) — integrated manufacturing and retail.
Häcker Küchen (Germany) — premium and mid-market kitchen systems.
Nobia AB (Sweden) — multi-brand portfolio across the Nordics and UK.
IKEA — flat-pack and modular kitchen systems with >13% share of the broader European wooden furniture market.
Hülsta Group, Nolte Gruppe, Natuzzi, Kettal — leading players in the adjacent wooden furniture space, collectively holding 22.5% of that market in 2025.
Competitive strategy is increasingly defined by three vectors: certified sourcing (FSC/PEFC chain-of-custody to satisfy EUDR), digital specification (BIM catalogues, AR showrooms, configurator-led trade portals), and channel control (installer networks, franchise showrooms, and B2B project teams).
Value Chain Analysis
Upstream: Timber (softwood, hardwood, engineered wood), hardware, hinges and runners, adhesives, laminates, and finishes. Timber cost volatility is the single largest margin variable.
Component manufacturing: Panel cutting, edge-banding, drilling, lacquering, and assembly. Increasingly automated via CNC and robotic lines, offsetting skilled labour shortages.
OEM/ODM: Kitchen carcass and door production, often split across low-cost EU locations (Poland, Romania, Serbia) and premium domestic plants (Germany, Italy).
Installation & after-sales: Certified fitter networks, warranty servicing, and circular take-back schemes in Northern Europe.
Recent Industry Developments
2026: EU Deforestation Regulation large-company compliance deadline set for December 2026, mandating chain-of-custody traceability across the wooden furniture and cabinetry value chain.
2025–2026: Major German brands align material upgrades with sustainability messaging, combining certified content with anti-fingerprint surfaces and low-emission bonding to meet public-procurement thresholds.
2025: Circular take-back schemes expand in Northern Europe, with retailers enhancing credit offers for returned modules.
2024: EU wood furniture imports from outside the region rise 17% to USD 6.64 billion, intensifying price competition in economy and mid-range segments.
2026: Digitization of specification and showroom experiences compresses design-to-manufacture lead times, supporting conversion in trade-focused and hybrid retail environments.
Europe Kitchen Furniture Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Europe Kitchen Furniture Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.88% from 2020-2034
Segmentation
By Product
Kitchen Cabinets
Kitchen Chairs
Others
By Material
Wood
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Renovation and remodeling cycles sustaining multi-year replacement demand
3.1.2. Preference for modular, space-efficient, frameless kitchens
3.1.3. EPBD-led energy renovations bundling kitchen upgrades in whole-home retrofits
3.1.4. Omnichannel retail and digitized showrooms lifting conversion rates
3.2. Market Trends
3.2.1. Shift toward modular, frameless, space-efficient kitchen systems in urban dwellings
3.2.2. Rising adoption of certified wood and circular materials under EU sustainability norms
3.2.3. Digitization of showroom experiences and BIM-ready project catalogues
3.2.4. Growth of build-to-rent and senior-living specifications for turnkey modular kitchens
3.3. Market Restrains
3.3.1. Volatile raw material and energy costs squeezing manufacturer margins
3.3.2. Stringent EU environmental regulations increasing compliance complexity for SMEs
3.3.3. Intensifying competition from low-cost Asian furniture imports
3.3.4. Structural skilled labour shortage limiting bespoke and premium production capacity
Metal
Plastic & Polymer
Other Materials
By End-User
Residential
Commercial
By Distribution Channel
B2C Retail
B2B Project
By Geography
Germany
United Kingdom
France
Spain
Italy
BENELUX
NORDICS
Rest of Europe
3.4. Market Restraints
3.4.1. Volatile raw material and energy costs squeezing manufacturer margins
3.4.2. Stringent EU environmental regulations increasing compliance complexity for SMEs
3.4.3. Intensifying competition from low-cost Asian furniture imports
3.4.4. Structural skilled labour shortage limiting bespoke and premium production capacity
3.5. Market Challenges
3.5.1. Balancing affordability with sustainability compliance across price tiers
3.5.2. Managing supply-chain traceability under the EU Deforestation Regulation
3.5.3. Countering import-led price pressure in economy and mid-range segments
3.5.4. Addressing artisan and skilled labour shortages in key manufacturing countries
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Kitchen Cabinets
5.1.2. Kitchen Chairs
5.1.3. Others
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Wood
5.2.2. Metal
5.2.3. Plastic & Polymer
5.2.4. Other Materials
5.3. Market Analysis, Insights and Forecast - by End-User
5.3.1. Residential
5.3.2. Commercial
5.4. Market Analysis, Insights and Forecast - by Distribution Channel
5.4.1. B2C Retail
5.4.2. B2B Project
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. Germany
5.5.2. United Kingdom
5.5.3. France
5.5.4. Spain
5.5.5. Italy
5.5.6. BENELUX
5.5.7. NORDICS
5.5.8. Rest of Europe
6. Germany Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Kitchen Cabinets
6.1.2. Kitchen Chairs
6.1.3. Others
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Wood
6.2.2. Metal
6.2.3. Plastic & Polymer
6.2.4. Other Materials
6.3. Market Analysis, Insights and Forecast - by End-User
6.3.1. Residential
6.3.2. Commercial
6.4. Market Analysis, Insights and Forecast - by Distribution Channel
6.4.1. B2C Retail
6.4.2. B2B Project
7. United Kingdom Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Kitchen Cabinets
7.1.2. Kitchen Chairs
7.1.3. Others
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Wood
7.2.2. Metal
7.2.3. Plastic & Polymer
7.2.4. Other Materials
7.3. Market Analysis, Insights and Forecast - by End-User
7.3.1. Residential
7.3.2. Commercial
7.4. Market Analysis, Insights and Forecast - by Distribution Channel
7.4.1. B2C Retail
7.4.2. B2B Project
8. France Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Kitchen Cabinets
8.1.2. Kitchen Chairs
8.1.3. Others
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Wood
8.2.2. Metal
8.2.3. Plastic & Polymer
8.2.4. Other Materials
8.3. Market Analysis, Insights and Forecast - by End-User
8.3.1. Residential
8.3.2. Commercial
8.4. Market Analysis, Insights and Forecast - by Distribution Channel
8.4.1. B2C Retail
8.4.2. B2B Project
9. Spain Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Kitchen Cabinets
9.1.2. Kitchen Chairs
9.1.3. Others
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Wood
9.2.2. Metal
9.2.3. Plastic & Polymer
9.2.4. Other Materials
9.3. Market Analysis, Insights and Forecast - by End-User
9.3.1. Residential
9.3.2. Commercial
9.4. Market Analysis, Insights and Forecast - by Distribution Channel
9.4.1. B2C Retail
9.4.2. B2B Project
10. Italy Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Kitchen Cabinets
10.1.2. Kitchen Chairs
10.1.3. Others
10.2. Market Analysis, Insights and Forecast - by Material
10.2.1. Wood
10.2.2. Metal
10.2.3. Plastic & Polymer
10.2.4. Other Materials
10.3. Market Analysis, Insights and Forecast - by End-User
10.3.1. Residential
10.3.2. Commercial
10.4. Market Analysis, Insights and Forecast - by Distribution Channel
10.4.1. B2C Retail
10.4.2. B2B Project
11. BENELUX Market Analysis, Insights and Forecast, 2020-2034
11.1. Market Analysis, Insights and Forecast - by Product
11.1.1. Kitchen Cabinets
11.1.2. Kitchen Chairs
11.1.3. Others
11.2. Market Analysis, Insights and Forecast - by Material
11.2.1. Wood
11.2.2. Metal
11.2.3. Plastic & Polymer
11.2.4. Other Materials
11.3. Market Analysis, Insights and Forecast - by End-User
11.3.1. Residential
11.3.2. Commercial
11.4. Market Analysis, Insights and Forecast - by Distribution Channel
11.4.1. B2C Retail
11.4.2. B2B Project
12. NORDICS Market Analysis, Insights and Forecast, 2020-2034
12.1. Market Analysis, Insights and Forecast - by Product
12.1.1. Kitchen Cabinets
12.1.2. Kitchen Chairs
12.1.3. Others
12.2. Market Analysis, Insights and Forecast - by Material
12.2.1. Wood
12.2.2. Metal
12.2.3. Plastic & Polymer
12.2.4. Other Materials
12.3. Market Analysis, Insights and Forecast - by End-User
12.3.1. Residential
12.3.2. Commercial
12.4. Market Analysis, Insights and Forecast - by Distribution Channel
12.4.1. B2C Retail
12.4.2. B2B Project
13. Rest of Europe Market Analysis, Insights and Forecast, 2020-2034
13.1. Market Analysis, Insights and Forecast - by Product
13.1.1. Kitchen Cabinets
13.1.2. Kitchen Chairs
13.1.3. Others
13.2. Market Analysis, Insights and Forecast - by Material
13.2.1. Wood
13.2.2. Metal
13.2.3. Plastic & Polymer
13.2.4. Other Materials
13.3. Market Analysis, Insights and Forecast - by End-User
13.3.1. Residential
13.3.2. Commercial
13.4. Market Analysis, Insights and Forecast - by Distribution Channel
13.4.1. B2C Retail
13.4.2. B2B Project
14. Competitive Analysis
14.1. Company Profiles
14.1.1. Nobilia
14.1.1.1. Company Overview
14.1.1.2. Products
14.1.1.3. Company Financials
14.1.1.4. SWOT Analysis
14.1.2. Howdens Joinery Group
14.1.2.1. Company Overview
14.1.2.2. Products
14.1.2.3. Company Financials
14.1.2.4. SWOT Analysis
14.1.3. Schmidt Groupe
14.1.3.1. Company Overview
14.1.3.2. Products
14.1.3.3. Company Financials
14.1.3.4. SWOT Analysis
14.1.4. Häcker Küchen
14.1.4.1. Company Overview
14.1.4.2. Products
14.1.4.3. Company Financials
14.1.4.4. SWOT Analysis
14.1.5. Nobia AB
14.1.5.1. Company Overview
14.1.5.2. Products
14.1.5.3. Company Financials
14.1.5.4. SWOT Analysis
14.1.6. IKEA
14.1.6.1. Company Overview
14.1.6.2. Products
14.1.6.3. Company Financials
14.1.6.4. SWOT Analysis
14.1.7. Hülsta Group
14.1.7.1. Company Overview
14.1.7.2. Products
14.1.7.3. Company Financials
14.1.7.4. SWOT Analysis
14.1.8. Nolte Gruppe
14.1.8.1. Company Overview
14.1.8.2. Products
14.1.8.3. Company Financials
14.1.8.4. SWOT Analysis
14.1.9. Natuzzi
14.1.9.1. Company Overview
14.1.9.2. Products
14.1.9.3. Company Financials
14.1.9.4. SWOT Analysis
14.1.10. Kettal
14.1.10.1. Company Overview
14.1.10.2. Products
14.1.10.3. Company Financials
14.1.10.4. SWOT Analysis
14.2. Market Entropy
14.2.1. Company's Key Areas Served
14.2.2. Recent Developments
14.3. Company Market Share Analysis, 2026
14.3.1. Top 5 Companies Market Share Analysis
14.3.2. Top 3 Companies Market Share Analysis
14.4. List of Potential Customers
List of Figures
Figure 1: Global Europe Kitchen Furniture Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Germany Europe Kitchen Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 3: Germany Europe Kitchen Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 4: Germany Europe Kitchen Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 5: Germany Europe Kitchen Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 6: Germany Europe Kitchen Furniture Industry Revenue (Billion), by End-User 2026 & 2034
Figure 7: Germany Europe Kitchen Furniture Industry Revenue Share (%), by End-User 2026 & 2034
Figure 8: Germany Europe Kitchen Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 9: Germany Europe Kitchen Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 10: Germany Europe Kitchen Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 11: Germany Europe Kitchen Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 12: United Kingdom Europe Kitchen Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 13: United Kingdom Europe Kitchen Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 14: United Kingdom Europe Kitchen Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 15: United Kingdom Europe Kitchen Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 16: United Kingdom Europe Kitchen Furniture Industry Revenue (Billion), by End-User 2026 & 2034
Figure 17: United Kingdom Europe Kitchen Furniture Industry Revenue Share (%), by End-User 2026 & 2034
Figure 18: United Kingdom Europe Kitchen Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 19: United Kingdom Europe Kitchen Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 20: United Kingdom Europe Kitchen Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 21: United Kingdom Europe Kitchen Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 22: France Europe Kitchen Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 23: France Europe Kitchen Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 24: France Europe Kitchen Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 25: France Europe Kitchen Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 26: France Europe Kitchen Furniture Industry Revenue (Billion), by End-User 2026 & 2034
Figure 27: France Europe Kitchen Furniture Industry Revenue Share (%), by End-User 2026 & 2034
Figure 28: France Europe Kitchen Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 29: France Europe Kitchen Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 30: France Europe Kitchen Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 31: France Europe Kitchen Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 32: Spain Europe Kitchen Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 33: Spain Europe Kitchen Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 34: Spain Europe Kitchen Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 35: Spain Europe Kitchen Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 36: Spain Europe Kitchen Furniture Industry Revenue (Billion), by End-User 2026 & 2034
Figure 37: Spain Europe Kitchen Furniture Industry Revenue Share (%), by End-User 2026 & 2034
Figure 38: Spain Europe Kitchen Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 39: Spain Europe Kitchen Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 40: Spain Europe Kitchen Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 41: Spain Europe Kitchen Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 42: Italy Europe Kitchen Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 43: Italy Europe Kitchen Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 44: Italy Europe Kitchen Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 45: Italy Europe Kitchen Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 46: Italy Europe Kitchen Furniture Industry Revenue (Billion), by End-User 2026 & 2034
Figure 47: Italy Europe Kitchen Furniture Industry Revenue Share (%), by End-User 2026 & 2034
Figure 48: Italy Europe Kitchen Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 49: Italy Europe Kitchen Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 50: Italy Europe Kitchen Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 51: Italy Europe Kitchen Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 52: BENELUX Europe Kitchen Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 53: BENELUX Europe Kitchen Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 54: BENELUX Europe Kitchen Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 55: BENELUX Europe Kitchen Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 56: BENELUX Europe Kitchen Furniture Industry Revenue (Billion), by End-User 2026 & 2034
Figure 57: BENELUX Europe Kitchen Furniture Industry Revenue Share (%), by End-User 2026 & 2034
Figure 58: BENELUX Europe Kitchen Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 59: BENELUX Europe Kitchen Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 60: BENELUX Europe Kitchen Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 61: BENELUX Europe Kitchen Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 62: NORDICS Europe Kitchen Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 63: NORDICS Europe Kitchen Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 64: NORDICS Europe Kitchen Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 65: NORDICS Europe Kitchen Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 66: NORDICS Europe Kitchen Furniture Industry Revenue (Billion), by End-User 2026 & 2034
Figure 67: NORDICS Europe Kitchen Furniture Industry Revenue Share (%), by End-User 2026 & 2034
Figure 68: NORDICS Europe Kitchen Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 69: NORDICS Europe Kitchen Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 70: NORDICS Europe Kitchen Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 71: NORDICS Europe Kitchen Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 72: Rest of Europe Europe Kitchen Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 73: Rest of Europe Europe Kitchen Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 74: Rest of Europe Europe Kitchen Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 75: Rest of Europe Europe Kitchen Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 76: Rest of Europe Europe Kitchen Furniture Industry Revenue (Billion), by End-User 2026 & 2034
Figure 77: Rest of Europe Europe Kitchen Furniture Industry Revenue Share (%), by End-User 2026 & 2034
Figure 78: Rest of Europe Europe Kitchen Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 79: Rest of Europe Europe Kitchen Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 80: Rest of Europe Europe Kitchen Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 81: Rest of Europe Europe Kitchen Furniture Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Global Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 3: Global Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 4: Global Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 5: Global Europe Kitchen Furniture Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 6: Germany Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 7: Germany Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 8: Germany Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 9: Germany Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 10: Germany Europe Kitchen Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 11: United Kingdom Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 12: United Kingdom Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 13: United Kingdom Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 14: United Kingdom Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 15: United Kingdom Europe Kitchen Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 16: France Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 17: France Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 18: France Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 19: France Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 20: France Europe Kitchen Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Spain Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 22: Spain Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 23: Spain Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 24: Spain Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 25: Spain Europe Kitchen Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 26: Italy Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 27: Italy Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 28: Italy Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 29: Italy Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 30: Italy Europe Kitchen Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 31: BENELUX Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 32: BENELUX Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 33: BENELUX Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 34: BENELUX Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 35: BENELUX Europe Kitchen Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 36: NORDICS Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 37: NORDICS Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 38: NORDICS Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 39: NORDICS Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 40: NORDICS Europe Kitchen Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 41: Rest of Europe Europe Kitchen Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 42: Rest of Europe Europe Kitchen Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 43: Rest of Europe Europe Kitchen Furniture Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 44: Rest of Europe Europe Kitchen Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 45: Rest of Europe Europe Kitchen Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the Europe kitchen furniture industry market size in 2026?
The Europe kitchen furniture industry market is estimated at USD 23.12 billion in 2026, up from USD 21.96 billion in 2025, and is projected to reach USD 27.97 billion by 2031 at a CAGR of 3.88%.
2Which country dominates the Europe kitchen furniture industry market?
Germany led the Europe kitchen furniture industry market with a 16.34% revenue share in 2025, supported by a dense installer network, strong trade channels, and energy-efficiency renovation programs that bundle kitchen upgrades.
3Which segment is the fastest growing in the Europe kitchen furniture industry market?
The commercial end-user segment is projected to grow at the fastest rate, 5.48% CAGR through 2031, driven by hospitality, build-to-rent, and senior-living specifications for turnkey modular kitchens.
4Who are the major companies in the Europe kitchen furniture industry market?
Nobilia, Howdens Joinery Group, Schmidt Groupe, Häcker Küchen, and Nobia AB are the leading companies, alongside IKEA, Hülsta Group, Nolte Gruppe, Natuzzi, and Kettal in the broader wooden furniture space.
5What is driving growth in the Europe kitchen furniture industry market?
Renovation and remodeling cycles contribute an estimated +1.8% to CAGR, while modular frameless kitchen demand adds +0.9% to 1.2% and EU sustainability norms drive certified wood adoption across the region.
6What are the key challenges in the Europe kitchen furniture industry market?
Volatile timber and energy costs, stringent EU environmental regulations, low-cost Asian import competition, and structural skilled labor shortages are the primary constraints on margin recovery and volume growth.
7How large are Europe's exports of wooden kitchen furniture?
Germany exported USD 2.87 billion (45.6 million items) of wooden kitchen furniture in 2022, followed by Italy at USD 1.09 billion and Poland at USD 212.8 million, according to UN Comtrade data.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research inputs are derived from primary interviews with senior decision-makers across the kitchen furniture value chain, including cabinetry OEMs, component suppliers, trade distributors, and installer networks.
We conduct structured interviews with 4–5 specific company types: (1) kitchen cabinet and carcass manufacturers; (2) hardware, hinge, and runner suppliers; (3) timber and panel board suppliers; (4) specialist kitchen retail chains and trade counters; and (5) B2B project specifiers and developer procurement teams.
Stakeholder job titles interviewed include Procurement Director, Head of Product Management, Trade Channel Manager, and Sustainability & Compliance Lead, ensuring cross-functional visibility into pricing, specification, and sourcing decisions.
Interviews are conducted across Germany, France, Italy, the UK, Spain, BENELUX, and the Nordics, with sample stratification by revenue band, product focus, and channel mix.
Primary research also incorporates factory floor observations and showroom audits to validate capacity utilisation, lead times, and specification trends.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
32%
Head of Product Management
28%
Trade Channel Manager
22%
Sustainability & Compliance Lead
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Kitchen Cabinet & Carcass Manufacturers
35%
Hardware & Component Suppliers
20%
Timber & Panel Board Suppliers
15%
Specialist Kitchen Retailers & Trade Counters
18%
B2B Project Specifiers & Developers
12%
Secondary Research & Industry Benchmarking
20–30% of research inputs come from secondary sources, including official multilateral and governmental institutions such as UN Comtrade, the World Bank WITS, Eurostat, and OECD.
We benchmark against recognised non-profit trade associations and technical standards bodies, including the European Panel Federation (EPF), CEI-Bois (European Confederation of Woodworking Industries), FSC and PEFC certification schemes, and Eurostat housing and construction statistics.
Standard financial databases — Bloomberg, Factiva, Hoovers, and PitchBook — are used to validate company revenues, ownership structures, and M&A activity.
Regulatory benchmarking covers the EU Deforestation Regulation (EUDR), the Energy Performance of Buildings Directive (EPBD), and the Ecodesign for Sustainable Products Regulation (ESPR).
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up estimation uses 4 specific quantitative metrics: (1) annual kitchen installation volumes by country from Eurostat building permit and renovation data; (2) average transaction value per installed kitchen by product tier; (3) manufacturer revenue per unit shipped (carcass, door, and worktop); and (4) replacement cycle frequency derived from housing stock age distributions.
Top-down estimation reconciles these bottom-up figures against national statistical accounts, trade association shipment data, and our proprietary panel of OEM revenue disclosures.
Segment-level forecasts are built using driver-impact attribution, assigning percentage-point contributions to each growth driver (renovation cycles, modular demand, omnichannel retail, certification, EPBD, and build-to-rent).
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-source triangulation and iterative validation.
Every data point is cross-checked against at least two independent primary or official secondary sources before inclusion.
Outlier detection and reconciliation are performed at the country and segment level to eliminate double counting across distribution channels.
Every report is updated to the date of purchase, incorporating the latest available trade statistics, regulatory announcements, and company disclosures.
Final quality assurance is conducted by a senior analyst panel, with sign-off on methodology, assumptions, and forecast ranges prior to publication.