1What is the size of the Kenya flexible packaging market?
The Kenya flexible packaging market is estimated at USD 2.24 billion in 2026, up from USD 2.19 billion in 2025, and is projected to reach USD 2.52 billion by 2031, expanding at a 2.35% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Kenya Flexible Packaging Market
 by Material (Plastic, Paper, Metal Foil, Bioplastics and Compostable Materials, More), by Product Type (Bags and Pouches, Films and Wraps, Sachets and Stick Packs, More), by End-User Industry (Food, Beverage, Healthcare and Pharmaceutical, Personal Care and Cosmetics, More), by Printing Technology (Flexography, Rotogravure, Digital Printing, More), by Nairobi Metropolitan, by Coast (Mombasa & Kilifi), by Central Highlands, by Western & Nyanza, by Rift Valley & Upcountry Forecast 2026-2034
Research Associate

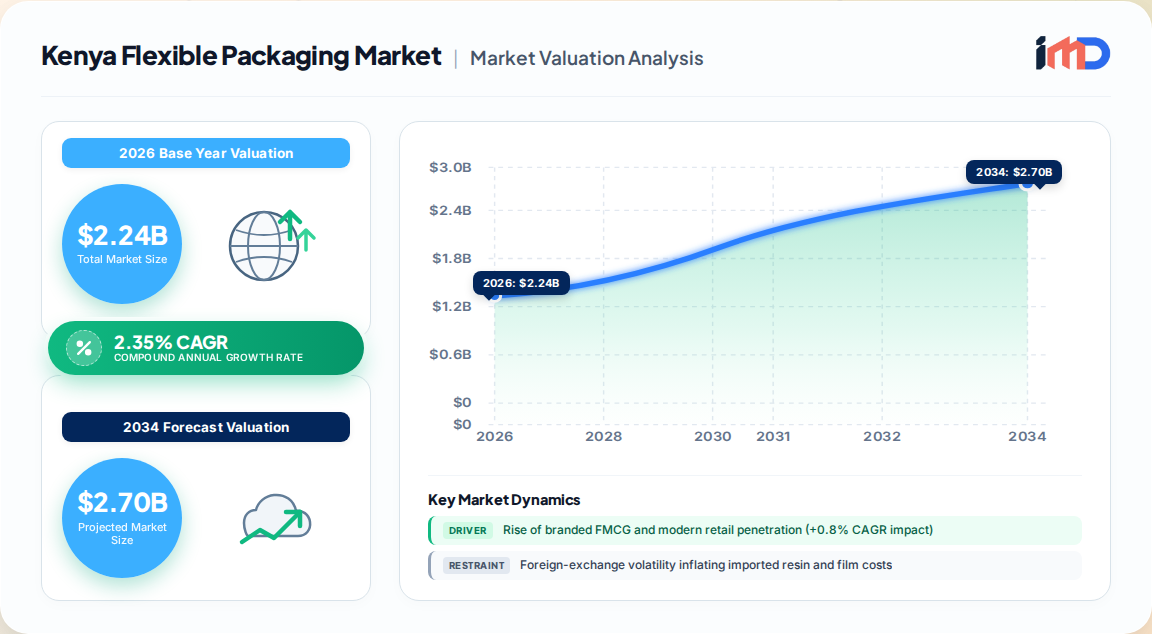
The Kenya flexible packaging market is estimated at USD 2.24 billion in 2026, up from USD 2.19 billion in 2025, and is projected to reach USD 2.52 billion by 2031, expanding at a 2.35% CAGR over the forecast window. Growth is anchored in Kenya's position as East Africa's manufacturing and distribution hub, the operationalization of Vision 2030 industrial incentives, and resilient domestic consumption across food, personal care, and pharmaceutical verticals.
Our proprietary bottom-up modelling — triangulated from converter-level shipment audits, resin import balances, and brand-owner packaging spend disclosures — indicates that volume growth outpaces value growth, reflecting a structural mix shift toward downgauged mono-material structures. The market remains moderately concentrated, with domestic converters and regional subsidiaries of global packaging majors competing on barrier performance, print quality, and EPR compliance readiness.
Key structural metrics framing the forecast:
The Kenyan market is being reshaped by six identifiable demand-side forces, each with a measurable effect on the forecast CAGR.
| Driver | Estimated CAGR Impact | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rise of branded FMCG and modern retail penetration | +0.8% | National; concentrated in Nairobi, Mombasa, Kisumu | Medium term (2–4 years) |
| Agricultural-export upgrade to value-added consumer packs | +0.6% | National; strongest in horticultural zones | Long term (≥4 years) |
| Explosive growth of quick-commerce and dark-store models | +0.4% | Urban centers, Nairobi metropolitan area | Short term (≤2 years) |
| Mandatory EPR and recyclability targets | +0.3% | National implementation via NEMA | Medium term (2–4 years) |
| Corporate carbon-footprint pledges driving light-weighting | +0.3% | Global brands operating in Kenya | Medium term (2–4 years) |
| Surge in off-grid solar-powered cold-chain nodes up-country | +0.2% | Rural and semi-urban areas | Long term (≥4 years) |
The most consequential driver remains the rapid formalization of modern retail. Supermarket and convenience chains are expanding beyond Nairobi into secondary towns such as Nyeri, Meru, and Eldoret, compelling FMCG producers to adopt high-barrier laminates that preserve freshness and support brand visibility. Flexible films enable SKU proliferation for new flavors and pack sizes without large mold investments — a critical advantage in promotional-driven retail environments.
On the restraint side, three factors temper topline expansion:
The 2024 Extended Producer Responsibility (EPR) rules represent the single most disruptive regulatory event in the Kenyan packaging sector in a decade. Every package placed on the market must be reported, with fees assessed per kilogram through Producer Responsibility Organizations such as KEPRO. This has triggered a structural respecification of laminate architectures.
Key compliance-driven shifts:
Early movers that qualify recyclable structures are capturing preferred-supplier status with multinational FMCG firms bound by global circular-economy pledges. This dynamic is accelerating consolidation among smaller converters unable to absorb compliance costs.
Plastic substrates dominate the Kenyan market, underpinned by polyethylene and polypropylene availability through regional petrochemical supply chains. However, the material mix is gradually diversifying.
| Material | 2025 Share | Forecast CAGR (2026–2031) |
|---|---|---|
| Plastic | 67.85% | 2.1% |
| Paper & Paperboard | ~18% | 3.2% |
| Metal Foil | ~10% | 1.8% |
| Bioplastics & Compostables | ~4% | 4.95% |
Bags and pouches remain the workhorse format, benefiting from the expansion of stand-up pouch filling lines at converter facilities in Nairobi's Industrial Area and Athi River. Sachets and stick packs are growing fastest, driven by quick-commerce demand for portion-controlled formats that withstand multiple handling points.
Food applications anchor demand, but personal care and cosmetics represent the fastest-growing vertical as branded personal-care products penetrate rural markets through sachet formats. Healthcare and pharmaceutical packaging is also expanding, albeit from a smaller base, driven by local manufacturing investments under Kenya's pharmaceutical industrialization agenda.
Flexography remains the dominant print technology, accounting for 45.05% of the market in 2025, owing to its cost efficiency for high-volume flexible substrates. Digital printing is registering a 4.89% CAGR, fueled by brand owners' demand for short-run customization, variable data, and faster turnaround times — particularly in the quick-commerce channel where limited-edition graphics influence app-based conversion.
The Kenyan flexible packaging market features a mix of domestic converters, regional subsidiaries, and imports from South Africa and Asia. The competitive battle is shifting from capacity expansion to sustainability engineering — the ability to deliver compliant, recyclable structures at competitive price points.
Leading domestic players include Ramco Plexus Ltd., Flexipac Limited, Polyflex Industries Limited, and Silafrica Plastics & Packaging International Ltd., while Huhtamaki Oyj operates as a regional subsidiary with global R&D backing. These companies compete on barrier performance, print quality, EPR compliance readiness, and supply-chain responsiveness.
Strategic imperatives for converters through 2031:
Kenya's flexible packaging value chain is structurally import-dependent for raw materials and high-barrier films, while finished packaging is increasingly produced domestically.
Import dynamics:
Export dynamics:
Supplier risk assessment:
Kenya's flexible packaging growth is geographically concentrated but gradually dispersing. The Nairobi metropolitan area accounts for the largest share of demand, driven by FMCG headquarters, modern retail concentration, and quick-commerce infrastructure. Mombasa benefits from port-linked trade and export-oriented processing, while Kisumu and Eldoret are emerging as secondary hubs for agricultural processing and regional distribution.
The forecast through 2031 points to a market that will grow steadily but face structural margin pressure. Success will accrue to converters that:
The Kenya flexible packaging market will not be a high-growth story in absolute terms, but it will be a quality-growth story — where regulatory compliance, material innovation, and channel agility determine winners and losers.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.35% from 2020-2034 |
| Segmentation |
|
By End-User Industry
By Printing Technology
| By Geography |
|
The Kenya flexible packaging market is estimated at USD 2.24 billion in 2026, up from USD 2.19 billion in 2025, and is projected to reach USD 2.52 billion by 2031, expanding at a 2.35% CAGR.
Plastic substrates maintained a 67.85% share of the Kenya flexible packaging market in 2025, while bioplastics and compostables are the fastest-growing material class at a 4.95% CAGR through 2031.
Leading companies include Ramco Plexus Ltd., Flexipac Limited, Polyflex Industries Limited, Silafrica Plastics & Packaging International Ltd., and Huhtamaki Oyj.
The 2024 Extended Producer Responsibility (EPR) rules require per-kilogram fees and design-for-recycling evidence, pushing brand owners toward mono-polyolefin laminates and compostable films certified to EN 13432, accelerating product development in bioplastics.
Personal care and cosmetics is forecast to expand at a 4.71% CAGR through 2031, while food applications represented 32.08% of the market size in 2025.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Packaging Development Manager | 35% |
| Procurement Director | 28% |
| Supply Chain Head | 22% |
| Sustainability/Compliance Officer | 15% |
| Company Type | Representation (%) |
|---|---|
| Flexible Packaging Converters | 40% |
| FMCG Brand Owners | 25% |
| Resin and Film Suppliers/Distributors | 20% |
| Retail Chain Packaging Buyers | 10% |
| EPR Producer Responsibility Organizations | 5% |

Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
 Related Reports
