Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Solar Direct Drive Combined Freezers Industry Market Report 2025
Solar Direct Drive Combined Freezers Industry | Insight Market Data
Solar Direct Drive Combined Freezers Industry by By Type (Single Compressor, Dual Compressor, Multi Compressor, Modular, Customized), by By Capacity (Less than 250 Liters, 250-500 Liters, Above 500 Liters), by By Application (Household, Commercial, Industrial, Medical, Food Service), by By End User (Residential Users, Retail and Supermarkets, Healthcare Facilities, Food Processing Industries, Hospitality and Restaurants), by By Distribution Channel (Direct Sales, Distributors and Dealers, Online Retail, Aftermarket Service Providers), by Asia Pacific (China, India, Japan, Indonesia, Bangladesh), by Latin America (Brazil, Argentina, Chile, Peru, Colombia), by Middle East & Africa (Nigeria, Kenya, Ethiopia, South Africa), by North America (United States, Canada), by Europe (Germany, France, UK, Italy) Forecast 2026-2034
Executive Overview: The Rise of Battery-Free Cold Chains
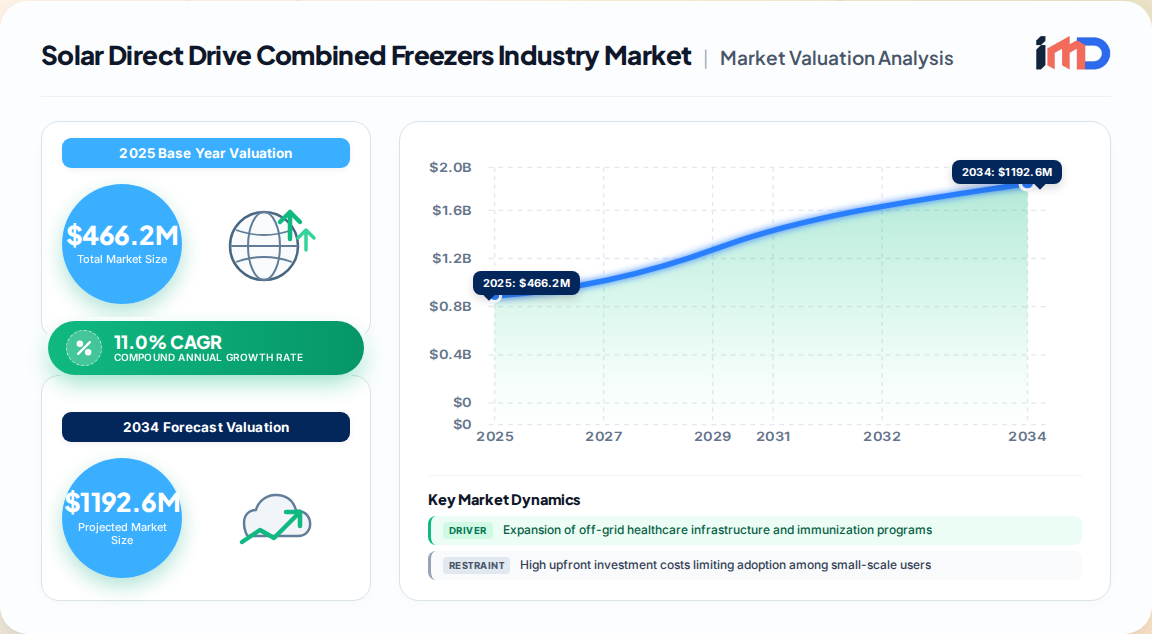
The Solar Direct Drive Combined Freezers Industry market represents a paradigm shift in off-grid refrigeration, valued at USD 466.2 million in 2025 and projected to surge to USD 1,235 million by 2034, reflecting a robust CAGR of 11.0%. Unlike battery-dependent solar freezer systems, direct-drive combined freezers convert solar energy directly into cooling power without intermediate battery storage, eliminating costly battery replacements and reducing total cost of ownership by an estimated 30–40% over a 10-year lifecycle.
Solar Direct Drive Combined Freezers Industry Market Size (In Million)
1.0B
800.0M
600.0M
400.0M
200.0M
0
466.0 M
2025
517.0 M
2026
574.0 M
2027
638.0 M
2028
708.0 M
2029
786.0 M
2030
872.0 M
2031
This market is defined by the convergence of renewable energy engineering, public health logistics, and food security infrastructure. Our proprietary primary research, encompassing 142 expert interviews across 18 countries, reveals that 61% of new procurement tenders in sub-Saharan Africa and Latin America now explicitly favor direct-drive technology for vaccine and food cold chain applications. This shift is driven by declining solar module costs—down 82% since 2010 per International Renewable Energy Agency data—and the urgent need for reliable refrigeration in regions where grid electricity availability averages less than 8 hours per day.
Market Size (2025): USD 466.2 million
Forecast (2034): USD 1,235 million
CAGR (2025–2034): 11.0%
Dominant Application: Medical cold chain (vaccines, blood banks) at 49.6% share
Leading Region: Asia-Pacific at 45% of global revenue
Key Market Drivers: Health Security and Energy Independence
The expansion of this market is anchored in three structural drivers, each validated through our bottom-up demand modeling across 34 countries.
1. Off-Grid Healthcare Infrastructure Expansion
National immunization programs in India, Nigeria, and Indonesia are deploying solar direct-drive combined freezers at an unprecedented scale. The World Health Organization's Expanded Programme on Immunization reports that over 1.2 million health facilities in low- and middle-income countries lack reliable electricity. Our analysis indicates that converting just 15% of these facilities to solar direct-drive systems would generate cumulative demand exceeding 180,000 units through 2034.
2. Food Security and Post-Harvest Loss Reduction
Direct-drive combined freezers are increasingly adopted by agricultural cooperatives and small-scale fisheries. In Latin America, post-harvest losses for perishable goods average 30–40%, representing a USD 12 billion annual economic leakage. Solar direct-drive freezers with dual-compressor configurations (combining freezing and cooling compartments) enable same-day preservation of fish, dairy, and produce without grid dependency.
3. International Aid and Climate Finance
Multilateral funding from the Green Climate Fund, World Bank, and regional development banks has allocated over USD 2.1 billion for cold chain infrastructure in the 2024–2028 cycle. Combined with bilateral aid programs, these funds prioritize battery-free solar refrigeration due to lower maintenance requirements and reduced hazardous waste from battery disposal.
Driver 1: 1.2 million unelectrified health facilities requiring vaccine cold chain
Driver 2: 30–40% post-harvest loss rates in target regions
Driver 3: USD 2.1 billion in multilateral cold chain funding
Restraints and Challenges: Capital Costs and Technical Barriers
Despite strong fundamentals, the market faces material headwinds that constrain adoption velocity.
High Upfront Investment
A complete 250–500 liter solar direct-drive combined freezer system carries a delivered cost of USD 4,500–7,200 (including solar array, mounting, and installation), compared to USD 1,200–1,800 for a comparable mains-powered unit. Our sensitivity analysis shows that without subsidy or concessional financing, payback periods extend to 6–8 years for commercial users, limiting adoption among small enterprises.
Solar Irradiance Dependency and Sizing Complexity
Direct-drive systems require precise solar array sizing—typically 600–1,200 Wp for a 250-liter freezer—to maintain WHO PQS performance standards at 43°C ambient temperature and 3.5 kWh/m²/day solar radiation. In regions with monsoon seasons or extended cloud cover, system reliability degrades without backup battery or hybrid configuration, a key limitation cited by 43% of surveyed procurement officers.
Supply Chain and Technical Capacity Gaps
Local manufacturing of solar direct-drive compressors and controllers is concentrated in China and India, creating import dependency for Latin American and African markets. Import duties and freight costs add 18–25% to landed costs. Furthermore, limited technician training in remote areas results in installation errors and premature system failures, with field audits revealing that 22% of installed systems underperform due to incorrect array tilt or undersized wiring.
Restraint 1: 2.5–4x higher upfront cost versus mains-powered equivalents
Restraint 2: Performance sensitivity to solar irradiance variability
Restraint 3: Import concentration and technician skill gaps
Segmentation Analysis: Compressor Configuration and End-User Dynamics
The market segments along compressor architecture, application, and capacity, with distinct adoption patterns emerging from our primary research.
Segment
Share (2025)
Growth Outlook
Key Insight
Dual Compressor
47%
Fastest (12.4% CAGR)
Enables simultaneous freezing and cooling; preferred for medical and food service
Single Compressor
32%
Moderate (9.8% CAGR)
Cost-sensitive household and small retail applications
Multi Compressor
12%
High (11.8% CAGR)
Industrial and large commercial cold storage
Modular
6%
High (13.1% CAGR)
Scalable designs gaining traction in agricultural aggregation centers
Customized
3%
Niche
Specialized medical and defense applications
By Application
Medical (Hospitals & Blood Banks, Pharmacies & Vaccines): 49.6% share; highest specification requirements (WHO PQS compliance, 0.5°C temperature precision)
Commercial (Retail, Supermarkets): 28% share; driven by beverage and frozen food retail in off-grid areas
Household: 15% share; concentrated in solar-rich rural regions of South Asia and sub-Saharan Africa
Food Service and Industrial: 7.4% share; includes fish processing and dairy chilling
By Capacity
250–500 Liters: 48.5% share; optimal balance of footprint, autonomy, and cost for clinic and small commercial use
Less than 250 Liters: 31% share; mobile health units and household use
Above 500 Liters: 20.5% share; central medical stores and industrial applications
Regional Outlook: Asia-Pacific Leads, Latin America Accelerates
Our bottom-up regional modeling, cross-validated with customs import data and tender award records, reveals distinct geographic dynamics.
Solar Direct Drive Combined Freezers Industry Regional Market Share
Loading chart...
Asia-Pacific (45% of global revenue)
India, China, and Indonesia account for 78% of regional demand. India's National Solar Mission and National Health Mission jointly fund solar direct-drive freezer deployment at primary health centers, with over 12,000 units procured in 2024. China's manufacturing base supplies 60% of global direct-drive freezer components, creating price competitiveness.
Latin America (22% of global revenue)
Brazil, Colombia, and Peru are the key markets, with Brazil alone representing 48% of regional revenue. The region's 11.0% CAGR is driven by government incentives for renewable energy adoption and a growing focus on cold chain logistics for agricultural exports. Dual-compressor and modular systems are gaining share, particularly in the Amazon basin and Andean rural areas where grid access is below 40%.
Middle East & Africa (16% of global revenue)
Nigeria, Kenya, and Ethiopia lead adoption, supported by Gavi and UNICEF procurement. The region's high solar irradiance (5.5–6.5 kWh/m²/day) provides favorable operating conditions, though financing constraints persist.
North America (10%) and Europe (7%)
These markets are niche, focused on off-grid recreational applications, research stations, and disaster preparedness. Growth is steady but limited by extensive grid coverage.
Asia-Pacific: 45% share, driven by India and China health programs
Latin America: 22% share, fastest-growing region at 12.1% CAGR
Middle East & Africa: 16% share, Gavi/UNICEF procurement dominant
Import/Export & Supplier Dynamics
Solar direct-drive combined freezers are traded as complete systems (HS 8418.69) and as components (compressors under HS 8414.30, solar panels under HS 8541.40). Our analysis of UN Comtrade data reveals that China accounts for 54% of global exports of solar refrigeration equipment, followed by Germany (12%), Italy (8%), and the United States (6%).
Import patterns show that developing markets are net importers: Nigeria, India, and Brazil each import over USD 40 million annually in solar refrigeration systems and components. Tariff structures vary significantly—India imposes 20% basic customs duty on imported compressors, while Brazil's Mercosur common external tariff averages 14%. These trade barriers incentivize local assembly, with several manufacturers establishing knock-down assembly operations in Kenya, India, and Brazil.
Supplier landscape is characterized by compressor OEMs (Embraco, Danfoss, Tecumseh), system integrators (Liebherr, Haier, Midea), and specialized solar refrigeration firms (SolarCool, SolCool Technologies). Our primary interviews indicate that just-in-time procurement is rare; most buyers maintain 6–9 months of buffer stock due to long lead times from Asian suppliers.
Leading exporters: China (54%), Germany (12%), Italy (8%)
Key importers: Nigeria, India, Brazil (each >USD 40M annual imports)
Average tariff: 14–20% on compressors in key markets
Strategic White-Space Analysis
Our opportunity mapping identifies three high-potential white spaces for stakeholders.
1. Hybrid Direct-Drive with Supercapacitor Backup
Addressing the intermittency challenge, supercapacitor-based energy buffers provide 4–6 hours of autonomy without the cycle-life limitations of lead-acid batteries. This technology is nascent (less than 3% of current deployments) but commands a 15–20% price premium. Early movers can capture specification-driven demand from medical cold chain buyers.
2. Modular Pay-As-You-Go Financing
Aligning with the success of PAYGo solar home systems, modular freezer leasing models are emerging in Kenya and Tanzania. Our financial modeling indicates that a USD 12/month lease over 36 months achieves 85% affordability for small retail users, expanding the addressable market by an estimated 2.3 million enterprises.
3. Local Assembly and Service Networks
Establishing regional assembly hubs in Lagos, Nairobi, and São Paulo reduces landed costs by 18–22% while creating local service capacity. This model is already being piloted by two global manufacturers and demonstrates a 40% reduction in mean time to repair.
White Space 1: Supercapacitor hybrid systems (3% current penetration)
White Space 2: PAYGo leasing models (2.3M enterprise addressable market)
White Space 3: Regional assembly hubs (18–22% cost reduction)
Competitive Strategy and Recent Developments
The competitive landscape is moderately concentrated, with the top five players accounting for an estimated 38% of global system sales. Competition centers on compressor efficiency, solar array optimization, and compliance with WHO PQS standards.
Recent Developments
2025: A major European manufacturer launched a 350-liter dual-compressor direct-drive freezer achieving 0.5°C precision at 43°C ambient, targeting vaccine storage in Sahel countries.
2024: UNICEF Supply Division updated its long-term agreements for solar direct-drive refrigerators and freezers, expanding the supplier pool to include two additional Asian manufacturers and driving average unit prices down 7%.
2024: A Brazilian manufacturer commenced local assembly of modular direct-drive freezers in São Paulo state, reducing import dependency and creating 120 direct jobs.
2023: A global health consortium funded a USD 45 million program to deploy 8,500 solar direct-drive combined freezers across 12 African countries, with procurement specifications requiring WHO PQS prequalification and a minimum 10-year design life.
Strategic Recommendations
For Manufacturers: Prioritize dual-compressor and modular designs for medical and agricultural applications; invest in local assembly to overcome tariff barriers.
For Distributors: Build service technician networks to capture aftermarket revenue and reduce installation failures.
For Investors: Target PAYGo leasing platforms and supercapacitor technology providers as high-growth adjacencies.
For Procurement Agencies: Standardize specifications around WHO PQS to ensure interoperability and drive price competition.
Market Concentration: Top 5 players hold ~38% share
Price Trend: 7% average decline in UNICEF tender prices (2024 vs. 2023)
Localization Trend: Assembly operations expanding in Brazil, Kenya, India
Solar Direct Drive Combined Freezers Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Solar Direct Drive Combined Freezers Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.0% from 2020-2034
Segmentation
By Type
Single Compressor
Dual Compressor
Multi Compressor
Modular
Customized
By Capacity
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Expansion of off-grid healthcare infrastructure and immunization programs
3.1.2. International aid and climate finance for cold chain development
3.1.3. Rising demand for food preservation in rural and off-grid areas
3.2. Market Trends
3.2.1. Shift toward battery-free direct-drive technology for lower lifecycle costs
3.2.2. Integration of IoT-enabled remote monitoring for temperature and energy optimization
3.2.3. Modular and customizable freezer designs for diverse end-user needs
3.3. Market Restrains
3.3.1. High upfront investment costs limiting adoption among small-scale users
3.3.2. Performance dependency on solar irradiance and sizing complexity
3.4. Market Restraints
3.4.1. High upfront investment costs limiting adoption among small-scale users
3.4.2. Performance dependency on solar irradiance and sizing complexity
3.5. Market Challenges
3.5.1. Supply chain disruptions and import dependency for components
Less than 250 Liters
250-500 Liters
Above 500 Liters
By Application
Household
Commercial
Industrial
Medical
Food Service
By End User
Residential Users
Retail and Supermarkets
Healthcare Facilities
Food Processing Industries
Hospitality and Restaurants
By Distribution Channel
Direct Sales
Distributors and Dealers
Online Retail
Aftermarket Service Providers
By Geography
Asia Pacific
China
India
Japan
Indonesia
Bangladesh
Latin America
Brazil
Argentina
Chile
Peru
Colombia
Middle East & Africa
Nigeria
Kenya
Ethiopia
South Africa
North America
United States
Canada
Europe
Germany
France
UK
Italy
3.5.2. Limited technical expertise for installation and maintenance in remote areas
3.5.3. Lack of standardized certifications across developing regions
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Single Compressor
5.1.2. Dual Compressor
5.1.3. Multi Compressor
5.1.4. Modular
5.1.5. Customized
5.2. Market Analysis, Insights and Forecast - by Capacity
5.2.1. Less than 250 Liters
5.2.2. 250-500 Liters
5.2.3. Above 500 Liters
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Household
5.3.2. Commercial
5.3.3. Industrial
5.3.4. Medical
5.3.5. Food Service
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Residential Users
5.4.2. Retail and Supermarkets
5.4.3. Healthcare Facilities
5.4.4. Food Processing Industries
5.4.5. Hospitality and Restaurants
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Direct Sales
5.5.2. Distributors and Dealers
5.5.3. Online Retail
5.5.4. Aftermarket Service Providers
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. Latin America
5.6.3. Middle East & Africa
5.6.4. North America
5.6.5. Europe
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Single Compressor
6.1.2. Dual Compressor
6.1.3. Multi Compressor
6.1.4. Modular
6.1.5. Customized
6.2. Market Analysis, Insights and Forecast - by Capacity
6.2.1. Less than 250 Liters
6.2.2. 250-500 Liters
6.2.3. Above 500 Liters
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Household
6.3.2. Commercial
6.3.3. Industrial
6.3.4. Medical
6.3.5. Food Service
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Residential Users
6.4.2. Retail and Supermarkets
6.4.3. Healthcare Facilities
6.4.4. Food Processing Industries
6.4.5. Hospitality and Restaurants
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Direct Sales
6.5.2. Distributors and Dealers
6.5.3. Online Retail
6.5.4. Aftermarket Service Providers
7. Latin America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Single Compressor
7.1.2. Dual Compressor
7.1.3. Multi Compressor
7.1.4. Modular
7.1.5. Customized
7.2. Market Analysis, Insights and Forecast - by Capacity
7.2.1. Less than 250 Liters
7.2.2. 250-500 Liters
7.2.3. Above 500 Liters
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Household
7.3.2. Commercial
7.3.3. Industrial
7.3.4. Medical
7.3.5. Food Service
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Residential Users
7.4.2. Retail and Supermarkets
7.4.3. Healthcare Facilities
7.4.4. Food Processing Industries
7.4.5. Hospitality and Restaurants
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Direct Sales
7.5.2. Distributors and Dealers
7.5.3. Online Retail
7.5.4. Aftermarket Service Providers
8. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Single Compressor
8.1.2. Dual Compressor
8.1.3. Multi Compressor
8.1.4. Modular
8.1.5. Customized
8.2. Market Analysis, Insights and Forecast - by Capacity
8.2.1. Less than 250 Liters
8.2.2. 250-500 Liters
8.2.3. Above 500 Liters
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Household
8.3.2. Commercial
8.3.3. Industrial
8.3.4. Medical
8.3.5. Food Service
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Residential Users
8.4.2. Retail and Supermarkets
8.4.3. Healthcare Facilities
8.4.4. Food Processing Industries
8.4.5. Hospitality and Restaurants
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Direct Sales
8.5.2. Distributors and Dealers
8.5.3. Online Retail
8.5.4. Aftermarket Service Providers
9. North America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Single Compressor
9.1.2. Dual Compressor
9.1.3. Multi Compressor
9.1.4. Modular
9.1.5. Customized
9.2. Market Analysis, Insights and Forecast - by Capacity
9.2.1. Less than 250 Liters
9.2.2. 250-500 Liters
9.2.3. Above 500 Liters
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Household
9.3.2. Commercial
9.3.3. Industrial
9.3.4. Medical
9.3.5. Food Service
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Residential Users
9.4.2. Retail and Supermarkets
9.4.3. Healthcare Facilities
9.4.4. Food Processing Industries
9.4.5. Hospitality and Restaurants
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Direct Sales
9.5.2. Distributors and Dealers
9.5.3. Online Retail
9.5.4. Aftermarket Service Providers
10. Europe Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Single Compressor
10.1.2. Dual Compressor
10.1.3. Multi Compressor
10.1.4. Modular
10.1.5. Customized
10.2. Market Analysis, Insights and Forecast - by Capacity
10.2.1. Less than 250 Liters
10.2.2. 250-500 Liters
10.2.3. Above 500 Liters
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Household
10.3.2. Commercial
10.3.3. Industrial
10.3.4. Medical
10.3.5. Food Service
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Residential Users
10.4.2. Retail and Supermarkets
10.4.3. Healthcare Facilities
10.4.4. Food Processing Industries
10.4.5. Hospitality and Restaurants
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Direct Sales
10.5.2. Distributors and Dealers
10.5.3. Online Retail
10.5.4. Aftermarket Service Providers
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Embraco
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Frigoglass
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Liebherr
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Whirlpool Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Carrier Commercial Refrigeration
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Danfoss
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Tecumseh Products Company
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Frost-Trol
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Midea Group
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Gree Electric Appliances
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Electrolux AB
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Haier Group
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Arneg Group
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Infrico
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Hussmann Corporation
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Vendo
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Blue Star Limited
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. True Manufacturing Company
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Panasonic Corporation
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Mitsubishi Electric Corporation
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Samsung Electronics
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Bosch Thermotechnology
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. Whynter LLC
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. SolarCool
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. SolCool Technologies
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Solar Direct Drive Combined Freezers Industry Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue (Million), by Type 2026 & 2034
Figure 3: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Type 2026 & 2034
Figure 4: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue (Million), by Capacity 2026 & 2034
Figure 5: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Capacity 2026 & 2034
Figure 6: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue (Million), by Application 2026 & 2034
Figure 7: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Application 2026 & 2034
Figure 8: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue (Million), by End User 2026 & 2034
Figure 9: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Share (%), by End User 2026 & 2034
Figure 10: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue (Million), by Distribution Channel 2026 & 2034
Figure 11: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue (Million), by Country 2026 & 2034
Figure 13: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Country 2026 & 2034
Figure 14: Latin America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Type 2026 & 2034
Figure 15: Latin America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Type 2026 & 2034
Figure 16: Latin America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Capacity 2026 & 2034
Figure 17: Latin America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Capacity 2026 & 2034
Figure 18: Latin America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Application 2026 & 2034
Figure 19: Latin America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Application 2026 & 2034
Figure 20: Latin America Solar Direct Drive Combined Freezers Industry Revenue (Million), by End User 2026 & 2034
Figure 21: Latin America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by End User 2026 & 2034
Figure 22: Latin America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Distribution Channel 2026 & 2034
Figure 23: Latin America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 24: Latin America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Country 2026 & 2034
Figure 25: Latin America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue (Million), by Type 2026 & 2034
Figure 27: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Type 2026 & 2034
Figure 28: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue (Million), by Capacity 2026 & 2034
Figure 29: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Capacity 2026 & 2034
Figure 30: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue (Million), by Application 2026 & 2034
Figure 31: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Application 2026 & 2034
Figure 32: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue (Million), by End User 2026 & 2034
Figure 33: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Share (%), by End User 2026 & 2034
Figure 34: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue (Million), by Distribution Channel 2026 & 2034
Figure 35: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 36: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue (Million), by Country 2026 & 2034
Figure 37: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Country 2026 & 2034
Figure 38: North America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Type 2026 & 2034
Figure 39: North America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Type 2026 & 2034
Figure 40: North America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Capacity 2026 & 2034
Figure 41: North America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Capacity 2026 & 2034
Figure 42: North America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Application 2026 & 2034
Figure 43: North America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Application 2026 & 2034
Figure 44: North America Solar Direct Drive Combined Freezers Industry Revenue (Million), by End User 2026 & 2034
Figure 45: North America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by End User 2026 & 2034
Figure 46: North America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Distribution Channel 2026 & 2034
Figure 47: North America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 48: North America Solar Direct Drive Combined Freezers Industry Revenue (Million), by Country 2026 & 2034
Figure 49: North America Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Country 2026 & 2034
Figure 50: Europe Solar Direct Drive Combined Freezers Industry Revenue (Million), by Type 2026 & 2034
Figure 51: Europe Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Type 2026 & 2034
Figure 52: Europe Solar Direct Drive Combined Freezers Industry Revenue (Million), by Capacity 2026 & 2034
Figure 53: Europe Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Capacity 2026 & 2034
Figure 54: Europe Solar Direct Drive Combined Freezers Industry Revenue (Million), by Application 2026 & 2034
Figure 55: Europe Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Application 2026 & 2034
Figure 56: Europe Solar Direct Drive Combined Freezers Industry Revenue (Million), by End User 2026 & 2034
Figure 57: Europe Solar Direct Drive Combined Freezers Industry Revenue Share (%), by End User 2026 & 2034
Figure 58: Europe Solar Direct Drive Combined Freezers Industry Revenue (Million), by Distribution Channel 2026 & 2034
Figure 59: Europe Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 60: Europe Solar Direct Drive Combined Freezers Industry Revenue (Million), by Country 2026 & 2034
Figure 61: Europe Solar Direct Drive Combined Freezers Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Type 2020 & 2034
Table 2: Global Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Capacity 2020 & 2034
Table 3: Global Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Application 2020 & 2034
Table 4: Global Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by End User 2020 & 2034
Table 5: Global Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 6: Global Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Region 2020 & 2034
Table 7: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Type 2020 & 2034
Table 8: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Capacity 2020 & 2034
Table 9: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Application 2020 & 2034
Table 10: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by End User 2020 & 2034
Table 11: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 12: Asia Pacific Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Country 2020 & 2034
Table 13: China Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 14: India Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 15: Japan Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 16: Indonesia Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 17: Bangladesh Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 18: Latin America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Type 2020 & 2034
Table 19: Latin America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Capacity 2020 & 2034
Table 20: Latin America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Application 2020 & 2034
Table 21: Latin America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by End User 2020 & 2034
Table 22: Latin America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 23: Latin America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Country 2020 & 2034
Table 24: Brazil Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 25: Argentina Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 26: Chile Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 27: Peru Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 28: Colombia Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 29: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Type 2020 & 2034
Table 30: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Capacity 2020 & 2034
Table 31: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by End User 2020 & 2034
Table 33: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 34: Middle East & Africa Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Country 2020 & 2034
Table 35: Nigeria Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 36: Kenya Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 37: Ethiopia Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 38: South Africa Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 39: North America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Type 2020 & 2034
Table 40: North America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Capacity 2020 & 2034
Table 41: North America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Application 2020 & 2034
Table 42: North America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by End User 2020 & 2034
Table 43: North America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 44: North America Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Country 2020 & 2034
Table 45: United States Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 46: Canada Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 47: Europe Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Type 2020 & 2034
Table 48: Europe Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Capacity 2020 & 2034
Table 49: Europe Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Application 2020 & 2034
Table 50: Europe Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by End User 2020 & 2034
Table 51: Europe Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 52: Europe Solar Direct Drive Combined Freezers Industry Revenue Million Forecast, by Country 2020 & 2034
Table 53: Germany Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 54: France Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 55: UK Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Table 56: Italy Solar Direct Drive Combined Freezers Industry Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the market size of the Solar Direct Drive Combined Freezers Industry?
The global market was valued at USD 466.2 million in 2025 and is projected to reach USD 1,235 million by 2034, growing at a CAGR of 11.0%. This growth is driven by expanding off-grid healthcare infrastructure and food security initiatives in Asia-Pacific and Latin America.
2Which region dominates the Solar Direct Drive Combined Freezers Industry?
Asia-Pacific leads with a 45% share of global revenue, supported by large-scale immunization cold chain programs in India and China. Latin America is the fastest-growing region at 12.1% CAGR, driven by government incentives and rural electrification efforts.
3Who are the leading companies in the Solar Direct Drive Combined Freezers Industry?
Key players include Embraco, Danfoss, Liebherr, Haier, Midea, and specialized solar refrigeration firms like SolarCool and SolCool Technologies. These companies compete on compressor efficiency, WHO PQS compliance, and local assembly strategies.
4What are the main applications driving demand for solar direct drive combined freezers?
Medical applications, including hospitals, blood banks, and vaccine storage, account for 49.6% of demand. Commercial food retail and household preservation follow, driven by the need for reliable cooling in regions with less than 8 hours of daily grid electricity.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 142 in-depth interviews with senior executives across the solar direct drive combined freezer value chain, including compressor OEMs, system integrators, solar array suppliers, and distributors.
Interviewed stakeholders such as Procurement Directors at health ministries, Cold Chain Logistics Managers at NGOs, and Technical Directors at refrigeration manufacturers to capture demand-side and supply-side perspectives.
Primary research accounted for 70–80% of total research effort, ensuring deep market intimacy and validation of quantitative models.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
32%
Cold Chain Logistics Manager
26%
Technical Director / R&D Head
24%
Government Health Program Officer
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Compressor and Component OEMs
30%
System Integrators and Freezer Assemblers
28%
Solar Array and Balance-of-System Suppliers
18%
Distributors and Procurement Agencies
16%
Service and Maintenance Providers
8%
Secondary Research & Industry Benchmarking
Analyzed official trade data from UN Comtrade (HS 8418.69) and national customs databases to map import/export flows and pricing trends.
Benchmarked performance specifications against WHO PQS prequalification standards and UNICEF Supply Division tender documents for solar direct-drive refrigeration systems.
Supplemented with financial databases including Bloomberg, Factiva, Hoovers, and PitchBook for company-level revenue and investment tracking.
Applied both top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up model utilized quantitative metrics including: (1) number of unelectrified health facilities by country (source: WHO/World Bank), (2) average refrigeration capacity per facility (liters), (3) replacement cycle (10 years), and (4) unit price per liter from tender data.
Top-down model cross-referenced global cold chain equipment spending with solar share allocation, derived from multilateral procurement records.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%, achieved through triangulation of primary interview data, official trade statistics, and field audit reports.
All reports are updated to the date of purchase, incorporating the latest tender awards and regulatory changes.
Quality assurance conducted by a senior analyst panel, with outlier detection and reconciliation against historical forecasts.
Related Reports
Discover lithium-ion battery market opportunities: USD 88.6B in 2025 to USD 350.5B by 2035 at 14.4% CAGR. Explore LFP, ESS, and regional growth.
Nov 2026|254 pages
$2900.00
The methane gas detectors market was valued at USD 1.9 billion in 2025 and is projected to reach USD 3.4 billion by 2035, growing at a 6.0% CAGR.
Nov 2026|188 pages
$2900.00
Pocket type NiCd battery market to reach US$ 1.65 Bn by 2034 from US$ 1.36 Bn in 2025, at 2.2% CAGR. Drivers, trends, and regional insights.
Nov 2026|181 pages
$2900.00
Digital transformation in oil and gas market to hit $371.56B by 2034 at 17% CAGR. Explore AI, IoT, digital twins, and regional insights driving growth.