1What is the current size of the lithium-ion battery market?
The global lithium-ion battery market was valued at USD 88.6 billion in 2025 and is projected to reach USD 104.1 billion in 2026, according to our proprietary research.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Opportunities in Lithium-Ion Batteries Market
 by Chemistry (NMC, LFP, LTO, NCA), by Form Factor (Cylindrical, Pouch, Prismatic), by Power Capacity (3, 000-10, 000 mAh, 10, 000-60, 000 mAh, Above 60, 000 mAh), by End-Use (Automotive, Stationary Energy Storage, Consumer Electronics, Industrial), by Component (Cathode, Anode, Electrolyte, Separator), by Asia Pacific (China, Japan, South Korea, India), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Nordic Countries), by Latin America (Brazil, Chile), by Middle East & Africa (UAE, South Africa) Forecast 2026-2034
Research Analyst


 Related Reports

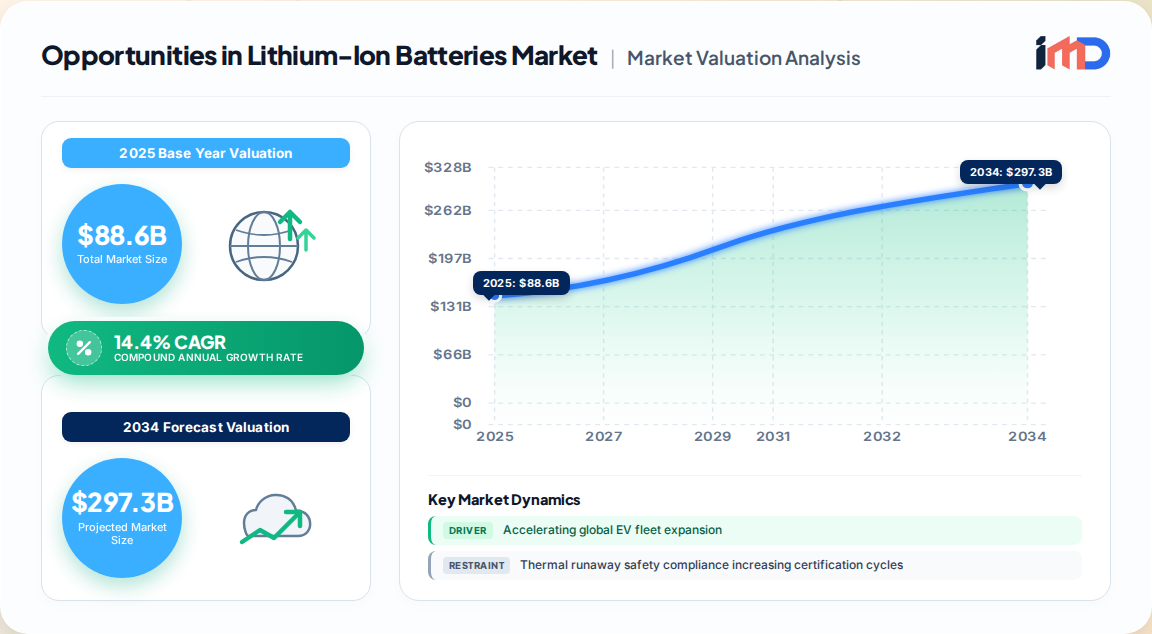
The global lithium-ion battery market represents one of the most significant industrial opportunities of the coming decade. Our proprietary primary research estimates the market at USD 88.6 billion in 2025, expanding to USD 104.1 billion in 2026 and reaching USD 350.5 billion by 2035, reflecting a 14.4% CAGR over the forecast period. This growth is not merely a continuation of historical trends but a structural re-rating of the industry driven by twin demand engines: electric vehicle (EV) fleet expansion and grid-scale energy storage buildout.
The opportunity set is widening beyond traditional automotive applications. Stationary energy storage, emerging as the fastest-growing end-use segment at a 28.9% CAGR, is creating a parallel demand channel that decouples battery demand from consumer electronics cycles and provides long-horizon utility contracts. Meanwhile, lithium iron phosphate (LFP) chemistry has achieved cost parity and is democratizing access to battery technology across price-sensitive markets, from entry-level EVs in India to utility-scale storage in the United States.
For investors and industry participants, the question is no longer whether lithium-ion batteries will dominate energy storage, but where the most attractive value pools will emerge. This report identifies those pools through rigorous analysis of demand drivers, supply chain dynamics, and regional competitive positioning.
The lithium-ion battery market is shaped by several powerful forces. Understanding their interaction is essential for strategic planning.
| Driver | Evidence Signal | Market-Demand Implication |
|---|---|---|
| Accelerating global EV fleet expansion | Global EV sales reached 17 million units in 2024 (IEA) | Scales procurement volume for automotive-grade cells and extends multi-year OEM commitments across LFP and NMC chemistries |
| Grid-scale energy storage capacity buildout | Tripling renewable capacity by 2030 requires 1,500 GW of battery storage (IEA) | Accelerates utility-scale BESS procurement, diversifying demand beyond automotive and creating long-horizon contracts |
| LFP chemistry cost parity and cross-application adoption | Iron-phosphate cathode eliminates cobalt dependency and extends cycle life | Compresses unit economics, broadens accessible markets, and diversifies procurement beyond NMC-dominant segments |
These drivers are reinforcing rather than independent. EV demand provides a durable utilization base for cell manufacturers, while stationary storage adds a distinct demand channel that values large-format LFP cells for their cost and safety attributes. The result is a more resilient demand profile than the industry has historically experienced.
However, three significant restraints temper the growth trajectory:
The lithium-ion battery market is not monolithic. Opportunity varies significantly by chemistry, form factor, power capacity, and end-use industry. Our segmentation analysis reveals where growth will be concentrated.
Asia Pacific is the undisputed center of gravity for lithium-ion battery production and demand, accounting for 57.65% of market revenue in 2026 and forecast to grow at a 30.2% CAGR over 2027–2032. China alone represents the largest manufacturing base, supported by industrial policies such as "Made in China 2025" and subsequent new-battery industry agendas that link manufacturing clusters to downstream applications.
However, opportunity is not confined to Asia Pacific. The United States is witnessing rapid rollout of utility-scale battery energy storage procurements, exemplified by Plus Power's 175 MW/350 MWh Cross Town facility in Maine (operational February 2026) and PacifiCorp's resource plan identifying 1,265 MW of 4-hour lithium-ion storage required for Oregon by 2030. Europe is seeing niche but high-value opportunities in maritime battery adoption (driven by IMO GHG targets) and stationary data-center backup migration from VRLA to lithium-ion in Nordic countries.
Latin America is forecast to be the fastest-growing region, albeit from a smaller base, as EV adoption accelerates and grid storage projects materialize. The Middle East & Africa region presents long-term opportunities linked to renewable energy integration and electrification.
The lithium-ion battery market is concentrated, with the top five players — CATL, LG Energy Solution, BYD, Samsung SDI, and Panasonic Energy — collectively holding 60.1% market share in 2025. CATL alone commanded over 25.1% share, underscoring its scale and technology leadership.
Recent industry developments highlight the strategic priorities of leading players:
The lithium-ion battery value chain spans raw material extraction, cell component manufacturing, cell assembly, module and pack integration, and end-of-life recycling. Each stage presents distinct opportunities:
Our analysis identifies several white spaces where demand is emerging faster than supply chains can respond:
For OEMs and utility procurers, battery sourcing strategy has become a board-level concern. Key considerations include:
The market opportunity is clear: USD 350.5 billion by 2035 awaits those who can navigate the restraints, capitalize on LFP and storage growth, and secure positions in the high-growth segments and regions identified in this report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.4% from 2020-2034 |
| Segmentation |
|
By Power Capacity
By End-Use
By Component
| By Geography |
|
The global lithium-ion battery market was valued at USD 88.6 billion in 2025 and is projected to reach USD 104.1 billion in 2026, according to our proprietary research.
The market is expected to grow at a CAGR of 14.4% from 2026 to 2035, reaching USD 350.5 billion by 2035.
Asia Pacific is the largest market, accounting for 57.65% of global revenue in 2026, and is also forecast to be the fastest-growing region at a 30.2% CAGR over 2027-2032.
Key opportunities include stationary energy storage (forecast 28.9% CAGR), LFP chemistry adoption (23% CAGR), and large-format cells above 60,000 mAh (27.4% CAGR), driven by EV and grid-storage demand.
The top five players are CATL, LG Energy Solution, BYD, Samsung SDI, and Panasonic Energy, collectively holding 60.1% market share in 2025. CATL leads with over 25.1% share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Battery Engineering Manager | 25% |
| Strategy/Planning Head | 20% |
| Supply Chain Manager | 15% |
| Regulatory Compliance Officer | 10% |
| Company Type | Representation (%) |
|---|---|
| Cell Manufacturers | 35% |
| Battery Pack Integrators | 20% |
| Automotive OEMs | 20% |
| Utility/Grid Storage Developers | 15% |
| Raw Material Suppliers | 10% |