Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Digital Transformation in Oil and Gas Market to 2034
Digital Transformation in Oil and Gas Market
Energy & Power / MARKET REPORT
Digital Transformation in Oil and Gas Market | Insight Market Data
Digital Transformation in Oil and Gas Market by Technology (IoT, Big data and analytics, Cloud computing, Artificial intelligence, Digital twins, Blockchain, Robotics & Automation, Others), by Sector (Upstream, Midstream, Downstream), by Component (Software, Hardware, Services), by Deployment Mode (On-premises, Cloud, Hybrid, Edge-based), by Application (Exploration, Drilling, Production, Refining, Transportation, Asset Management, Safety & Compliance, Others), by North America (US, Canada, Mexico), by Europe (Germany, UK, France), by Asia-Pacific (China, Japan, India), by Middle East & Africa (Saudi Arabia, UAE, South Africa), by South America (Brazil, Argentina) Forecast 2026-2034
India renewable energy market is projected to reach USD 159.81 Billion by 2035, growing at a CAGR of 7.36% from 2026 to 2035, driven by solar and wind.
The Semi-Submersible Drilling Rig Industry market was valued at USD 24.6 Billion in 2025 and is projected to reach USD 41.2 Billion by 2033, growing at a 6.7% CAGR.
Nov 2026|275 pages
$2900.00
West Africa refined petroleum products market to reach USD 78.62 billion by 2031 at 4.88% CAGR. Dangote, subsidy reform and LPG drive demand.
Nov 2026|251 pages
$2900.00
Marine solid state circuit breaker market to reach USD 1.24 Billion by 2035 at 9.2% CAGR, driven by vessel electrification and DC grid adoption.
Executive Overview: A Structural Shift Toward Data-Centric Energy Operations
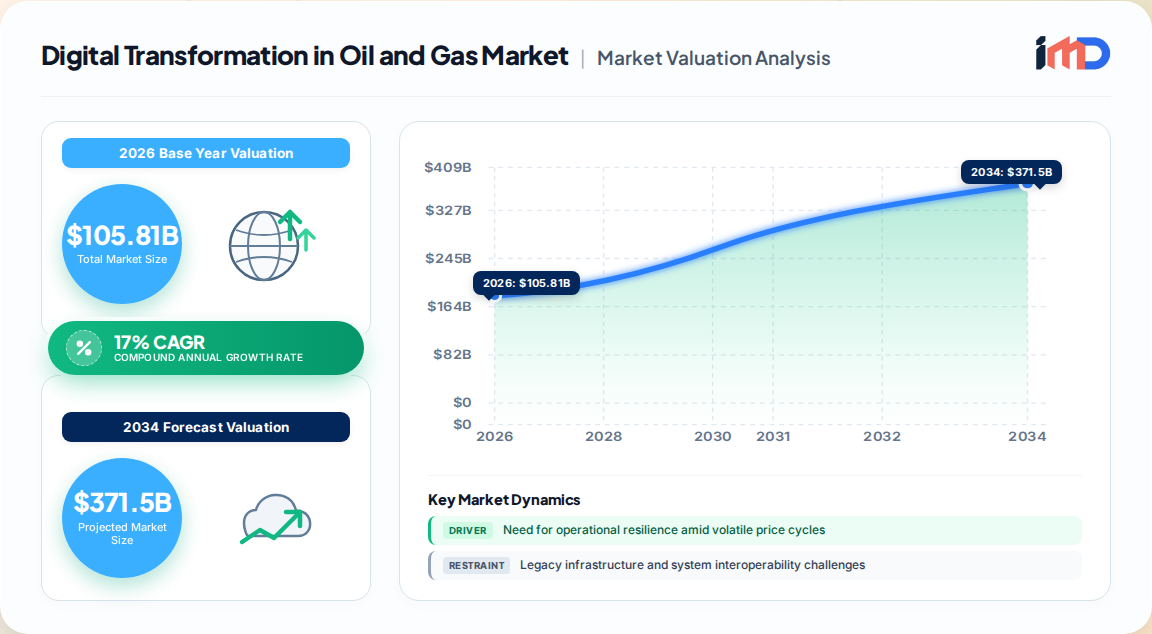
The digital transformation in oil and gas market is valued at USD 105.81 billion in 2026 and is projected to reach USD 371.56 billion by 2034, expanding at a 17% CAGR. This growth reflects a fundamental re-architecture of how hydrocarbons are explored, produced, moved, refined, and monetized.
Digital Transformation in Oil and Gas Market Market Size (In Billion)
250.0B
200.0B
150.0B
100.0B
50.0B
0
90.44 B
2025
105.8 B
2026
123.8 B
2027
144.8 B
2028
169.5 B
2029
198.3 B
2030
232.0 B
2031
Our proprietary primary research indicates that digital transformation has moved beyond pilot-stage experimentation into enterprise-scale deployment. Operators are no longer asking whether to digitalize, but how quickly they can industrialize AI, industrial IoT (IIoT), cloud-native data platforms, and digital twins across remote and capital-intensive assets.
Operational resilience is the top board-level driver, as commodity price volatility forces operators to compress breakeven costs and reduce non-productive time.
Sustainability compliance, particularly methane measurement and emissions reporting, is creating a second wave of digital spending across both OECD and emerging markets.
Agentic AI and autonomous decision intelligence are emerging as the next efficiency frontier, moving beyond descriptive analytics to closed-loop operational control.
Key Market Drivers & Restraints
Drivers
Volatile price cycles demand leaner operations. Crude oil prices have fluctuated by more than 50% between 2022 and 2023, compelling operators to adopt predictive maintenance and remote monitoring. Our interviews suggest predictive analytics can cut maintenance costs by 25% and extend equipment life by 20-40%.
Carbon and methane regulation. The oil and gas sector accounts for nearly 15% of global energy-related greenhouse gas emissions. Regulatory frameworks, including the EU methane framework, are forcing granular asset-level monitoring, driving adoption of IoT sensors and satellite-based leak detection.
AI-driven exploration and drilling efficiency. Machine learning is compressing subsurface modeling cycles from months to weeks. In one primary case, operators using AI-driven seismic analysis identified viable hydrocarbon deposits over 30% faster than traditional methods.
Restraints
Legacy infrastructure and technical debt. Decades-old SCADA and OT systems create interoperability barriers. Retrofitting legacy fields often requires extensive downtime and custom middleware, slowing brownfield digitalization.
Cybersecurity vulnerabilities. The energy sector experienced a 50% increase in ransomware attacks between 2022 and 2023, targeting SCADA and distributed control systems. This remains a board-level adoption barrier.
Talent shortage. A persistent gap in data science, industrial cybersecurity, and OT-IT convergence skills limits the speed at which digital initiatives can scale.
Segmentation Analysis: Technology, Sector, and Deployment
By Technology
IoT formed the telemetry backbone, valued at USD 20.85 billion in 2024, and remains foundational for real-time asset monitoring.
Big data and analytics and cloud computing commanded the largest technology share at 34% in 2025, enabling elastic compute for reservoir simulation and enterprise data integration.
Artificial intelligence is the fastest-growing technology segment, projected at a 14.6% CAGR, driven by predictive maintenance, autonomous drilling, and generative AI for engineering document retrieval.
Digital twins are transitioning from static asset models to living virtual replicas integrating real-time sensor feeds and physics-based simulation.
By Sector
Upstream accounted for 46.3% of spending in 2025, led by AI-enabled reservoir characterization and autonomous drilling pilots.
Downstream remains the largest revenue contributor by digital spend in refining and petrochemicals, with a 12.23% CAGR forecast as smart refineries scale.
Midstream is the fastest-rising sector at 12.3% CAGR, driven by pipeline integrity monitoring and logistics optimization.
By Deployment Mode
On-premise infrastructure still represented 61.54% of market size in 2025 due to security and latency requirements in OT environments.
Cloud deployments are growing at an 11.91% CAGR, supported by hybrid architectures that keep latency-sensitive logic on-premise while exporting analytics workloads.
Regional Outlook: North America Leads, Asia-Pacific Accelerates
North America held 33.53% of global digital transformation spending in 2025, driven by shale operators' data-driven completion designs and offshore automation. Asia-Pacific is the fastest-growing region at a 12.68% CAGR, as national oil companies modernize infrastructure to meet LNG export schedules and decarbonization targets.
Digital Transformation in Oil and Gas Market Regional Market Share
Digital twins, autonomous well control, large-scale predictive simulation
South America
~5%
Emerging
Deepwater subsea automation, offshore safety systems
Middle East pioneers large-scale predictive simulation and digital twin deployment for mature basins, with national oil companies using AI to maximize recovery.
Europe leads in ESG-linked digital programs, linking production data to carbon accounting and TCFD-aligned reporting.
Asia-Pacific is adopting secure OT networks and zero-trust architectures for refineries and LNG hubs, with China, Japan, and India as primary growth engines.
Competitive Landscape and Strategic Developments
The market is highly competitive and fragmented, featuring industrial automation leaders, IT giants, and oilfield service majors. Companies are pursuing AI research partnerships, cybersecurity collaborations, and digital platform rollouts.
IBM, Microsoft, SAP, Oracle, and Accenture are driving cloud, AI, and enterprise data fabric deployments.
SLB, Halliburton, and Baker Hughes are scaling AI/ML and big data analytics from pilot to production in drilling and completions.
Siemens Energy, Schneider Electric, ABB, and Rockwell Automation provide secure OT networks and zero-trust architectures for refineries and LNG hubs.
Honeywell and Emerson lead in process automation and safety systems for offshore platforms and subsea operations.
Recent Developments
2025: Saudi Aramco's AI infrastructure, recognized by the World Economic Forum's Global Lighthouse Network, cut greenhouse-gas intensity at Yanbu Refinery by 23% and maintenance cost at Khurais by 30%.
2025: SLB and Equinor demonstrated autonomous directional drilling off Brazil, trimming drilling duration by 15%.
2024: ADNOC, with Shell downstream operations, deployed AI for more than 120 drilling rigs, cutting engineering effort by 30-40% and saving up to two days of rig shutdowns.
Value Chain Analysis: From Sensor to Strategic Decision
The digital transformation value chain spans hardware, software, services, and integrated platforms.
Sensing and data acquisition: IIoT sensors, drones, and edge computing devices capture real-time data from wellheads, pipelines, and refineries.
Connectivity and infrastructure: Secure OT networks, 5G, and satellite links transmit data to edge servers and cloud platforms.
Data integration and analytics: Cloud-native data fabrics unify operational and enterprise streams. AI and machine learning models convert data into predictive insights.
Application and decision support: Digital twins, predictive maintenance, and autonomous control systems translate insights into operational actions.
Services and change management: Integration, cybersecurity, and workforce reskilling services are increasingly critical as wallet share shifts toward services, growing at 12.62% CAGR.
Import/Export and Supplier Dynamics
Digital transformation solutions in oil and gas are not traditional traded commodities, but cross-border supply dynamics are significant for hardware (sensors, edge devices) and software licensing.
Hardware supply chains for IIoT sensors, drones, and edge computing are concentrated in Asia-Pacific manufacturing hubs, with China, Taiwan, and South Korea as key exporters. Trade friction and export controls on advanced semiconductors pose supply risks.
Software and cloud services are largely delivered through global platforms, but data sovereignty rules are pushing operators toward federated learning and localized data centers.
Services procurement is shifting toward managed services and outcome-based contracts, with system integrators and consultancies competing for wallet share.
Strategic White-Space Analysis
Our primary research identifies three underpenetrated opportunity areas:
AI-powered predictive maintenance for aging assets. Over 45% of U.S. oil refineries are more than 40 years old, creating a large addressable market for condition-based monitoring and failure prediction.
Methane monitoring and emissions reporting. Regulatory tailwinds in Europe and North America are creating demand for connected sensors, satellite surveillance, and automated reporting platforms.
Digital twins for midstream and downstream. Midstream operators are lagging upstream in digital adoption, but pipeline integrity and logistics optimization represent high-ROI use cases.
Ansoff Matrix Analysis
Strategy
Description
Examples
Market Penetration
Expand digital solutions in existing upstream assets
Scaling predictive maintenance across mature fields
Market Development
Enter midstream and downstream digital markets
Digital twins for pipeline networks and smart refineries
Product Development
Launch AI-driven autonomous operations platforms
Agentic AI for closed-loop drilling control
Diversification
Offer cross-industry digital solutions
Adapting oilfield IoT for geothermal and carbon capture
Research Methodology
Primary Research
70-80% of data collected through primary research, including structured interviews with C-level executives, digital transformation officers, and OT engineers across upstream, midstream, and downstream operators.
Interviews conducted with 4-5 specific company types: integrated oil and gas majors, national oil companies (NOCs), oilfield service providers, industrial automation and software vendors, and engineering, procurement, and construction (EPC) contractors.
Stakeholder job titles interviewed include Chief Digital Officer, VP of Operations, Head of OT Cybersecurity, and Digital Transformation Program Director.
Primary research validated through consultations with recognized industry associations, including the American Petroleum Institute (API), the International Association of Oil & Gas Producers (IOGP), and the World Economic Forum's Global Lighthouse Network.
Secondary Research & Industry Benchmarking
20-30% of data derived from secondary research, benchmarking against official multilateral sources such as the OECD, International Energy Agency (IEA), U.S. Energy Information Administration (EIA), and International Renewable Energy Agency (IRENA).
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook used for company-level analysis and investment tracking.
All sources are official .gov, .org, or recognized non-profit trade associations; no commercial market research firms are cited.
Demand Modeling & Market Estimation
Simultaneous top-down and bottom-up methodologies applied, validated via multi-level data triangulation.
Bottom-up market sizing based on specific quantitative metrics: number of active drilling rigs, refinery capacity (barrels per day), pipeline miles under digital monitoring, and average digital spend per asset.
Top-down modeling uses regional capex allocation for digital initiatives, cross-checked against vendor revenue disclosures and procurement data.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85-90%, with all figures updated to the date of purchase.
Multi-level triangulation across primary interviews, secondary benchmarks, and financial databases ensures consistency.
Every report undergoes a three-stage quality review: data validation, analytical review, and editorial compliance.
This report is based on proprietary research and expert interviews. All market sizes and forecasts represent our independent analysis and are provided for strategic planning purposes.
Digital Transformation in Oil and Gas Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Digital Transformation in Oil and Gas Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 17% from 2020-2034
Segmentation
By Technology
IoT
Big data and analytics
Cloud computing
Artificial intelligence
Digital twins
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Need for operational resilience amid volatile price cycles
3.1.2. Regulatory and investor pressure to reduce carbon emissions
3.1.3. AI and machine learning adoption for predictive maintenance and autonomous operations
3.1.4. Industrial IoT and edge computing for real-time asset monitoring
3.2. Market Trends
3.2.1. Institutionalization of agentic AI and autonomous decision intelligence
3.2.2. Shift from static asset models to living digital twins with real-time sensor feeds
3.2.3. Cloud-native architectures and zero-trust security in OT environments
3.2.4. Blockchain for supply chain verification and computer vision for automated inspections
3.3. Market Restrains
3.3.1. Legacy infrastructure and system interoperability challenges
3.3.2. Cybersecurity vulnerabilities in expanding digital attack surfaces
3.3.3. Talent shortage in data science and industrial cybersecurity
3.3.4. Resistance to cultural and organizational change
3.4. Market Restraints
Blockchain
Robotics & Automation
Others
By Sector
Upstream
Midstream
Downstream
By Component
Software
Hardware
Services
By Deployment Mode
On-premises
Cloud
Hybrid
Edge-based
By Application
Exploration
Drilling
Production
Refining
Transportation
Asset Management
Safety & Compliance
Others
By Geography
North America
US
Canada
Mexico
Europe
Germany
UK
France
Asia-Pacific
China
Japan
India
Middle East & Africa
Saudi Arabia
UAE
South Africa
South America
Brazil
Argentina
3.4.1. Legacy infrastructure and system interoperability challenges
3.4.2. Cybersecurity vulnerabilities in expanding digital attack surfaces
3.4.3. Talent shortage in data science and industrial cybersecurity
3.4.4. Resistance to cultural and organizational change
3.5. Market Challenges
3.5.1. Integrating legacy OT with modern cloud and analytics layers
3.5.2. Securing interconnected IT/OT assets against ransomware
3.5.3. Upskilling workforce for digital operating models
3.5.4. Data sovereignty and federated learning constraints
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Technology
5.1.1. IoT
5.1.2. Big data and analytics
5.1.3. Cloud computing
5.1.4. Artificial intelligence
5.1.5. Digital twins
5.1.6. Blockchain
5.1.7. Robotics & Automation
5.1.8. Others
5.2. Market Analysis, Insights and Forecast - by Sector
5.2.1. Upstream
5.2.2. Midstream
5.2.3. Downstream
5.3. Market Analysis, Insights and Forecast - by Component
5.3.1. Software
5.3.2. Hardware
5.3.3. Services
5.4. Market Analysis, Insights and Forecast - by Deployment Mode
5.4.1. On-premises
5.4.2. Cloud
5.4.3. Hybrid
5.4.4. Edge-based
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Exploration
5.5.2. Drilling
5.5.3. Production
5.5.4. Refining
5.5.5. Transportation
5.5.6. Asset Management
5.5.7. Safety & Compliance
5.5.8. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia-Pacific
5.6.4. Middle East & Africa
5.6.5. South America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Technology
6.1.1. IoT
6.1.2. Big data and analytics
6.1.3. Cloud computing
6.1.4. Artificial intelligence
6.1.5. Digital twins
6.1.6. Blockchain
6.1.7. Robotics & Automation
6.1.8. Others
6.2. Market Analysis, Insights and Forecast - by Sector
6.2.1. Upstream
6.2.2. Midstream
6.2.3. Downstream
6.3. Market Analysis, Insights and Forecast - by Component
6.3.1. Software
6.3.2. Hardware
6.3.3. Services
6.4. Market Analysis, Insights and Forecast - by Deployment Mode
6.4.1. On-premises
6.4.2. Cloud
6.4.3. Hybrid
6.4.4. Edge-based
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Exploration
6.5.2. Drilling
6.5.3. Production
6.5.4. Refining
6.5.5. Transportation
6.5.6. Asset Management
6.5.7. Safety & Compliance
6.5.8. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Technology
7.1.1. IoT
7.1.2. Big data and analytics
7.1.3. Cloud computing
7.1.4. Artificial intelligence
7.1.5. Digital twins
7.1.6. Blockchain
7.1.7. Robotics & Automation
7.1.8. Others
7.2. Market Analysis, Insights and Forecast - by Sector
7.2.1. Upstream
7.2.2. Midstream
7.2.3. Downstream
7.3. Market Analysis, Insights and Forecast - by Component
7.3.1. Software
7.3.2. Hardware
7.3.3. Services
7.4. Market Analysis, Insights and Forecast - by Deployment Mode
7.4.1. On-premises
7.4.2. Cloud
7.4.3. Hybrid
7.4.4. Edge-based
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Exploration
7.5.2. Drilling
7.5.3. Production
7.5.4. Refining
7.5.5. Transportation
7.5.6. Asset Management
7.5.7. Safety & Compliance
7.5.8. Others
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Technology
8.1.1. IoT
8.1.2. Big data and analytics
8.1.3. Cloud computing
8.1.4. Artificial intelligence
8.1.5. Digital twins
8.1.6. Blockchain
8.1.7. Robotics & Automation
8.1.8. Others
8.2. Market Analysis, Insights and Forecast - by Sector
8.2.1. Upstream
8.2.2. Midstream
8.2.3. Downstream
8.3. Market Analysis, Insights and Forecast - by Component
8.3.1. Software
8.3.2. Hardware
8.3.3. Services
8.4. Market Analysis, Insights and Forecast - by Deployment Mode
8.4.1. On-premises
8.4.2. Cloud
8.4.3. Hybrid
8.4.4. Edge-based
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Exploration
8.5.2. Drilling
8.5.3. Production
8.5.4. Refining
8.5.5. Transportation
8.5.6. Asset Management
8.5.7. Safety & Compliance
8.5.8. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Technology
9.1.1. IoT
9.1.2. Big data and analytics
9.1.3. Cloud computing
9.1.4. Artificial intelligence
9.1.5. Digital twins
9.1.6. Blockchain
9.1.7. Robotics & Automation
9.1.8. Others
9.2. Market Analysis, Insights and Forecast - by Sector
9.2.1. Upstream
9.2.2. Midstream
9.2.3. Downstream
9.3. Market Analysis, Insights and Forecast - by Component
9.3.1. Software
9.3.2. Hardware
9.3.3. Services
9.4. Market Analysis, Insights and Forecast - by Deployment Mode
9.4.1. On-premises
9.4.2. Cloud
9.4.3. Hybrid
9.4.4. Edge-based
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Exploration
9.5.2. Drilling
9.5.3. Production
9.5.4. Refining
9.5.5. Transportation
9.5.6. Asset Management
9.5.7. Safety & Compliance
9.5.8. Others
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Technology
10.1.1. IoT
10.1.2. Big data and analytics
10.1.3. Cloud computing
10.1.4. Artificial intelligence
10.1.5. Digital twins
10.1.6. Blockchain
10.1.7. Robotics & Automation
10.1.8. Others
10.2. Market Analysis, Insights and Forecast - by Sector
10.2.1. Upstream
10.2.2. Midstream
10.2.3. Downstream
10.3. Market Analysis, Insights and Forecast - by Component
10.3.1. Software
10.3.2. Hardware
10.3.3. Services
10.4. Market Analysis, Insights and Forecast - by Deployment Mode
10.4.1. On-premises
10.4.2. Cloud
10.4.3. Hybrid
10.4.4. Edge-based
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Exploration
10.5.2. Drilling
10.5.3. Production
10.5.4. Refining
10.5.5. Transportation
10.5.6. Asset Management
10.5.7. Safety & Compliance
10.5.8. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. IBM Corporation
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Microsoft Corporation
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. SAP SE
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Oracle Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Accenture
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Cognizant Technology Solutions
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Hewlett Packard Enterprise
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. SLB
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Halliburton
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Baker Hughes
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Siemens Energy
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Schneider Electric
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Honeywell
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Emerson Electric Co.
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. ABB
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Rockwell Automation Inc.
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. General Electric Co.
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Intel Corp.
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Tata Consultancy Services Ltd.
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Teradata Corp.
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Kyndryl
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Digital Transformation in Oil and Gas Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Digital Transformation in Oil and Gas Market Revenue (Billion), by Technology 2026 & 2034
Figure 3: North America Digital Transformation in Oil and Gas Market Revenue Share (%), by Technology 2026 & 2034
Figure 4: North America Digital Transformation in Oil and Gas Market Revenue (Billion), by Sector 2026 & 2034
Figure 5: North America Digital Transformation in Oil and Gas Market Revenue Share (%), by Sector 2026 & 2034
Figure 6: North America Digital Transformation in Oil and Gas Market Revenue (Billion), by Component 2026 & 2034
Figure 7: North America Digital Transformation in Oil and Gas Market Revenue Share (%), by Component 2026 & 2034
Figure 8: North America Digital Transformation in Oil and Gas Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 9: North America Digital Transformation in Oil and Gas Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 10: North America Digital Transformation in Oil and Gas Market Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Digital Transformation in Oil and Gas Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Digital Transformation in Oil and Gas Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Digital Transformation in Oil and Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Digital Transformation in Oil and Gas Market Revenue (Billion), by Technology 2026 & 2034
Figure 15: Europe Digital Transformation in Oil and Gas Market Revenue Share (%), by Technology 2026 & 2034
Figure 16: Europe Digital Transformation in Oil and Gas Market Revenue (Billion), by Sector 2026 & 2034
Figure 17: Europe Digital Transformation in Oil and Gas Market Revenue Share (%), by Sector 2026 & 2034
Figure 18: Europe Digital Transformation in Oil and Gas Market Revenue (Billion), by Component 2026 & 2034
Figure 19: Europe Digital Transformation in Oil and Gas Market Revenue Share (%), by Component 2026 & 2034
Figure 20: Europe Digital Transformation in Oil and Gas Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 21: Europe Digital Transformation in Oil and Gas Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 22: Europe Digital Transformation in Oil and Gas Market Revenue (Billion), by Application 2026 & 2034
Figure 23: Europe Digital Transformation in Oil and Gas Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Digital Transformation in Oil and Gas Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Digital Transformation in Oil and Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue (Billion), by Technology 2026 & 2034
Figure 27: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Share (%), by Technology 2026 & 2034
Figure 28: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue (Billion), by Sector 2026 & 2034
Figure 29: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Share (%), by Sector 2026 & 2034
Figure 30: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue (Billion), by Component 2026 & 2034
Figure 31: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Share (%), by Component 2026 & 2034
Figure 32: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 33: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 34: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue (Billion), by Application 2026 & 2034
Figure 35: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Share (%), by Application 2026 & 2034
Figure 36: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue (Billion), by Technology 2026 & 2034
Figure 39: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Share (%), by Technology 2026 & 2034
Figure 40: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue (Billion), by Sector 2026 & 2034
Figure 41: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Share (%), by Sector 2026 & 2034
Figure 42: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue (Billion), by Component 2026 & 2034
Figure 43: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Share (%), by Component 2026 & 2034
Figure 44: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 45: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 46: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue (Billion), by Application 2026 & 2034
Figure 47: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Share (%), by Application 2026 & 2034
Figure 48: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Share (%), by Country 2026 & 2034
Figure 50: South America Digital Transformation in Oil and Gas Market Revenue (Billion), by Technology 2026 & 2034
Figure 51: South America Digital Transformation in Oil and Gas Market Revenue Share (%), by Technology 2026 & 2034
Figure 52: South America Digital Transformation in Oil and Gas Market Revenue (Billion), by Sector 2026 & 2034
Figure 53: South America Digital Transformation in Oil and Gas Market Revenue Share (%), by Sector 2026 & 2034
Figure 54: South America Digital Transformation in Oil and Gas Market Revenue (Billion), by Component 2026 & 2034
Figure 55: South America Digital Transformation in Oil and Gas Market Revenue Share (%), by Component 2026 & 2034
Figure 56: South America Digital Transformation in Oil and Gas Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 57: South America Digital Transformation in Oil and Gas Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 58: South America Digital Transformation in Oil and Gas Market Revenue (Billion), by Application 2026 & 2034
Figure 59: South America Digital Transformation in Oil and Gas Market Revenue Share (%), by Application 2026 & 2034
Figure 60: South America Digital Transformation in Oil and Gas Market Revenue (Billion), by Country 2026 & 2034
Figure 61: South America Digital Transformation in Oil and Gas Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 2: Global Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Sector 2020 & 2034
Table 3: Global Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Component 2020 & 2034
Table 4: Global Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 5: Global Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Global Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 8: North America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Sector 2020 & 2034
Table 9: North America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Component 2020 & 2034
Table 10: North America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 11: North America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: US Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 17: Europe Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Sector 2020 & 2034
Table 18: Europe Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Component 2020 & 2034
Table 19: Europe Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 20: Europe Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Application 2020 & 2034
Table 21: Europe Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Germany Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 26: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Sector 2020 & 2034
Table 27: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Component 2020 & 2034
Table 28: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 29: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Application 2020 & 2034
Table 30: Asia-Pacific Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Country 2020 & 2034
Table 31: China Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Japan Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: India Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 35: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Sector 2020 & 2034
Table 36: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Component 2020 & 2034
Table 37: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 38: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Application 2020 & 2034
Table 39: Middle East & Africa Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Country 2020 & 2034
Table 40: Saudi Arabia Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: UAE Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: South Africa Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: South America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 44: South America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Sector 2020 & 2034
Table 45: South America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Component 2020 & 2034
Table 46: South America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 47: South America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Application 2020 & 2034
Table 48: South America Digital Transformation in Oil and Gas Market Revenue Billion Forecast, by Country 2020 & 2034
Table 49: Brazil Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: Argentina Digital Transformation in Oil and Gas Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the digital transformation in oil and gas market?
The market is valued at USD 105.81 billion in 2026 and is projected to reach USD 371.56 billion by 2034, growing at a 17% CAGR. North America accounts for approximately 34% of global spending.
2Which technology segment is fastest-growing in digital transformation in oil and gas?
Artificial intelligence is the fastest-growing technology segment, projected at a 14.6% CAGR through 2031. IoT remains the foundational segment, valued at USD 20.85 billion in 2024.
3Which region leads the digital transformation in oil and gas market?
North America leads with 33.53% of global spending, driven by shale and offshore operations. Asia-Pacific is the fastest-growing region at a 12.68% CAGR.
4How does digital transformation improve oil and gas operations?
Digital transformation enables predictive maintenance that cuts maintenance costs by 25% and extends equipment life by 20-40%. AI-driven seismic analysis identifies hydrocarbon deposits over 30% faster.
5What are the key challenges in digital transformation in oil and gas?
Legacy infrastructure interoperability and cybersecurity vulnerabilities are the main challenges. The energy sector saw a 50% increase in ransomware attacks between 2022 and 2023.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70-80% of data collected through primary research, including structured interviews with C-level executives, digital transformation officers, and OT engineers.
Interviews conducted with integrated oil and gas majors, national oil companies, oilfield service providers, industrial automation vendors, and EPC contractors.
Stakeholder job titles interviewed include Chief Digital Officer, VP of Operations, Head of OT Cybersecurity, and Digital Transformation Program Director.
Primary research validated through consultations with the American Petroleum Institute (API), the International Association of Oil & Gas Producers (IOGP), and the World Economic Forum's Global Lighthouse Network.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Digital Officer
30%
VP of Operations
30%
Head of OT Cybersecurity
20%
Digital Transformation Program Director
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Integrated Oil & Gas Majors
30%
National Oil Companies
25%
Oilfield Service Providers
20%
Industrial Automation & Software Vendors
15%
EPC Contractors
10%
Secondary Research & Industry Benchmarking
20-30% of data derived from secondary research, benchmarking against official multilateral sources such as the OECD, International Energy Agency (IEA), U.S. Energy Information Administration (EIA), and International Renewable Energy Agency (IRENA).
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook used for company-level analysis and investment tracking.
Official .gov, .org, and recognized non-profit trade association sources cited; no commercial market research firms are referenced.
Demand Modeling & Market Estimation
Simultaneous top-down and bottom-up methodologies applied, validated via multi-level data triangulation.
Bottom-up market sizing based on number of active drilling rigs, refinery capacity, pipeline miles under digital monitoring, and average digital spend per asset.
Top-down modeling uses regional capex allocation for digital initiatives, cross-checked against vendor revenue disclosures.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85-90%, with all figures updated to the date of purchase.
Multi-level triangulation across primary interviews, secondary benchmarks, and financial databases ensures consistency.
Every report undergoes a three-stage quality review: data validation, analytical review, and editorial compliance.