Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Smart Restaurant System
Hospitality and Tourism / MARKET REPORT
Smart Restaurant System | Insight Market Data
Smart Restaurant System by Component (Software Platform, Hardware, Services), by Deployment (Cloud, On-Premise), by Functionality (POS, Inventory Management, Employee Management, CRM), by End-User (Full-Service Restaurants, Quick-Service Restaurants, Bars & Cafes, Multi-location Chains), by Terminal Type (Fixed POS, Mobile POS), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia-Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
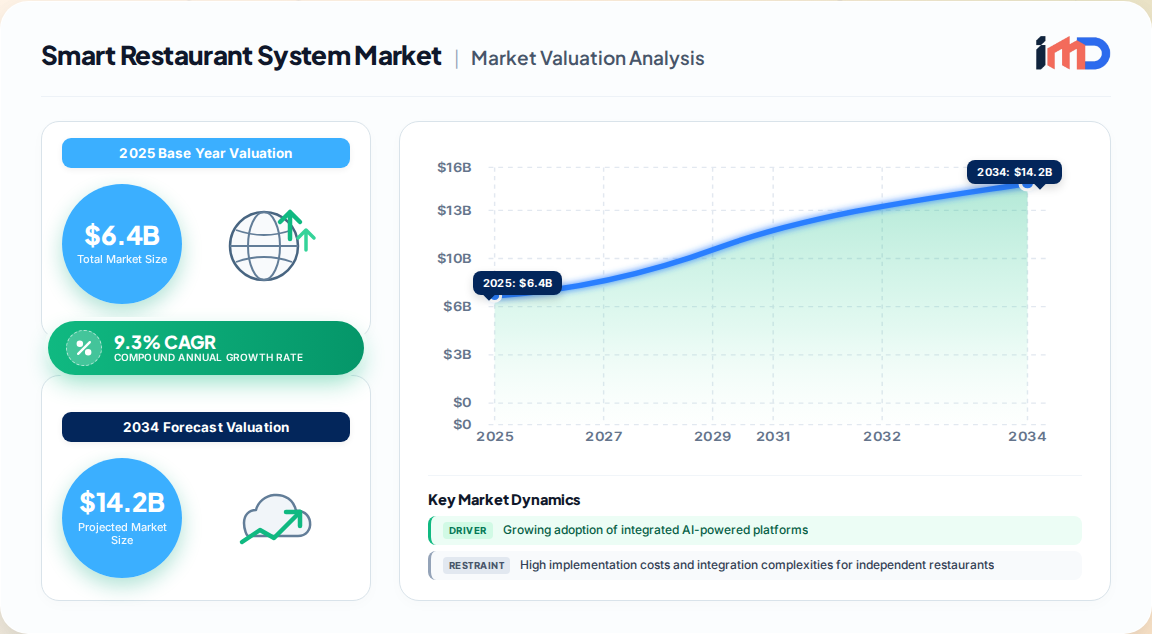
The global Smart Restaurant System market is undergoing a fundamental transformation as foodservice operators accelerate digitalization to meet rising labor costs, shifting consumer expectations, and the imperative for operational agility. Our proprietary primary research estimates the market at USD 6.4 billion in 2025, with a projected expansion to USD 10.9 billion by 2032, reflecting a robust CAGR of 9.3% during the forecast period 2026–2032. This growth is underpinned by the convergence of point-of-sale (POS) technology, cloud computing, artificial intelligence (AI), and the Internet of Things (IoT) into unified smart restaurant ecosystems.
Smart Restaurant System Market Size (In Billion)
15.0B
10.0B
5.0B
0
6.400 B
2025
6.995 B
2026
7.646 B
2027
8.357 B
2028
9.134 B
2029
9.983 B
2030
10.91 B
2031
Smart restaurant systems integrate front-of-house and back-of-house operations—including ordering, payment processing, inventory management, employee scheduling, customer relationship management (CRM), and analytics—into a single connected platform. The market is transitioning from standalone POS terminals to holistic, data-driven solutions that enable real-time decision-making, personalized guest experiences, and cost control. North America currently dominates with a 32.1% revenue share in 2025, but Asia-Pacific is poised to register the fastest growth, driven by rapid QSR expansion and digital payment adoption.
This report provides an in-depth analysis of market dynamics, segmentation, regional outlook, competitive strategies, and emerging opportunities, drawing on extensive primary interviews and rigorous quantitative modeling. All data and insights are derived from our proprietary research and expert interviews, ensuring actionable intelligence for stakeholders across the value chain.
Market Dynamics
Drivers
Growing Adoption of AI-Powered and Integrated Platforms: The shift toward unified smart systems that combine POS, online ordering, inventory, labor scheduling, and analytics is a primary growth driver. AI and predictive analytics enable demand forecasting, dynamic pricing, and personalized promotions, directly improving profitability. For instance, leading QSR chains are deploying voice-activated ordering and chatbots to enhance customer engagement and streamline operations.
Cloud-Based Deployment and Scalability: Cloud solutions accounted for 70.0% of the market in 2025, valued at USD 4.48 billion, and are projected to grow at a CAGR of 11.2%. Restaurants increasingly prefer cloud platforms for remote management, automatic updates, and lower upfront costs. This trend is especially pronounced among multi-location chains seeking centralized control.
Omnichannel Order Consolidation: The proliferation of online ordering, third-party delivery, and self-service kiosks demands systems that consolidate orders from multiple channels into a single kitchen workflow. Smart restaurant systems that seamlessly integrate with delivery aggregators and mobile apps are gaining traction, reducing errors and improving efficiency.
Contactless Payments and Digital Wallets: Accelerated by the pandemic, contactless payment adoption remains a key driver. In 2023, mobile payment users in the US exceeded 101 million, with Apple Pay used by 60% of respondents in restaurants. Smart POS systems with NFC and mobile wallet support are essential to meet consumer expectations for speed and safety.
Restraints
High Implementation Costs and Integration Complexities: For small and independent restaurants, the upfront investment in hardware, software, and training can be prohibitive. Integration with legacy systems and disparate third-party applications further adds to complexity and cost, limiting adoption among smaller operators.
Data Security and Privacy Concerns: With increasing reliance on cloud storage and digital payments, data breaches and compliance with regulations such as PCI DSS v4.0.1 and GDPR pose significant challenges. Restaurants must invest in robust cybersecurity measures, which can deter some from upgrading to advanced systems.
Resistance to Technological Change: Many restaurant owners and staff lack the technical expertise or willingness to transition from traditional methods, slowing down digital transformation, particularly in emerging markets.
Opportunities
Expansion of Cloud Kitchens and Off-Premise Dining: The rise of delivery-only concepts and ghost kitchens creates demand for systems optimized for high-volume takeout and delivery. Smart restaurant systems that integrate with delivery platforms and provide real-time order tracking present a significant growth avenue.
AI and Predictive Analytics for Operational Efficiency: Leveraging AI for inventory optimization, waste reduction, and labor forecasting can deliver measurable ROI, making advanced analytics a compelling value proposition for operators seeking to tighten margins.
Emerging Markets in Asia-Pacific and Latin America: Rapid urbanization, increasing disposable incomes, and the expansion of organized restaurant chains in countries like India, China, and Brazil offer untapped potential for smart restaurant system vendors.
Challenges
Fragmented Vendor Landscape and Interoperability: The market comprises numerous solution providers with varying degrees of integration, making it difficult for restaurants to choose and integrate systems. Standardization and open APIs are critical to addressing this challenge.
Regulatory Compliance Across Regions: Varying tax reporting requirements (e.g., EU's VAT in the Digital Age) and data localization laws require vendors to customize solutions, increasing operational complexity.
Value Chain Analysis
The smart restaurant system value chain comprises several interconnected stages, each contributing to the final solution delivered to foodservice operators.
Our primary research indicates that software platforms account for the largest share of the value chain, with 32.15% of the market by 2034, underscoring the importance of software-driven innovation. Hardware suppliers remain critical for enabling connectivity and data capture, while system integrators play a key role in ensuring seamless deployment.
Global Trade Analysis & Supply Chain Risk Assessment
The smart restaurant system market is less reliant on physical trade than traditional commodities, but hardware components (e.g., POS terminals, kiosks, sensors) are subject to global supply chain dynamics. According to UN Comtrade data, global exports of POS terminals and related hardware reached approximately USD 8.2 billion in 2024, with China, the United States, and Germany as leading exporters. Supply chain risks include semiconductor shortages, logistical disruptions, and geopolitical tensions, which can delay hardware deployments and increase costs.
To mitigate risks, vendors are diversifying sourcing and adopting cloud-based software to reduce hardware dependency. The shift toward software-as-a-service (SaaS) models also lessens the impact of hardware trade fluctuations. However, for markets in Asia-Pacific and Latin America, import reliance on hardware remains significant, and tariff policies can affect pricing and adoption rates.
Regional Outlook
North America leads the global smart restaurant system market, accounting for 32.1% of revenue in 2025, driven by high digital payment penetration, widespread adoption of cloud POS, and the presence of major vendors. The U.S. is the largest country market, with restaurant chains rapidly upgrading to integrated systems. Europe follows with a 26.0% share, supported by modernization of payment infrastructure and multi-location operations, though regulatory diversity (e.g., VAT e-invoicing) requires localized solutions.
Smart Restaurant System Regional Market Share
Loading chart...
Asia-Pacific is the fastest-growing region, projected to register a CAGR of 11.8% during 2026–2032, fueled by rapid QSR expansion, increasing smartphone penetration, and government push for digital payments. China, India, and Japan are key markets. Latin America and the Middle East & Africa are also expected to grow at moderate CAGRs of 9.7% and 9.3%, respectively, as digitalization spreads.
Region
2025 Share (%)
CAGR (2026–2032)
North America
32.1
8.3%
Europe
26.0
8.8%
Asia-Pacific
29.0
11.8%
Latin America
7.0
9.7%
Middle East & Africa
6.0
9.3%
Segmentation Analysis
The smart restaurant system market is segmented by component, deployment, functionality, end-user, and region. By component, software platforms are dominant, expected to hold 32.15% market share by 2034, while mobile POS software is the fastest-growing type with a CAGR of 10.34%. Cloud deployment leads with 70% share, and within functionality, POS holds the largest share at 43%, followed by inventory management (24%), CRM (17%), and employee management (16%). By end-user, full-service restaurants (FSR) lead with 37% share, while multi-location chains are the fastest-growing segment at 11.5% CAGR.
Segment
2025 Share (%)
CAGR (2026–2032)
Component: Software Platform
32.15 (by 2034)
11.2%
Deployment: Cloud
70.0
11.2%
Functionality: POS
43.0
8.7%
End-user: FSR
37.0
8.5%
End-user: Multi-location Chains
20.0
11.5%
Competitive Strategies
The competitive landscape is shifting from standalone POS systems to integrated platforms offering transactions, payments, customer engagement, inventory, workforce management, and analytics. Leading vendors are differentiating through cloud delivery, multi-location management, and AI-driven features.
Key players include Toast, Oracle, PAR Technology, Lightspeed, Square, Restaurant365, and Foodics. Toast provides a restaurant-focused cloud POS and payments platform; Oracle's Simphony is favored by large chains; PAR Technology targets QSR and enterprise brands; Lightspeed serves independents and multi-location hospitality businesses; Square offers simple implementation for smaller venues; Restaurant365 focuses on back-office accounting and inventory; and Foodics has a strong Middle East presence.
Strategic imperatives include:
Investment in AI and predictive analytics to deliver actionable insights.
Building open ecosystems with APIs to integrate third-party delivery and loyalty apps.
Expanding into emerging markets through localized solutions and partnerships.
Emphasizing data security and compliance to build trust.
Recent developments include Yum! Brands' launch of Byte by Yum! in February 2025, an AI-driven SaaS restaurant platform, and Square's June 2024 launch of an mPOS reader with built-in display. These innovations underscore the industry's move toward smarter, integrated systems.
Strategic White-Space Analysis
Our analysis identifies several underpenetrated opportunities:
Small and Independent Restaurants: Despite cost barriers, tailored, low-cost cloud solutions with modular pricing can unlock this vast segment, which remains largely underserved.
Integration with Third-Party Delivery: Seamless integration with platforms like Grubhub, Uber Eats, and DoorDash is still fragmented, presenting a white space for systems offering unified order management.
Advanced Analytics for Food Waste Reduction: With sustainability becoming a priority, systems that provide AI-driven waste tracking and forecasting can command premium pricing.
Emerging Markets in Southeast Asia and Africa: Rapidly growing foodservice sectors in countries like Indonesia, Vietnam, and Nigeria offer first-mover advantages for vendors with localized, mobile-first solutions.
Smart Restaurant System Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Smart Restaurant System REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.3% from 2020-2034
Segmentation
By Component
Software Platform
Hardware
Services
By Deployment
Cloud
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Growing adoption of integrated AI-powered platforms
3.1.2. Rising demand for contactless payments and digital wallets
3.1.3. Expansion of cloud kitchens and off-premise dining
3.2. Market Trends
3.2.1. AI-powered predictive analytics for demand forecasting and staffing
3.2.2. Omnichannel order consolidation across POS, mobile, and delivery platforms
3.2.3. Cloud-based deployment dominating with 70% share
3.3. Market Restrains
3.3.1. High implementation costs and integration complexities for independent restaurants
3.3.2. Data security and privacy concerns (PCI DSS, GDPR)
3.4. Market Restraints
3.4.1. High implementation costs and integration complexities for independent restaurants
3.4.2. Data security and privacy concerns (PCI DSS, GDPR)
3.5. Market Challenges
3.5.1. Fragmented vendor landscape and interoperability issues
On-Premise
By Functionality
POS
Inventory Management
Employee Management
CRM
By End-User
Full-Service Restaurants
Quick-Service Restaurants
Bars & Cafes
Multi-location Chains
By Terminal Type
Fixed POS
Mobile POS
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia-Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
3.5.2. Regulatory compliance across regions (e.g., VAT e-invoicing)
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Software Platform
5.1.2. Hardware
5.1.3. Services
5.2. Market Analysis, Insights and Forecast - by Deployment
5.2.1. Cloud
5.2.2. On-Premise
5.3. Market Analysis, Insights and Forecast - by Functionality
5.3.1. POS
5.3.2. Inventory Management
5.3.3. Employee Management
5.3.4. CRM
5.4. Market Analysis, Insights and Forecast - by End-User
5.4.1. Full-Service Restaurants
5.4.2. Quick-Service Restaurants
5.4.3. Bars & Cafes
5.4.4. Multi-location Chains
5.5. Market Analysis, Insights and Forecast - by Terminal Type
5.5.1. Fixed POS
5.5.2. Mobile POS
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia-Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Software Platform
6.1.2. Hardware
6.1.3. Services
6.2. Market Analysis, Insights and Forecast - by Deployment
6.2.1. Cloud
6.2.2. On-Premise
6.3. Market Analysis, Insights and Forecast - by Functionality
6.3.1. POS
6.3.2. Inventory Management
6.3.3. Employee Management
6.3.4. CRM
6.4. Market Analysis, Insights and Forecast - by End-User
6.4.1. Full-Service Restaurants
6.4.2. Quick-Service Restaurants
6.4.3. Bars & Cafes
6.4.4. Multi-location Chains
6.5. Market Analysis, Insights and Forecast - by Terminal Type
6.5.1. Fixed POS
6.5.2. Mobile POS
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Software Platform
7.1.2. Hardware
7.1.3. Services
7.2. Market Analysis, Insights and Forecast - by Deployment
7.2.1. Cloud
7.2.2. On-Premise
7.3. Market Analysis, Insights and Forecast - by Functionality
7.3.1. POS
7.3.2. Inventory Management
7.3.3. Employee Management
7.3.4. CRM
7.4. Market Analysis, Insights and Forecast - by End-User
7.4.1. Full-Service Restaurants
7.4.2. Quick-Service Restaurants
7.4.3. Bars & Cafes
7.4.4. Multi-location Chains
7.5. Market Analysis, Insights and Forecast - by Terminal Type
7.5.1. Fixed POS
7.5.2. Mobile POS
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Software Platform
8.1.2. Hardware
8.1.3. Services
8.2. Market Analysis, Insights and Forecast - by Deployment
8.2.1. Cloud
8.2.2. On-Premise
8.3. Market Analysis, Insights and Forecast - by Functionality
8.3.1. POS
8.3.2. Inventory Management
8.3.3. Employee Management
8.3.4. CRM
8.4. Market Analysis, Insights and Forecast - by End-User
8.4.1. Full-Service Restaurants
8.4.2. Quick-Service Restaurants
8.4.3. Bars & Cafes
8.4.4. Multi-location Chains
8.5. Market Analysis, Insights and Forecast - by Terminal Type
8.5.1. Fixed POS
8.5.2. Mobile POS
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Software Platform
9.1.2. Hardware
9.1.3. Services
9.2. Market Analysis, Insights and Forecast - by Deployment
9.2.1. Cloud
9.2.2. On-Premise
9.3. Market Analysis, Insights and Forecast - by Functionality
9.3.1. POS
9.3.2. Inventory Management
9.3.3. Employee Management
9.3.4. CRM
9.4. Market Analysis, Insights and Forecast - by End-User
9.4.1. Full-Service Restaurants
9.4.2. Quick-Service Restaurants
9.4.3. Bars & Cafes
9.4.4. Multi-location Chains
9.5. Market Analysis, Insights and Forecast - by Terminal Type
9.5.1. Fixed POS
9.5.2. Mobile POS
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Software Platform
10.1.2. Hardware
10.1.3. Services
10.2. Market Analysis, Insights and Forecast - by Deployment
10.2.1. Cloud
10.2.2. On-Premise
10.3. Market Analysis, Insights and Forecast - by Functionality
10.3.1. POS
10.3.2. Inventory Management
10.3.3. Employee Management
10.3.4. CRM
10.4. Market Analysis, Insights and Forecast - by End-User
10.4.1. Full-Service Restaurants
10.4.2. Quick-Service Restaurants
10.4.3. Bars & Cafes
10.4.4. Multi-location Chains
10.5. Market Analysis, Insights and Forecast - by Terminal Type
10.5.1. Fixed POS
10.5.2. Mobile POS
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Toast
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Oracle
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. PAR Technology
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Lightspeed
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Square
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Restaurant365
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Foodics
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. NCR Voyix
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. 7shifts
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Craftable
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. ChowNow
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. MarketMan
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Nory
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Toshiba Tec
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Smart Restaurant System Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Smart Restaurant System Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Smart Restaurant System Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Smart Restaurant System Revenue (Billion), by Deployment 2026 & 2034
Figure 5: North America Smart Restaurant System Revenue Share (%), by Deployment 2026 & 2034
Figure 6: North America Smart Restaurant System Revenue (Billion), by Functionality 2026 & 2034
Figure 7: North America Smart Restaurant System Revenue Share (%), by Functionality 2026 & 2034
Figure 8: North America Smart Restaurant System Revenue (Billion), by End-User 2026 & 2034
Figure 9: North America Smart Restaurant System Revenue Share (%), by End-User 2026 & 2034
Figure 10: North America Smart Restaurant System Revenue (Billion), by Terminal Type 2026 & 2034
Figure 11: North America Smart Restaurant System Revenue Share (%), by Terminal Type 2026 & 2034
Figure 12: North America Smart Restaurant System Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Smart Restaurant System Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Smart Restaurant System Revenue (Billion), by Component 2026 & 2034
Figure 15: Europe Smart Restaurant System Revenue Share (%), by Component 2026 & 2034
Figure 16: Europe Smart Restaurant System Revenue (Billion), by Deployment 2026 & 2034
Figure 17: Europe Smart Restaurant System Revenue Share (%), by Deployment 2026 & 2034
Figure 18: Europe Smart Restaurant System Revenue (Billion), by Functionality 2026 & 2034
Figure 19: Europe Smart Restaurant System Revenue Share (%), by Functionality 2026 & 2034
Figure 20: Europe Smart Restaurant System Revenue (Billion), by End-User 2026 & 2034
Figure 21: Europe Smart Restaurant System Revenue Share (%), by End-User 2026 & 2034
Figure 22: Europe Smart Restaurant System Revenue (Billion), by Terminal Type 2026 & 2034
Figure 23: Europe Smart Restaurant System Revenue Share (%), by Terminal Type 2026 & 2034
Figure 24: Europe Smart Restaurant System Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Smart Restaurant System Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia-Pacific Smart Restaurant System Revenue (Billion), by Component 2026 & 2034
Figure 27: Asia-Pacific Smart Restaurant System Revenue Share (%), by Component 2026 & 2034
Figure 28: Asia-Pacific Smart Restaurant System Revenue (Billion), by Deployment 2026 & 2034
Figure 29: Asia-Pacific Smart Restaurant System Revenue Share (%), by Deployment 2026 & 2034
Figure 30: Asia-Pacific Smart Restaurant System Revenue (Billion), by Functionality 2026 & 2034
Figure 31: Asia-Pacific Smart Restaurant System Revenue Share (%), by Functionality 2026 & 2034
Figure 32: Asia-Pacific Smart Restaurant System Revenue (Billion), by End-User 2026 & 2034
Figure 33: Asia-Pacific Smart Restaurant System Revenue Share (%), by End-User 2026 & 2034
Figure 34: Asia-Pacific Smart Restaurant System Revenue (Billion), by Terminal Type 2026 & 2034
Figure 35: Asia-Pacific Smart Restaurant System Revenue Share (%), by Terminal Type 2026 & 2034
Figure 36: Asia-Pacific Smart Restaurant System Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia-Pacific Smart Restaurant System Revenue Share (%), by Country 2026 & 2034
Figure 38: Latin America Smart Restaurant System Revenue (Billion), by Component 2026 & 2034
Figure 39: Latin America Smart Restaurant System Revenue Share (%), by Component 2026 & 2034
Figure 40: Latin America Smart Restaurant System Revenue (Billion), by Deployment 2026 & 2034
Figure 41: Latin America Smart Restaurant System Revenue Share (%), by Deployment 2026 & 2034
Figure 42: Latin America Smart Restaurant System Revenue (Billion), by Functionality 2026 & 2034
Figure 43: Latin America Smart Restaurant System Revenue Share (%), by Functionality 2026 & 2034
Figure 44: Latin America Smart Restaurant System Revenue (Billion), by End-User 2026 & 2034
Figure 45: Latin America Smart Restaurant System Revenue Share (%), by End-User 2026 & 2034
Figure 46: Latin America Smart Restaurant System Revenue (Billion), by Terminal Type 2026 & 2034
Figure 47: Latin America Smart Restaurant System Revenue Share (%), by Terminal Type 2026 & 2034
Figure 48: Latin America Smart Restaurant System Revenue (Billion), by Country 2026 & 2034
Figure 49: Latin America Smart Restaurant System Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Smart Restaurant System Revenue (Billion), by Component 2026 & 2034
Figure 51: Middle East & Africa Smart Restaurant System Revenue Share (%), by Component 2026 & 2034
Figure 52: Middle East & Africa Smart Restaurant System Revenue (Billion), by Deployment 2026 & 2034
Figure 53: Middle East & Africa Smart Restaurant System Revenue Share (%), by Deployment 2026 & 2034
Figure 54: Middle East & Africa Smart Restaurant System Revenue (Billion), by Functionality 2026 & 2034
Figure 55: Middle East & Africa Smart Restaurant System Revenue Share (%), by Functionality 2026 & 2034
Figure 56: Middle East & Africa Smart Restaurant System Revenue (Billion), by End-User 2026 & 2034
Figure 57: Middle East & Africa Smart Restaurant System Revenue Share (%), by End-User 2026 & 2034
Figure 58: Middle East & Africa Smart Restaurant System Revenue (Billion), by Terminal Type 2026 & 2034
Figure 59: Middle East & Africa Smart Restaurant System Revenue Share (%), by Terminal Type 2026 & 2034
Figure 60: Middle East & Africa Smart Restaurant System Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Smart Restaurant System Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Smart Restaurant System Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Global Smart Restaurant System Revenue Billion Forecast, by Deployment 2020 & 2034
Table 3: Global Smart Restaurant System Revenue Billion Forecast, by Functionality 2020 & 2034
Table 4: Global Smart Restaurant System Revenue Billion Forecast, by End-User 2020 & 2034
Table 5: Global Smart Restaurant System Revenue Billion Forecast, by Terminal Type 2020 & 2034
Table 6: Global Smart Restaurant System Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Smart Restaurant System Revenue Billion Forecast, by Component 2020 & 2034
Table 8: North America Smart Restaurant System Revenue Billion Forecast, by Deployment 2020 & 2034
Table 9: North America Smart Restaurant System Revenue Billion Forecast, by Functionality 2020 & 2034
Table 10: North America Smart Restaurant System Revenue Billion Forecast, by End-User 2020 & 2034
Table 11: North America Smart Restaurant System Revenue Billion Forecast, by Terminal Type 2020 & 2034
Table 12: North America Smart Restaurant System Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Smart Restaurant System Revenue Billion Forecast, by Component 2020 & 2034
Table 17: Europe Smart Restaurant System Revenue Billion Forecast, by Deployment 2020 & 2034
Table 18: Europe Smart Restaurant System Revenue Billion Forecast, by Functionality 2020 & 2034
Table 19: Europe Smart Restaurant System Revenue Billion Forecast, by End-User 2020 & 2034
Table 20: Europe Smart Restaurant System Revenue Billion Forecast, by Terminal Type 2020 & 2034
Table 21: Europe Smart Restaurant System Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Germany Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Italy Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Spain Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Asia-Pacific Smart Restaurant System Revenue Billion Forecast, by Component 2020 & 2034
Table 28: Asia-Pacific Smart Restaurant System Revenue Billion Forecast, by Deployment 2020 & 2034
Table 29: Asia-Pacific Smart Restaurant System Revenue Billion Forecast, by Functionality 2020 & 2034
Table 30: Asia-Pacific Smart Restaurant System Revenue Billion Forecast, by End-User 2020 & 2034
Table 31: Asia-Pacific Smart Restaurant System Revenue Billion Forecast, by Terminal Type 2020 & 2034
Table 32: Asia-Pacific Smart Restaurant System Revenue Billion Forecast, by Country 2020 & 2034
Table 33: China Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Japan Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: India Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: South Korea Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Australia Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Latin America Smart Restaurant System Revenue Billion Forecast, by Component 2020 & 2034
Table 39: Latin America Smart Restaurant System Revenue Billion Forecast, by Deployment 2020 & 2034
Table 40: Latin America Smart Restaurant System Revenue Billion Forecast, by Functionality 2020 & 2034
Table 41: Latin America Smart Restaurant System Revenue Billion Forecast, by End-User 2020 & 2034
Table 42: Latin America Smart Restaurant System Revenue Billion Forecast, by Terminal Type 2020 & 2034
Table 43: Latin America Smart Restaurant System Revenue Billion Forecast, by Country 2020 & 2034
Table 44: Brazil Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Argentina Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 46: Middle East & Africa Smart Restaurant System Revenue Billion Forecast, by Component 2020 & 2034
Table 47: Middle East & Africa Smart Restaurant System Revenue Billion Forecast, by Deployment 2020 & 2034
Table 48: Middle East & Africa Smart Restaurant System Revenue Billion Forecast, by Functionality 2020 & 2034
Table 49: Middle East & Africa Smart Restaurant System Revenue Billion Forecast, by End-User 2020 & 2034
Table 50: Middle East & Africa Smart Restaurant System Revenue Billion Forecast, by Terminal Type 2020 & 2034
Table 51: Middle East & Africa Smart Restaurant System Revenue Billion Forecast, by Country 2020 & 2034
Table 52: Saudi Arabia Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: UAE Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 54: South Africa Smart Restaurant System Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the market size of the Smart Restaurant System market in 2025?
The global smart restaurant system market was valued at USD 6.4 billion in 2025, according to our proprietary primary research. It is projected to reach USD 10.9 billion by 2032, growing at a CAGR of 9.3%.
2Which region dominates the Smart Restaurant System market?
North America holds the largest market share at 32.1% in 2025, driven by high adoption of cloud POS and digital payment technologies. However, Asia-Pacific is the fastest-growing region with a CAGR of 11.8%.
3What are the key drivers of the Smart Restaurant System market?
Key drivers include the growing adoption of AI-powered integrated platforms, the shift to cloud-based deployment (70% share), omnichannel order consolidation, and the rising demand for contactless payments.
4How is AI reshaping the Smart Restaurant System market?
AI enables predictive demand forecasting, dynamic staffing, inventory optimization, and personalized marketing. Platforms like Byte by Yum! launched in 2025 exemplify the trend toward AI-driven restaurant management.
5Who are the leading companies in the Smart Restaurant System market?
Leading vendors include Toast, Oracle, PAR Technology, Lightspeed, Square, Restaurant365, and Foodics. These companies are differentiating through cloud delivery, AI integration, and multi-location management capabilities.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our proprietary research relies on a 70–80% primary research component, involving direct interviews and surveys with key decision-makers across the smart restaurant system value chain.
We conducted in-depth interviews with C-level executives, operations directors, IT managers, and procurement heads from restaurant chains, independent restaurants, and technology vendors.
Primary research participants include 4–5 specific company types: restaurant POS software developers, hardware OEMs (terminals, kiosks, card readers), cloud infrastructure providers, system integrators, and restaurant franchise operators.
Stakeholder job titles interviewed include Chief Technology Officer (CTO), Director of Operations, Procurement Manager, and Restaurant Owner/Manager.
We also engage with industry associations and regulatory bodies such as the National Restaurant Association (NRA), the PCI Security Standards Council, and the European Payment Council to validate compliance and operational standards.
Quantitative metrics captured include average transaction value per terminal, software subscription penetration rates, number of installed POS terminals, and average spend per restaurant on IT.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Technology Officer (CTO)
30%
Director of Operations
25%
Procurement Manager
25%
Restaurant Owner/Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Restaurant POS Software Developers
35%
Hardware OEMs (Terminals, Kiosks)
25%
Cloud Infrastructure Providers
15%
System Integrators
15%
Restaurant Franchise Operators
10%
Secondary Research & Industry Benchmarking
Secondary research constitutes 20–30% of our methodology and includes a rigorous review of official filings, trade statistics, and regulatory documents.
Data sources include Bloomberg, Factiva, Hoovers, and PitchBook for financial and company-level data.
We benchmark against official multilateral sources such as UN Comtrade for hardware trade flows, Eurostat for European restaurant industry statistics, and OECD for macroeconomic indicators.
We also reference standards from the PCI Security Standards Council (PCI DSS v4.0.1) and GDPR for data privacy, ensuring regulatory alignment.
Demand Modeling & Market Estimation
We employ a bottom-up approach to calculate market size, building from granular restaurant-level data: number of restaurant outlets by type (FSR, QSR, bars & cafés), average technology spend per outlet, and adoption rates of smart systems.
This is cross-validated with a top-down approach using total IT spending in the foodservice sector and vendor revenue reports.
Multi-level data triangulation is applied to reconcile differences and ensure consistency across segments and regions.
Key quantitative metrics used in modeling include average revenue per user (ARPU) for software subscriptions, hardware attach rates, and cloud migration rates.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous validation and cross-referencing.
Every data point is subjected to multi-level triangulation, comparing primary interview findings with secondary sources and historical trends.
Our reports are updated to the date of purchase, ensuring the latest market developments and data are incorporated.
A dedicated quality assurance team reviews all data and analysis for consistency, logical coherence, and adherence to research standards.