1What is the size of the France hospitality market?
The France hospitality market was valued at USD 128.18 billion in 2025 and is estimated at USD 133.68 billion in 2026, forecast to reach USD 164.78 billion by 2031 at a 4.29% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 France Hospitality Market
 by Type (Chain Hotels, Independent Hotels), by Accommodation Class (Luxury & Palace, Mid & Upper-Mid-Scale, Budget & Economy, Service Apartments), by Booking Channel (Direct Digital, OTAs, Corporate/MICE, Wholesale & Traditional Agents), by Service Type (Food Service, Accommodation), by Ownership (Chained, Standalone), by Tourist Origin (Domestic, International), by France (Île-de-France, Provence-Alpes-Côte d'Azur, Auvergne-Rhône-Alpes, Occitanie, Nouvelle-Aquitaine, Other Regions) Forecast 2026-2034
Research Associate


 Related Reports

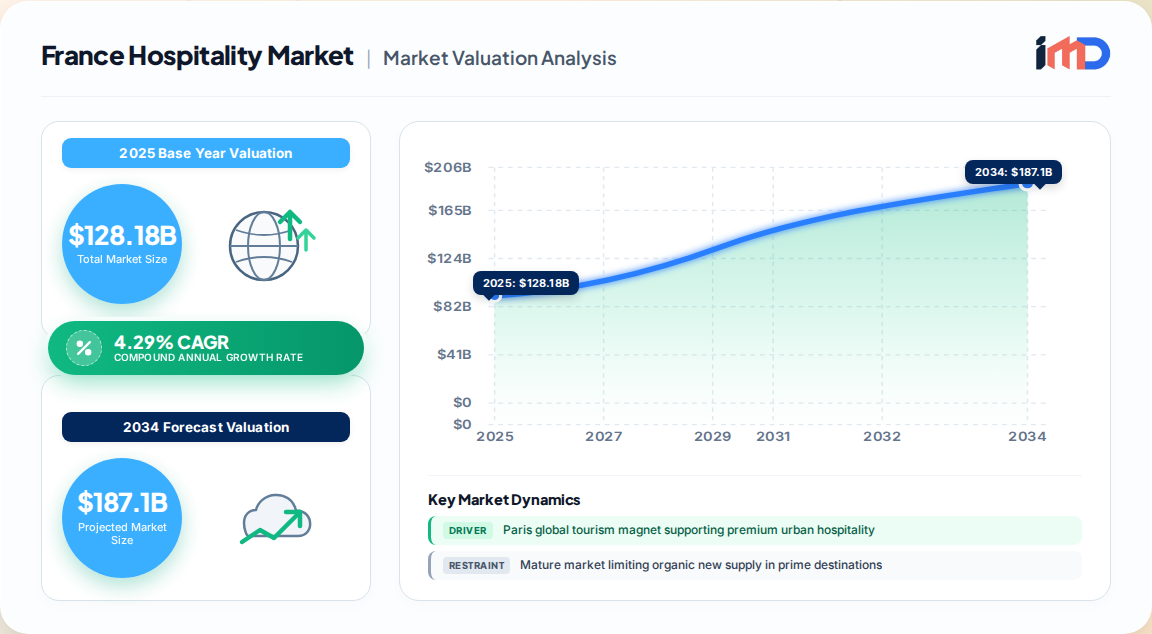
The France hospitality market represents one of the most mature, resilient, and globally influential lodging and food-service ecosystems in the world. Our proprietary first-party research estimates the market at USD 128.18 billion in 2025, expanding to USD 133.68 billion in 2026 and forecast to reach USD 164.78 billion by 2031, reflecting a 4.29% CAGR over the 2026–2031 period.
France welcomed 102 million international visitors in 2025, while total visitor nights reached 743 million across commercial and non-commercial accommodation. Tourism directly contributed 3.8% of national GDP and supported 1.5 million direct jobs (7.6% of total employment), with travel exports representing 19.1% of total service exports.
Demand-side and policy-side forces reinforce revenue visibility across the forecast window.
| Driver | Est. CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Paris global tourism magnet | 1.20% | Paris luxury and business districts | ≤ 2 years |
| Fashion and luxury ecosystem | 0.90% | Paris haute couture hubs | ≤ 2 years |
| International event calendar | 0.80% | Paris and Cannes | ≤ 2 years |
| Wine region tourism | 0.70% | Bordeaux, Burgundy, Champagne | 2–4 years |
| Heritage property conversion | 0.60% | Loire, Provence, Normandy | ≥ 4 years |
| Second-home and regional leisure culture | 0.50% | Provence, Brittany, Alps | 2–4 years |
Independent hotels led with 61.74% share in 2025, reflecting the fragmented, family-owned character of French provincial supply. Chain hotels are forecast to record the fastest growth at a 5.12% CAGR, driven by asset-light franchise conversion.
| Segment | 2025 Share | Growth Outlook |
|---|---|---|
| Mid & Upper-Mid-Scale | 42.95% | Steady core |
| Luxury & Palace | Dominant value contributor | Premiumization-led |
| Budget & Economy | Volume-led | Moderate |
| Service Apartments | Emerging | 6.00% CAGR |
OTAs commanded 41.05% of market value in 2025, while direct digital bookings are poised for a 7.00% CAGR through 2031 as brands invest in loyalty ecosystems and first-party data.
Île-de-France held 33.05% share in 2025, recording 89.7 million collective accommodation nights. Provence-Alpes-Côte d'Azur is forecast for a 5.52% CAGR, supported by coastal and wine-tourism demand.
Competitive intensity is moderate, with the top five operators holding approximately 47% of national room capacity.
| Player | Strategic Positioning |
|---|---|
| Accor S.A. | Multi-brand breadth across luxury to economy |
| Louvre Hotels Group | Economy and midscale chain scale |
| B&B HOTELS | Budget segment expansion |
| Marriott International | Global loyalty-led premium penetration |
| Hilton | Corporate and MICE demand capture |
| Logis Hotels Group | Independent hotel affiliation network |
| Groupe Lucien Barrière | Resort and casino-integrated hospitality |
| Maisons Pariente, Evok Collection | Boutique luxury and lifestyle |
Winning strategies center on direct-booking conversion, loyalty monetization, premiumization of room product, and asset-light conversion of ageing independent stock. Approximately 16,850 players operate in the market, sustaining competitive dynamism at the regional level.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.29% from 2020-2034 |
| Segmentation |
|
By Booking Channel
By Service Type
By Ownership
By Tourist Origin
| By Geography |
|
The France hospitality market was valued at USD 128.18 billion in 2025 and is estimated at USD 133.68 billion in 2026, forecast to reach USD 164.78 billion by 2031 at a 4.29% CAGR.
Île-de-France held 33.05% of national market share in 2025, recording 89.7 million collective accommodation nights, while Provence-Alpes-Côte d'Azur is forecast to grow fastest at a 5.52% CAGR.
OTAs commanded 41.05% of market value in 2025, but direct digital bookings are forecast to grow at a 7.00% CAGR through 2031 as brands invest in loyalty and first-party data.
Major operators include Accor S.A., Louvre Hotels Group, B&B HOTELS, Marriott International, Hilton, Logis Hotels Group, Groupe Lucien Barrière, and boutique players such as Evok Collection and Maisons Pariente.
Key drivers include 102 million international arrivals in 2025, the EUR 1.9 billion Destination France programme, high-speed rail connectivity, wine-region tourism, and heritage property conversion into boutique hotels.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Revenue Officer | 32% |
| Asset Management Director | 28% |
| Head of Distribution & Channel Strategy | 24% |
| Tourism Board Policy Lead | 16% |
| Company Type | Representation (%) |
|---|---|
| Hotel Owners & Asset Managers | 30% |
| Hotel Operators & Revenue Directors | 28% |
| OTA & Distribution Executives | 18% |
| Hospitality Technology Vendors | 14% |
| Serviced Apartment Operators | 10% |