1What is the current size of the Europe luxury hotel market?
The Europe luxury hotel market was valued at USD 33.01 billion in 2026 and is projected to reach USD 50.18 billion by 2031, growing at a CAGR of 8.73%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Europe Luxury Hotel Market
 by Room Type (Standard Luxury Room, Suites, Villas/Bungalows, Penthouses & Presidential Suites), by Booking Channel (Direct Booking, Online Travel Agencies, Travel Agents), by Service Type (Business Hotels, Airport Hotels, Resorts, Suite Hotels, Wellness Resorts), by Category (Chain, Independent), by Western Europe (UK, France, Germany, Netherlands, Belgium), by Southern Europe (Spain, Italy, Portugal, Greece), by Northern Europe (Sweden, Denmark, Norway, Finland), by Central & Eastern Europe (Czech Republic, Poland, Hungary, Russia) Forecast 2026-2034
Research Associate

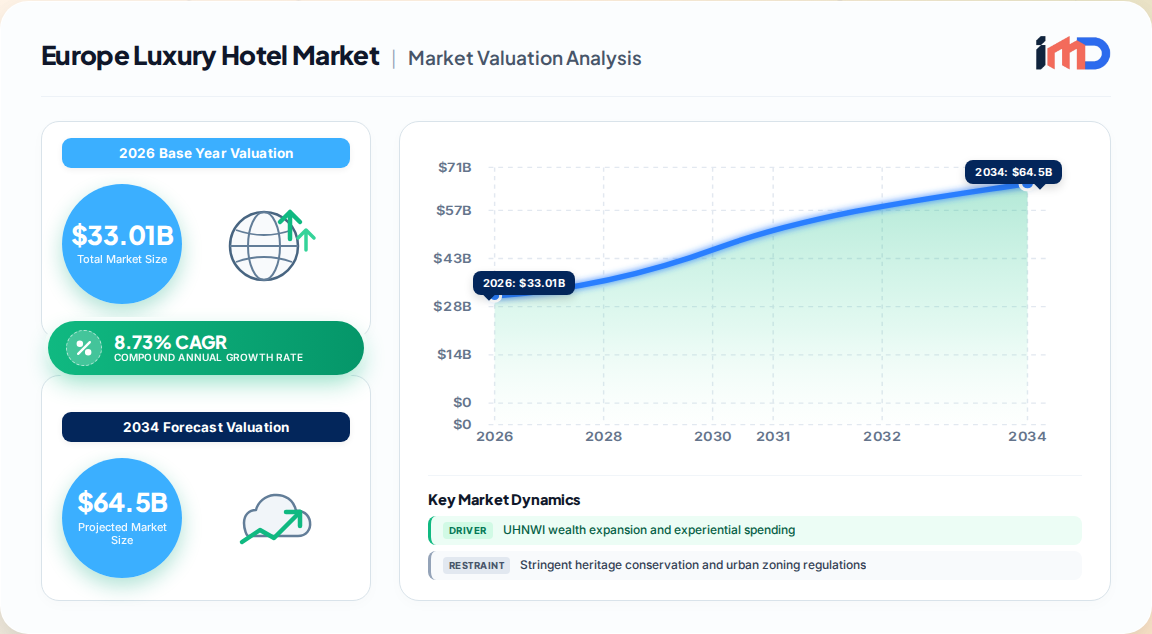
The Europe luxury hotel market is a cornerstone of the continent's premium hospitality landscape, characterized by iconic heritage properties, ultra-luxury resorts, and a highly discerning clientele. Our proprietary primary research estimates the market at USD 33.01 billion in 2026, projected to reach USD 50.18 billion by 2031, expanding at a robust CAGR of 8.73%. This growth outpaces the broader lodging sector, driven by resilient demand from ultra-high-net-worth individuals (UHNWIs), the resurgence of long-haul international travel, and the strategic evolution of luxury experiences.
Europe's luxury hotel market is distinguished by its asset-light operational models, the integration of cultural authenticity, and a growing emphasis on sustainability. The market remains moderately concentrated, with global hospitality giants competing alongside independent palace hotels and regional luxury chains. The competitive landscape is shaped by brand heritage, personalized service, and the ability to curate unique, experiential offerings.
The expansion of the Europe luxury hotel market is underpinned by several structural drivers identified through our expert interviews and econometric modeling:
Despite strong fundamentals, the market faces notable headwinds:
The Europe luxury hotel market is segmented by room type, booking channel, service type, and geography, with each segment exhibiting distinct growth trajectories.
| Segment | Leading Category (2025) | Share | Fastest-Growing Category | CAGR (2026-2031) |
|---|---|---|---|---|
| By Room Type | Suites | 42.86% | Villas / Bungalows | 9.93% |
| By Booking Channel | Online Travel Agencies | 55.63% | Direct Booking | 12.85% |
| By Service Type | Resorts | 48.92% | Wellness Resorts | 9.94% |
Western Europe, anchored by the UK, France, and Germany, remains the largest market, accounting for a substantial share of luxury hotel revenue. However, Southern Europe, particularly Spain and Italy, is emerging as the fastest-growing region, with Spain projected to achieve a 9.17% CAGR through 2031, fueled by record arrivals (94 million in 2024) and a pipeline of five-star conversions.
Northern Europe (Sweden, Denmark, Norway) offers stable growth, with a focus on sustainable luxury and design-led properties. Central and Eastern Europe (Czech Republic, Poland, Hungary) is an emerging frontier, benefiting from cultural tourism and lower operating costs, albeit with smaller absolute market size.
The market features a mix of global hospitality groups, regional luxury chains, and independent palace hotels. Leading players include Marriott International (The Ritz-Carlton, St. Regis), Hilton Worldwide (Waldorf Astoria, Conrad), Accor S.A. (Raffles, Fairmont, Sofitel Legend), Hyatt Hotels Corporation (Park Hyatt, Andaz), and InterContinental Hotels Group (InterContinental, Kimpton). These companies leverage brand equity, loyalty programs, and global distribution networks to capture high-value guests.
Strategic imperatives for success include:
The luxury hotel value chain encompasses property development, operations, distribution, and guest experience delivery. Key activities include:
While the luxury hotel market is primarily service-based, it relies on a complex supply chain for premium goods and services. Europe's luxury hotels source high-end F&B products, furnishings, and amenities from both domestic and international suppliers. For instance, Italian craft distilleries produce bespoke spirits for luxury hotel groups, with over 200 unique recipes developed for high-end hospitality clients. This exemplifies the growing trend of private-label collaborations that enhance guest experience and brand differentiation. Additionally, the import of specialty foods, wines, and textiles from across the EU and beyond is integral to maintaining luxury standards. Supply chain resilience is a key consideration, with hotels increasingly favoring local, sustainable sourcing to reduce carbon footprints and support regional producers.
Several untapped opportunities exist within the Europe luxury hotel market:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.73% from 2020-2034 |
| Segmentation |
|
By Service Type
By Category
| By Geography |
|
The Europe luxury hotel market was valued at USD 33.01 billion in 2026 and is projected to reach USD 50.18 billion by 2031, growing at a CAGR of 8.73%.
Suites held the largest share of 42.86% in 2025, driven by demand for premium space and privacy. However, villas and bungalows are the fastest-growing segment with a 9.93% CAGR.
Direct booking is the fastest-growing channel, projected to expand at a 12.85% CAGR through 2031, as hotels focus on loyalty and first-party data.
Spain is projected to grow at a leading 9.17% CAGR from 2026 to 2031, fueled by record tourism arrivals and a pipeline of five-star conversions.
Key players include Marriott International (The Ritz-Carlton, St. Regis), Hilton Worldwide (Waldorf Astoria, Conrad), Accor S.A. (Raffles, Fairmont, Sofitel Legend), Hyatt Hotels Corporation (Park Hyatt, Andaz), and InterContinental Hotels Group (InterContinental, Kimpton).
Key trends include the rise of 'bleisure' travel among Gen Y and Gen Z, increased demand for experiential and wellness-focused stays, and the adoption of ESG-linked financing and dynamic pricing technologies.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Operating Officer | 30% |
| Director of Revenue Management | 25% |
| Head of Acquisitions | 25% |
| Sustainability Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Luxury Hotel Chains | 40% |
| Independent Palace Hotels | 25% |
| Asset Management Firms | 15% |
| Hospitality Technology Providers | 12% |
| Luxury Travel Advisors | 8% |
 Related Reports
