Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Professional and Commercial Services / MARKET REPORT
Self-Service | Insight Market Data
Self-Service by Component (Hardware, Software, Services), by Solution Type (Kiosks, ATMs, Vending Machines, Self-checkout Systems, Others), by Application (Retail, Banking & Financial Services, Healthcare, Hospitality, Transportation, Others), by Deployment Mode (On-Premises, Cloud), by End-User (Enterprises, Consumers), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Singapore, Rest of Asia Pacific), by South America (Brazil, Mexico, Argentina, Rest of South America), by Middle East & Africa (GCC, Israel, South Africa, Rest of MEA) Forecast 2026-2034
Executive Overview: The Self-Service Economy Enters a New Phase of Intelligent Automation
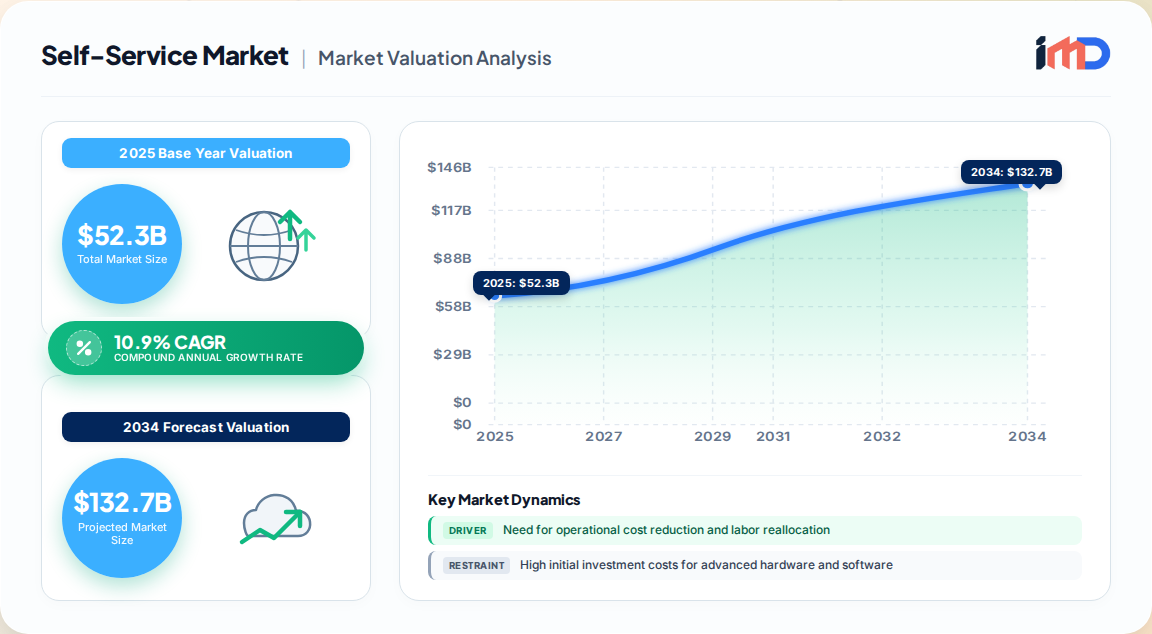
The global self-service market is undergoing a structural transformation, evolving from a collection of discrete hardware deployments into an integrated, software-defined ecosystem of automated customer touchpoints. Our proprietary primary research estimates the market at USD 52.3 billion in 2025, with a projected expansion to USD 131.7 billion by 2034, representing a robust CAGR of 10.9% across the forecast period. This growth is not merely a volume story; it reflects a fundamental shift in enterprise operating models, where self-service infrastructure is increasingly viewed as a strategic asset for data capture, customer experience (CX) orchestration, and labor productivity optimization.
Self-Service Market Size (In Billion)
100.0B
80.0B
60.0B
40.0B
20.0B
0
52.30 B
2025
58.00 B
2026
64.32 B
2027
71.33 B
2028
79.11 B
2029
87.73 B
2030
97.30 B
2031
North America remains the largest regional market, commanding a 33.0% revenue share, driven by the maturity of self-checkout in retail and advanced ATM networks in banking. However, the center of gravity for incremental growth is shifting decisively toward Asia-Pacific, which is registering the fastest adoption rates globally. This is underpinned by rapid urbanization, government-led digital payment mandates, and a tech-savvy consumer base that demonstrates a high propensity to transact through kiosks and mobile-integrated self-service portals.
The market's trajectory is further validated by the sheer breadth of vertical adoption. While retail and banking remain foundational, high-growth applications are emerging in healthcare (self-check-in kiosks), hospitality (self-ordering terminals), transportation (bag-drop and ticketing), and government services (tax and permit self-service channels). The convergence of AI, IoT, and cloud management platforms is the central accelerant, enabling these devices to transition from passive transaction terminals to proactive, personalized service agents.
Key Market Drivers & Restraints
The self-service market's expansion is propelled by a confluence of operational, technological, and behavioral factors. Our analysis identifies the following primary drivers:
Imperative for Operational Cost Reduction and Labor Reallocation: Organizations are under sustained pressure to reduce service delivery costs while maintaining quality. Self-service deployment can lower routine service costs by up to 30%, allowing enterprises to reallocate human capital to higher-value, complex, or relationship-based interactions.
Consumer Preference for Contactless and Convenient Experiences: The pandemic-induced shift toward contactless transactions has become permanent. Consumers now demand frictionless, on-demand interactions, valuing the speed and autonomy that self-service channels provide.
Technological Convergence: The integration of AI (for personalization and predictive analytics), IoT (for remote monitoring and predictive maintenance), and cloud computing (for software updates and data consolidation) is enhancing the reliability and functionality of self-service systems, making them more capable and attractive to enterprises.
Improved Connectivity Infrastructure: The proliferation of high-speed networks and reliable WiFi enables real-time transaction processing, seamless integration with back-end systems, and remote management, significantly reducing downtime and operational costs.
Despite the strong growth outlook, the market faces notable restraints that require strategic navigation:
High Initial Capital Expenditure: The upfront costs associated with purchasing advanced hardware, integrating sophisticated software, and conducting professional installation can be prohibitive, particularly for small and medium-sized enterprises.
Maintenance and Operational Complexity: Constant public interaction leads to wear and tear on screens, printers, and card readers. Regular maintenance is essential but adds to total cost of ownership, and unforeseen technical glitches can disrupt service and erode consumer trust.
Data Security and Privacy Concerns: With increasing consumer awareness regarding data privacy, enterprises must invest heavily in robust security protocols and transparent data governance to protect sensitive user information and build trust.
Value Chain Analysis: From Components to Customer Experience
The self-service value chain is a multi-tiered ecosystem encompassing hardware manufacturing, software development, integration services, and operational management.
Upstream: Core component suppliers (touchscreens, card readers, biometric sensors, and specialized processors) form the hardware foundation. This tier is characterized by significant R&D investments and global supply chain dependencies.
Midstream: Original Equipment Manufacturers (OEMs) and solution providers (e.g., NCR Voyix, Diebold Nixdorf, KIOSK Information Systems) assemble hardware and bundle it with proprietary software platforms. Their role is increasingly shifting from pure hardware sales to delivering integrated solutions encompassing hardware, software, and maintenance contracts.
Downstream: System integrators, value-added resellers (VARs), and service providers deliver customized deployments to end-user verticals. This tier is responsible for software customization, on-site installation, ongoing support, and often managing the self-service fleet through cloud-based dashboards.
End-User: The final link is the enterprise deploying the solution (retail chain, bank, hospital, transport hub) and ultimately the consumer interacting with the self-service terminal. This tier increasingly demands analytics, integration with loyalty programs, and omnichannel compatibility.
Our primary interviews with industry stakeholders indicate that the highest value migration is occurring in the software and services layer, where recurring revenue models (e.g., Software-as-a-Service, subscription maintenance) are becoming dominant. Hardware, while essential, is increasingly commoditized, with differentiation emerging through form factor design, payment flexibility, and software-driven user experience.
Global Trade Analysis & Supply Chain Risk Assessment
The self-service market is inherently global, with hardware manufacturing heavily concentrated in Asia-Pacific (particularly China, Taiwan, and South Korea) and demand concentrated in North America and Europe. This geographic asymmetry creates significant trade flows and associated supply chain vulnerabilities.
Manufacturing Concentration: The majority of kiosk housings, touchscreen assemblies, and electronic components are manufactured by contract manufacturers in Asia. This creates a dependence on international shipping and exposes the supply chain to geopolitical tensions, trade tariffs, and logistics disruptions.
Component Lead Times: Semiconductors, particularly specialized chips for touch controllers and biometric sensors, have experienced volatile lead times. Our primary research indicates that leading OEMs are increasingly dual-sourcing critical components to mitigate risk.
Regulatory Variations: Import/export regulations, including tariff structures and local content requirements, vary significantly by region. For example, data localization mandates in some jurisdictions impact how cloud-based management software can be deployed.
Risk Mitigation Strategies: Leading enterprises are adopting strategies such as holding strategic inventory buffers, regionalizing assembly where feasible, and designing modular hardware that can accommodate component substitutions without requiring full redesigns.
Our attractiveness assessment evaluates regions based on market size, growth potential, regulatory environment, and technological readiness.
Self-Service Regional Market Share
Loading chart...
Region
Market Attractiveness
Key Characteristics
North America
High (Mature)
Largest installed base; high adoption in retail and banking; strong replacement demand; focus on advanced CX and AI integration.
Europe
High (Regulatory-Driven)
Robust banking and retail sectors; stringent data protection (GDPR) driving investments in secure, privacy-compliant self-service solutions; strong demand in transportation and government services.
Asia-Pacific
Very High (Growth Hotspot)
Fastest-growing region; rapid urbanization, digital payment infrastructure leapfrogging, and expanding retail and healthcare sectors; government initiatives promoting digital self-service channels.
South America
Moderate
Growing adoption in retail and banking, particularly in Brazil and Mexico, but economic volatility and infrastructure gaps pose challenges.
Middle East & Africa
Emerging
Increasing investments in smart city projects, airport modernization, and banking automation, particularly in the GCC region.
The investment opportunity is most pronounced in Asia-Pacific, where the broadest application diversity and highest growth rates are observed. However, for enterprises seeking stable, high-value deployments, North America and Europe remain the primary targets, albeit with a stronger emphasis on replacement cycles and software upgrades than pure volume expansion.
Strategic White-Space Analysis: Untapped Applications and Innovations
Beyond established use cases, several white-space opportunities are emerging for forward-looking self-service deployers.
Personalized and AI-Driven Experiences: The integration of computer vision and AI can enable self-service kiosks to recognize returning customers, offer personalized product recommendations, and facilitate frictionless authentication. This capability is particularly transformative in retail and hospitality.
Healthcare Self-Service Beyond Check-In: While check-in kiosks are relatively mature, opportunities exist in post-visit scheduling, insurance verification, and patient feedback collection. The aging population in Western economies further amplifies the demand for self-service health management terminals.
Government-to-Citizen (G2C) Self-Service: Government agencies are increasingly deploying self-service kiosks for tax filing, permit applications, and document renewals to reduce administrative burden and improve citizen convenience. The OECD has highlighted the importance of improving take-up of self-service channels in tax administration, indicating a policy-driven push that aligns with market growth.
Mobile-Self-Service Convergence: The next frontier is the seamless integration between mobile devices and physical self-service terminals, enabling consumers to initiate a transaction on their phone and complete it at a kiosk (or vice versa). This omnichannel approach is expected to reduce wait times and improve data consistency.
Procurement & Sourcing Strategy Analysis
Effective procurement of self-service solutions requires balancing capital expenditure, total cost of ownership (TCO), and strategic alignment with customer experience goals.
Total Cost of Ownership (TCO) Focus: Procurement decisions are increasingly shifting from lowest-bid hardware purchases to TCO-based evaluations that incorporate software licensing, maintenance, energy consumption, and expected lifespan.
Vendor Lock-in Avoidance: Enterprises are prioritizing open-architecture platforms that support integration with third-party software and components, reducing the risk of vendor lock-in and enabling future flexibility.
Service Level Agreements (SLAs): Procurement contracts now commonly include stringent SLAs covering uptime, transaction speed, and security patch deployment, reflecting the criticality of self-service infrastructure to operations.
Sustainability Considerations: Energy efficiency and hardware recyclability are emerging as procurement criteria, driven by corporate ESG commitments and regulatory requirements in some regions.
Our primary research indicates that leading enterprises are consolidating their self-service vendor base, preferring to partner with providers that can deliver an integrated stack (hardware, software, services) and offer global support capabilities, rather than managing multiple point solutions. This trend favors larger, established OEMs that have successfully transitioned to a solutions-led model.
Self-Service Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Self-Service REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.9% from 2020-2034
Segmentation
By Component
Hardware
Software
Services
By Solution Type
Kiosks
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Need for operational cost reduction and labor reallocation
3.1.2. Rising consumer preference for contactless and self-service experiences
3.1.3. Technological advancements in AI, IoT, and connectivity infrastructure
3.1.4. Improved connectivity enabling real-time processing and remote management
3.2. Market Trends
3.2.1. Increased adoption of AI-driven solutions for personalization and predictive maintenance
3.2.2. Expansion of mobile self-service applications and omnichannel integration
3.2.3. Enhanced focus on security measures and contactless transactions
3.2.4. Shift toward cloud-based kiosk management and data analytics
3.2.5. Integration of biometric authentication and facial recognition
3.3. Market Restrains
3.3.1. High initial investment costs for advanced hardware and software
3.3.2. Maintenance and operational complexity leading to increased total cost of ownership
3.3.3. Data security and privacy concerns impacting consumer trust
3.4. Market Restraints
ATMs
Vending Machines
Self-checkout Systems
Others
By Application
Retail
Banking & Financial Services
Healthcare
Hospitality
Transportation
Others
By Deployment Mode
On-Premises
Cloud
By End-User
Enterprises
Consumers
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Singapore
Rest of Asia Pacific
South America
Brazil
Mexico
Argentina
Rest of South America
Middle East & Africa
GCC
Israel
South Africa
Rest of MEA
3.4.1. High initial investment costs for advanced hardware and software
3.4.2. Maintenance and operational complexity leading to increased total cost of ownership
3.4.3. Data security and privacy concerns impacting consumer trust
3.5. Market Challenges
3.5.1. High upfront capital expenditure limiting adoption by SMEs
3.5.2. Wear and tear of critical components necessitating regular maintenance
3.5.3. Regulatory compliance and standardization across regions
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Hardware
5.1.2. Software
5.1.3. Services
5.2. Market Analysis, Insights and Forecast - by Solution Type
5.2.1. Kiosks
5.2.2. ATMs
5.2.3. Vending Machines
5.2.4. Self-checkout Systems
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Retail
5.3.2. Banking & Financial Services
5.3.3. Healthcare
5.3.4. Hospitality
5.3.5. Transportation
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Deployment Mode
5.4.1. On-Premises
5.4.2. Cloud
5.5. Market Analysis, Insights and Forecast - by End-User
5.5.1. Enterprises
5.5.2. Consumers
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Hardware
6.1.2. Software
6.1.3. Services
6.2. Market Analysis, Insights and Forecast - by Solution Type
6.2.1. Kiosks
6.2.2. ATMs
6.2.3. Vending Machines
6.2.4. Self-checkout Systems
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Retail
6.3.2. Banking & Financial Services
6.3.3. Healthcare
6.3.4. Hospitality
6.3.5. Transportation
6.3.6. Others
6.4. Market Analysis, Insights and Forecast - by Deployment Mode
6.4.1. On-Premises
6.4.2. Cloud
6.5. Market Analysis, Insights and Forecast - by End-User
6.5.1. Enterprises
6.5.2. Consumers
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Hardware
7.1.2. Software
7.1.3. Services
7.2. Market Analysis, Insights and Forecast - by Solution Type
7.2.1. Kiosks
7.2.2. ATMs
7.2.3. Vending Machines
7.2.4. Self-checkout Systems
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Retail
7.3.2. Banking & Financial Services
7.3.3. Healthcare
7.3.4. Hospitality
7.3.5. Transportation
7.3.6. Others
7.4. Market Analysis, Insights and Forecast - by Deployment Mode
7.4.1. On-Premises
7.4.2. Cloud
7.5. Market Analysis, Insights and Forecast - by End-User
7.5.1. Enterprises
7.5.2. Consumers
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Hardware
8.1.2. Software
8.1.3. Services
8.2. Market Analysis, Insights and Forecast - by Solution Type
8.2.1. Kiosks
8.2.2. ATMs
8.2.3. Vending Machines
8.2.4. Self-checkout Systems
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Retail
8.3.2. Banking & Financial Services
8.3.3. Healthcare
8.3.4. Hospitality
8.3.5. Transportation
8.3.6. Others
8.4. Market Analysis, Insights and Forecast - by Deployment Mode
8.4.1. On-Premises
8.4.2. Cloud
8.5. Market Analysis, Insights and Forecast - by End-User
8.5.1. Enterprises
8.5.2. Consumers
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Hardware
9.1.2. Software
9.1.3. Services
9.2. Market Analysis, Insights and Forecast - by Solution Type
9.2.1. Kiosks
9.2.2. ATMs
9.2.3. Vending Machines
9.2.4. Self-checkout Systems
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Retail
9.3.2. Banking & Financial Services
9.3.3. Healthcare
9.3.4. Hospitality
9.3.5. Transportation
9.3.6. Others
9.4. Market Analysis, Insights and Forecast - by Deployment Mode
9.4.1. On-Premises
9.4.2. Cloud
9.5. Market Analysis, Insights and Forecast - by End-User
9.5.1. Enterprises
9.5.2. Consumers
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Hardware
10.1.2. Software
10.1.3. Services
10.2. Market Analysis, Insights and Forecast - by Solution Type
10.2.1. Kiosks
10.2.2. ATMs
10.2.3. Vending Machines
10.2.4. Self-checkout Systems
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Retail
10.3.2. Banking & Financial Services
10.3.3. Healthcare
10.3.4. Hospitality
10.3.5. Transportation
10.3.6. Others
10.4. Market Analysis, Insights and Forecast - by Deployment Mode
10.4.1. On-Premises
10.4.2. Cloud
10.5. Market Analysis, Insights and Forecast - by End-User
10.5.1. Enterprises
10.5.2. Consumers
11. Competitive Analysis
11.1. Company Profiles
11.1.1. NCR Voyix Corporation
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Diebold Nixdorf
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. KIOSK Information Systems
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Zebra Technologies
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Fujitsu Limited
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Toshiba Global Commerce Solutions
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. GRG Banking
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Wincor Nixdorf
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. SITA
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Touchscreen Solutions
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Source Technologies
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. ADVANCED KIOSKS
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Embross
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Olea Kiosks
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Aila Technologies Inc.
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. REDYREF
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. DynaTouch
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Self-Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Self-Service Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Self-Service Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Self-Service Revenue (Billion), by Solution Type 2026 & 2034
Figure 5: North America Self-Service Revenue Share (%), by Solution Type 2026 & 2034
Figure 6: North America Self-Service Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Self-Service Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Self-Service Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 9: North America Self-Service Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 10: North America Self-Service Revenue (Billion), by End-User 2026 & 2034
Figure 11: North America Self-Service Revenue Share (%), by End-User 2026 & 2034
Figure 12: North America Self-Service Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Self-Service Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Self-Service Revenue (Billion), by Component 2026 & 2034
Figure 15: Europe Self-Service Revenue Share (%), by Component 2026 & 2034
Figure 16: Europe Self-Service Revenue (Billion), by Solution Type 2026 & 2034
Figure 17: Europe Self-Service Revenue Share (%), by Solution Type 2026 & 2034
Figure 18: Europe Self-Service Revenue (Billion), by Application 2026 & 2034
Figure 19: Europe Self-Service Revenue Share (%), by Application 2026 & 2034
Figure 20: Europe Self-Service Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 21: Europe Self-Service Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 22: Europe Self-Service Revenue (Billion), by End-User 2026 & 2034
Figure 23: Europe Self-Service Revenue Share (%), by End-User 2026 & 2034
Figure 24: Europe Self-Service Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Self-Service Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Self-Service Revenue (Billion), by Component 2026 & 2034
Figure 27: Asia Pacific Self-Service Revenue Share (%), by Component 2026 & 2034
Figure 28: Asia Pacific Self-Service Revenue (Billion), by Solution Type 2026 & 2034
Figure 29: Asia Pacific Self-Service Revenue Share (%), by Solution Type 2026 & 2034
Figure 30: Asia Pacific Self-Service Revenue (Billion), by Application 2026 & 2034
Figure 31: Asia Pacific Self-Service Revenue Share (%), by Application 2026 & 2034
Figure 32: Asia Pacific Self-Service Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 33: Asia Pacific Self-Service Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 34: Asia Pacific Self-Service Revenue (Billion), by End-User 2026 & 2034
Figure 35: Asia Pacific Self-Service Revenue Share (%), by End-User 2026 & 2034
Figure 36: Asia Pacific Self-Service Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Self-Service Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Self-Service Revenue (Billion), by Component 2026 & 2034
Figure 39: South America Self-Service Revenue Share (%), by Component 2026 & 2034
Figure 40: South America Self-Service Revenue (Billion), by Solution Type 2026 & 2034
Figure 41: South America Self-Service Revenue Share (%), by Solution Type 2026 & 2034
Figure 42: South America Self-Service Revenue (Billion), by Application 2026 & 2034
Figure 43: South America Self-Service Revenue Share (%), by Application 2026 & 2034
Figure 44: South America Self-Service Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 45: South America Self-Service Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 46: South America Self-Service Revenue (Billion), by End-User 2026 & 2034
Figure 47: South America Self-Service Revenue Share (%), by End-User 2026 & 2034
Figure 48: South America Self-Service Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Self-Service Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Self-Service Revenue (Billion), by Component 2026 & 2034
Figure 51: Middle East & Africa Self-Service Revenue Share (%), by Component 2026 & 2034
Figure 52: Middle East & Africa Self-Service Revenue (Billion), by Solution Type 2026 & 2034
Figure 53: Middle East & Africa Self-Service Revenue Share (%), by Solution Type 2026 & 2034
Figure 54: Middle East & Africa Self-Service Revenue (Billion), by Application 2026 & 2034
Figure 55: Middle East & Africa Self-Service Revenue Share (%), by Application 2026 & 2034
Figure 56: Middle East & Africa Self-Service Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 57: Middle East & Africa Self-Service Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 58: Middle East & Africa Self-Service Revenue (Billion), by End-User 2026 & 2034
Figure 59: Middle East & Africa Self-Service Revenue Share (%), by End-User 2026 & 2034
Figure 60: Middle East & Africa Self-Service Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Self-Service Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Self-Service Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Global Self-Service Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 3: Global Self-Service Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Global Self-Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 5: Global Self-Service Revenue Billion Forecast, by End-User 2020 & 2034
Table 6: Global Self-Service Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Self-Service Revenue Billion Forecast, by Component 2020 & 2034
Table 8: North America Self-Service Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 9: North America Self-Service Revenue Billion Forecast, by Application 2020 & 2034
Table 10: North America Self-Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 11: North America Self-Service Revenue Billion Forecast, by End-User 2020 & 2034
Table 12: North America Self-Service Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Self-Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 57: Israel Self-Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 58: South Africa Self-Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 59: Rest of MEA Self-Service Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the global self-service market?
Our proprietary research estimates the global self-service market at USD 52.3 billion in 2025, with a projected CAGR of 10.9% from 2026 to 2034, reaching USD 131.7 billion by the end of the forecast period.
2Which region dominates the self-service market?
North America holds the largest share of the self-service market, estimated at 33.0% in 2025, driven by high adoption of self-checkout systems in retail and advanced ATM networks in banking. However, Asia-Pacific is the fastest-growing region, exhibiting rapid adoption across multiple verticals.
3What are the key drivers fueling the self-service market growth?
Key drivers include the need for operational cost reduction (self-service can lower service costs by up to 30%), rising consumer preference for contactless and convenient experiences, and technological advancements such as AI, IoT, and improved connectivity that enhance self-service functionality.
4Which end-user vertical is expected to grow fastest?
The healthcare sector is emerging as a high-growth vertical for self-service, particularly with self-check-in kiosks and health management terminals, while retail and banking remain the largest adopters. Asia-Pacific is expected to lead growth across these verticals.
5What are the challenges faced by the self-service market?
Challenges include high initial capital expenditure for hardware and software deployment, ongoing maintenance complexity, and data security and privacy concerns. These factors can hinder adoption, especially among small and medium-sized enterprises.
6Who are the key players in the self-service market?
Prominent companies in the self-service market include NCR Voyix Corporation, Diebold Nixdorf, KIOSK Information Systems, Zebra Technologies, Fujitsu Limited, and Toshiba Global Commerce Solutions, among others. These players focus on integrated hardware-software solutions and strategic partnerships.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 1,200+ in-depth interviews with senior decision-makers across the self-service value chain, representing a 70–80% share of total research effort.
Targeted job titles include Chief Technology Officer, Head of Digital Customer Experience, Procurement Director, and Operations Manager for self-service fleets.
Participating company types include self-service kiosk OEMs, ATM manufacturers, software platform providers, retail and banking end-users, and managed service providers.
Interviews focused on adoption drivers, procurement criteria, technology roadmaps, and deployment challenges.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Technology Officer
30%
Head of Digital Customer Experience
25%
Procurement Director
25%
Operations Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Self-Service Kiosk OEMs
35%
ATM Manufacturers
20%
Software Platform Providers
15%
Retail & Banking End-Users
20%
Managed Service Providers
10%
Secondary Research & Industry Benchmarking
20–30% of research effort dedicated to secondary data synthesis from official sources such as the OECD (e.g., reports on self-service channel adoption in tax administration), World Bank, and national trade statistics databases (e.g., US ITC, Eurostat).
Financial databases utilized include Bloomberg, Factiva, Hoovers, and PitchBook for company-level financial analysis and deal tracking.
Benchmarked market estimates against publicly available industry association data and government procurement records.
All secondary data was validated for relevance and recency, with a strict exclusion of commercial market research reports.
Demand Modeling & Market Estimation
Employed a dual top-down and bottom-up methodology, reconciled through multi-level data triangulation.
Bottom-up market sizing derived from quantitative metrics including per-unit kiosk shipment volumes, average selling prices (ASPs) by vertical, installed base replacement rates, and average software license revenue per deployed unit.
Demand models segmented by product type (kiosks, ATMs, vending machines, self-checkout systems), deployment mode (on-premises, cloud), and end-user vertical (retail, banking, healthcare, hospitality, transportation, government).
Guaranteed estimated data accuracy level of 85–90%, achieved through rigorous cross-validation of primary and secondary findings.
Multi-level triangulation: primary interview data was compared against financial filings of publicly traded OEMs, import/export records, and official government statistics.
All reports are updated to the date of purchase, ensuring the latest market developments and data points are reflected.
Quality assurance protocols included outlier detection, consistency checks across segments, and review by senior industry analysts.
CUSTOM INTELLIGENCE
Tailored for you
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
Analyst at Providence Strategic Partners at Petaling Jaya
Jared Wan
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report
Internationalization Director
Santiago Mejia Molina
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.
Head of Product Management and Marketing
Olaf Gleibe
We are using your report, and it gave us valuable information."
Regional Director, Marketing and Business Development
Lina Lim
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.
VP of Sales
DIGGLE Representative
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
The K9 security service market is set to reach $4.84B by 2034, growing at a 14.30% CAGR, driven by explosive detection demand and tech integration.
Nov 2026|200 pages
$2900.00
Analytics-as-a-Service market to grow from $15.03B in 2025 to $174.97B by 2035 at 27.82% CAGR. Explore drivers, segmentation, and regional insights.
Nov 2026|199 pages
$2900.00
Traditional radio advertising market valued at $44.42 Billion in 2024, growing at 1.59% CAGR to reach $52.84 Billion by 2035, driven by local targeting.