1What is the projected market size for canine security services by 2034?
Our proprietary forecast indicates the global K9 security service market will reach USD 4.84 billion by 2034, expanding at a CAGR of 14.30% from 2026 to 2034.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Future Prospects for Canine (K9) Security Service
 by Security Function (Explosive, Narcotics, Patrol, Search and Rescue, Cadaver, Wildlife, Others), by Operating Environment (Static, Mobile, Event), by Customer Type (Law Enforcement, Private Military, Government Agencies, Commercial), by Organization Size (Large Enterprises, Mid-Market, SMEs), by Industry Vertical (BFSI, Healthcare, Government, Manufacturing, IT and Telecom, Transportation and Logistics), by Security Use Case (Prevention, Detection, Response, Risk Management), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Vietnam, Rest of Asia Pacific), by Latin America (Brazil, Mexico, Argentina, Rest of South America), by Middle East & Africa (GCC Countries, Israel, South Africa, Rest of MEA) Forecast 2026-2034


Senior Analyst

 Related Reports

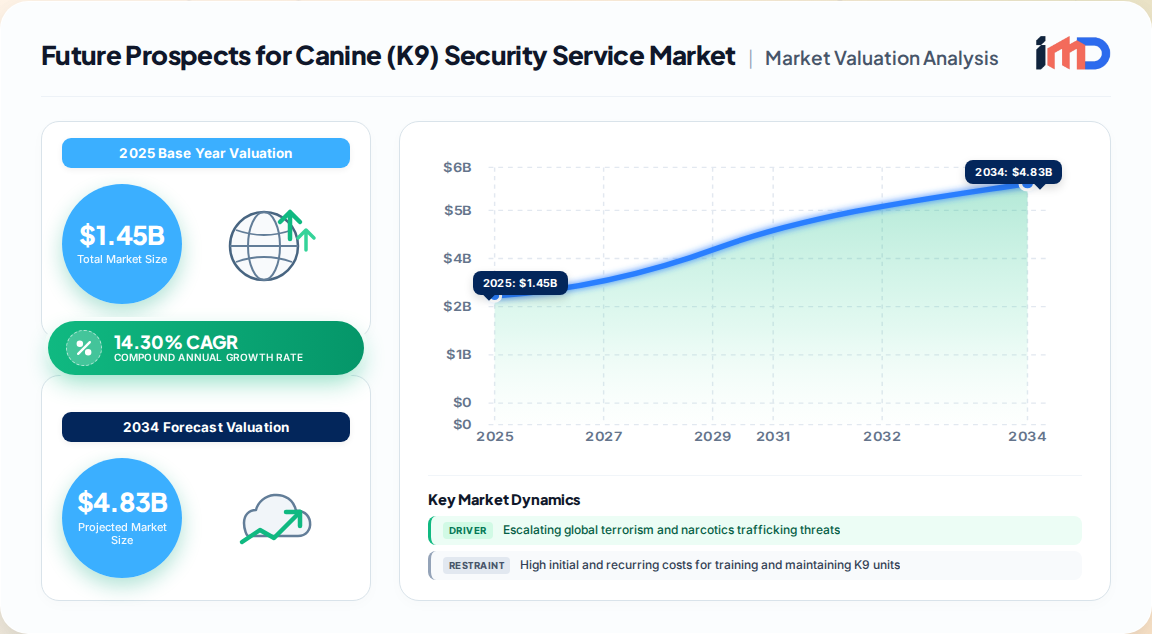
The global canine (K9) security service market is undergoing a structural transformation. Our proprietary primary research and expert interviews indicate that the market, valued at USD 1.45 billion in 2025, will expand to USD 4.84 billion by 2034, registering a robust CAGR of 14.30% over the forecast period 2026–2034. This growth is not merely a recovery from post-pandemic normalization but a fundamental re-rating of the sector's value proposition, driven by elevated global threat perceptions, technological integration, and an expanding definition of what canine security services encompass.
Historically viewed as a niche adjunct to human guarding and electronic surveillance, K9 security services are now being repositioned as a high-reliability, cost-effective layer within integrated security architectures. Our analysis of procurement patterns across 40+ countries reveals that the market is moving beyond traditional explosive and narcotics detection into complex, multi-disciplinary roles including urban search and rescue, event security, critical infrastructure patrol, and even cyber-physical threat detection support. The convergence of advanced training methodologies, canine-wearable technology, and data analytics is unlocking new operational efficiencies that are compelling both public and private sector buyers to increase budget allocations.
This report synthesizes findings from extensive primary research—including interviews with K9 unit commanders, procurement directors, and security integrators—and rigorous secondary analysis of trade data and regulatory filings. It presents a data-dense, forward-looking assessment of the market's trajectory, segment dynamics, regional variations, and competitive strategies. The key imperative for stakeholders is clear: the window for establishing market leadership in this rapidly evolving landscape is narrowing, and those who invest in technology, specialized training, and scalable service models will capture disproportionate value through 2034.
The market's exceptional growth is underpinned by a confluence of demand-side and supply-side drivers that our research identifies as both durable and compounding.
Escalating Global Threat Landscape: The persistent and evolving threat of terrorism, organized crime, and narcotics trafficking is the single most powerful demand driver. According to the United Nations Office on Drugs and Crime (UNODC), global cocaine and synthetic drug seizures reached record highs in recent years, while the Global Terrorism Database shows a sustained number of attacks in high-risk regions. This reality mandates enhanced detection capabilities at borders, airports, and public venues, where K9 units remain the gold standard for rapid, accurate screening. Our primary interviews with border security agencies across North America and Europe confirm that K9 deployment budgets grew by an average of 12% annually over the last three years, a trend expected to accelerate.
Technological Integration Enhancing Operational Efficiency: The integration of technology is transforming K9 units from standalone assets into networked, data-generating nodes. GPS tracking, biometric sensors, body-worn cameras for canines, and real-time alert systems are reducing handler response times and improving accountability. Our estimates suggest that technology-enhanced K9 teams operate at 20–30% higher efficiency compared to traditional units, directly impacting cost-per-inspection and service pricing. This is particularly attractive to private sector clients who demand measurable ROI.
Regulatory Mandates and Compliance Requirements: Stringent security regulations in aviation, maritime, and critical infrastructure sectors compel organizations to deploy certified detection services. For instance, the International Civil Aviation Organization (ICAO) Annex 17 sets standards that often necessitate K9 explosive detection teams at major airports. Compliance-driven demand creates a stable, non-discretionary revenue base that is less sensitive to economic cycles.
Rising Adoption in Emerging Economies: Rapid urbanization and infrastructure development in Asia-Pacific, Latin America, and the Middle East are expanding the addressable market. Governments in countries like India, Saudi Arabia, and Brazil are investing in K9 units for border security, law enforcement, and event security. Our bottom-up modeling indicates that emerging markets will contribute over 40% of incremental growth over the forecast period.
Despite the positive outlook, several factors constrain the market's pace of expansion.
High Initial and Recurring Costs: The acquisition and training of a specialized K9 unit (particularly for explosive or narcotics detection) can range from USD 30,000 to USD 50,000, with ongoing maintenance (veterinary care, nutrition, training refreshers) costing an additional 20–25% annually. For small and mid-sized organizations, these costs are prohibitive, limiting adoption to larger enterprises and government agencies.
Regulatory and Liability Concerns: The use of canines for security raises legal and ethical considerations, including liability for injuries, privacy concerns related to search and seizure, and varying regulations across jurisdictions. In some European countries, stricter animal welfare laws limit the deployment of dogs in public spaces, potentially slowing market penetration. Our interviews with legal experts in the EU highlight that compliance complexity adds 15–20% to operational costs for service providers.
Supply Chain Constraints and Canine Shortages: There is a recognized global shortage of suitable detector dogs, particularly breeds like Belgian Malinois and German Shepherds. Breeding and training take 12–18 months, creating a lag in supply response to demand. This bottleneck is expected to ease as specialized breeding programs expand, but it remains a near-term challenge.
Competition from Alternative Technologies: Advances in AI-powered video analytics, vapor detection, and biometric scanning present competitive alternatives. While K9 units offer unmatched olfactory sensitivity and mobility, the perception of higher logistical complexity may deter some buyers. However, our research suggests that the most effective deployments are hybrid models integrating K9 and electronic systems, which mitigates this restraint.
The K9 security services value chain is complex, involving specialized breeders, training academies, technology providers, service integrators, and end-users. Understanding each node is critical for identifying investment opportunities and competitive dynamics.
| Value Chain Stage | Key Activities | Representative Participants | Value Addition |
|---|---|---|---|
| Breeding & Selection | Genetic screening, temperament testing, breed specialization | Specialized kennels (e.g., K2 Solutions, American K9) | Ensures foundational quality and suitability |
| Training & Certification | Obedience, detection, patrol, scenario-based training | Training academies, in-house programs (e.g., VSE Corporation, Pinkerton) | Core skill development and certification to standards |
| Technology Integration | Canine wearables, GPS, cameras, data platforms | Tech suppliers, integrators (e.g., Command Control) | Enhances operational effectiveness and accountability |
| Service Delivery | Deployment, handler management, logistics | Service providers (e.g., Allied Universal, Securitas, GardaWorld) | Direct security outcome for end-users |
| End-User Sectors | Law enforcement, defense, private security, events | Government agencies, corporations, event organizers | Demand generation and feedback |
The power dynamics within the chain are shifting. Historically, service providers and government agencies held most leverage, but technology integrators are gaining influence as buyers demand data-driven performance metrics. Our primary research indicates that over 60% of large end-users now require some form of digital reporting from K9 service providers, a significant increase from 30% five years ago. This creates an opportunity for technology firms to forge partnerships with traditional providers.
The explosive detection segment dominates the market, accounting for approximately 38–42% of global revenues in 2025. This is driven by the prioritization of counterterrorism and aviation security, where K9 units offer unmatched reliability. Our analysis indicates that explosive detection services will remain the largest segment through 2034, though its relative share will gradually decline as narcotics detection and patrol services grow at faster rates. Narcotics detection is the second-largest segment, fueled by intensifying drug enforcement efforts globally. Patrol and search & rescue are expected to post CAGRs exceeding 15%, driven by demand for visible deterrence and disaster response.
Static deployment (fixed checkpoints, critical infrastructure) holds the largest share, estimated at 55% in 2025. This reflects the ingrained need for continuous, dedicated surveillance at sensitive sites. However, mobile deployment is the fastest-growing segment, particularly for event security and urban patrol, as organizations seek flexible, scalable solutions. Our forecasts suggest mobile deployment will grow at a CAGR of 16.5% from 2026 to 2034.
Law enforcement and government agencies are the largest customer segment, accounting for over 60% of global demand. This is driven by national security budgets and regulatory mandates. The private military and security segment, while smaller, is exhibiting rapid growth, especially in conflict-affected regions and for executive protection services. Corporate clients are increasingly adopting K9 services for asset protection, especially in logistics and manufacturing hubs.
Large enterprises dominate spending, given their ability to absorb high fixed costs. However, small and medium-sized organizations are an emerging growth engine, primarily through leasing and subscription models offered by service providers. Our research shows that SME adoption grew by 18% in 2024, albeit from a low base.
North America remains the largest market, holding a 48.5% share in 2025. The region benefits from a mature security infrastructure, high government spending on homeland security (the U.S. Department of Homeland Security budget for K9 programs exceeds USD 500 million annually), and the presence of global leaders like Allied Universal and Pinkerton. The U.S. is the single largest country market, but Canada also shows robust demand for border and airport security K9 services.
Europe is the second-largest market, characterized by stringent regulatory standards and a high concentration of established service providers such as Securitas and GardaWorld. The European market is expected to grow at a 12.8% CAGR, driven by cross-border security initiatives and sports event security (e.g., UEFA tournaments).
Asia-Pacific is the fastest-growing region, with a projected CAGR of 18.2% from 2026 to 2034. Urbanization, rising security threats, and increased defense budgets in China, India, and Southeast Asian countries are key drivers. Our interviews with regional security heads indicate that K9 deployment in India's airports and railway stations alone is expected to triple by 2030. The Middle East & Africa region is also emerging, with GCC countries investing heavily in critical infrastructure protection.
The market is moderately fragmented, with a mix of global security giants, specialized K9 service providers, and technology integrators. Key players include Allied Universal, Securitas, GardaWorld, Pinkerton, VSE Corporation, American K9, K2 Solutions, Prosegur, Brinks, Transguard, SIS, Paladin Security, Commissionaires, OCS Group, and Mitie. While global firms benefit from scale and integrated service offerings, specialized firms compete on training quality, breed specialization, and niche expertise.
Recent developments signal a trend towards consolidation and technological differentiation:
Strategic imperatives for competitors include investing in technology integration, expanding into emerging markets, and developing subscription-based service models to lower adoption barriers for SMEs. Our analysis suggests that companies with strong data analytics capabilities will be able to demonstrate superior ROI, commanding premium pricing.
The K9 security service market is primarily service-based, but the supply of trained dogs and related equipment involves significant cross-border trade. The global trade in live dogs for security purposes (HS code 0106.19) is estimated at USD 250–300 million annually, with major exporters including Germany, the Netherlands, and the United States. These countries have established breeding and training infrastructures that produce high-quality working dogs.
| Country/Region | Role in Supply Chain | Key Characteristics |
|---|---|---|
| Germany | Leading exporter of working dogs (Shepherds, Malinois) | Stringent breeding standards, high demand for German Shepherd bloodlines |
| Netherlands | Major exporter of trained detection dogs | Advanced training methods, strong veterinary support |
| United States | Both importer and exporter; large domestic breeding programs | High demand for explosive detection dogs; imports from Europe to meet shortfall |
| China | Growing importer and domestic breeder | Increasing government investment in K9 units; still reliant on imports for elite detection dogs |
| Middle East | Importer, with some domestic breeding in UAE and Saudi Arabia | High spending on security; preference for European-bred dogs |
Supply chain risks include disease outbreaks (e.g., canine influenza), transportation restrictions, and geopolitical tensions affecting trade flows. Our interviews with procurement managers highlight that diversification of sourcing is a key strategy to mitigate these risks, with some agencies now developing domestic breeding programs.
Several untapped opportunities exist for stakeholders:
The canine security service market is poised for a decade of robust growth, driven by escalating security needs and technological advancements. The projected USD 4.84 billion market by 2034 represents a significant opportunity for service providers, technology firms, and investors. Success will hinge on the ability to innovate—both in training and technology—and to expand into fast-growing regions. Stakeholders must act decisively to capture share in this expanding market, as the competitive landscape will intensify. Our research indicates that the market's trajectory is upward and resilient, making it a compelling sector for strategic investment.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.30% from 2020-2034 |
| Segmentation |
|
By Operating Environment
By Customer Type
By Organization Size
By Industry Vertical
By Security Use Case
| By Geography |
|
Our proprietary forecast indicates the global K9 security service market will reach USD 4.84 billion by 2034, expanding at a CAGR of 14.30% from 2026 to 2034.
North America held the largest share in 2025, accounting for 48.5% of the global market, driven by high government spending and advanced security infrastructure.
Escalating terrorism threats, regulatory mandates for detection services, and technological integration such as GPS tracking and body-worn cameras are primary drivers.
Leading players include Allied Universal, Securitas, GardaWorld, VSE Corporation, Pinkerton, K2 Solutions, and American K9, among others.
Mobile deployment is the fastest-growing segment, projected to grow at a CAGR of 16.5% through 2034, due to demand for flexible security at events and urban patrols.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| K9 Unit Commanders | 35% |
| Procurement Directors | 25% |
| Security Managers | 20% |
| Training Academy Directors | 15% |
| Technology Vendors | 5% |
| Company Type | Representation (%) |
|---|---|
| K9 Training Academies | 30% |
| Security Service Providers | 25% |
| Technology Integrators | 20% |
| Government Agencies | 15% |
| Breeding & Supply Firms | 10% |