1What is the size of the Analytics-as-a-Service market in 2025?
The global Analytics-as-a-Service market is estimated at USD 15.03 Billion in 2025 and is projected to reach USD 174.97 Billion by 2035, growing at a CAGR of 27.82%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Analytics-as-a-Service
 by Component (Solutions, Services), by Analytics Type (Descriptive, Predictive, Prescriptive, Diagnostic), by Enterprise Size (Large Enterprise, Small & Medium Enterprise), by End-Use (BFSI, Retail, Government, IT & Telecom, Healthcare, Manufacturing, Other End-Uses), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Rest of Europe), by Asia Pacific (China, Japan, India, Southeast Asia, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (GCC, South Africa, Rest of Middle East & Africa) Forecast 2026-2034

Senior Analyst


 Related Reports

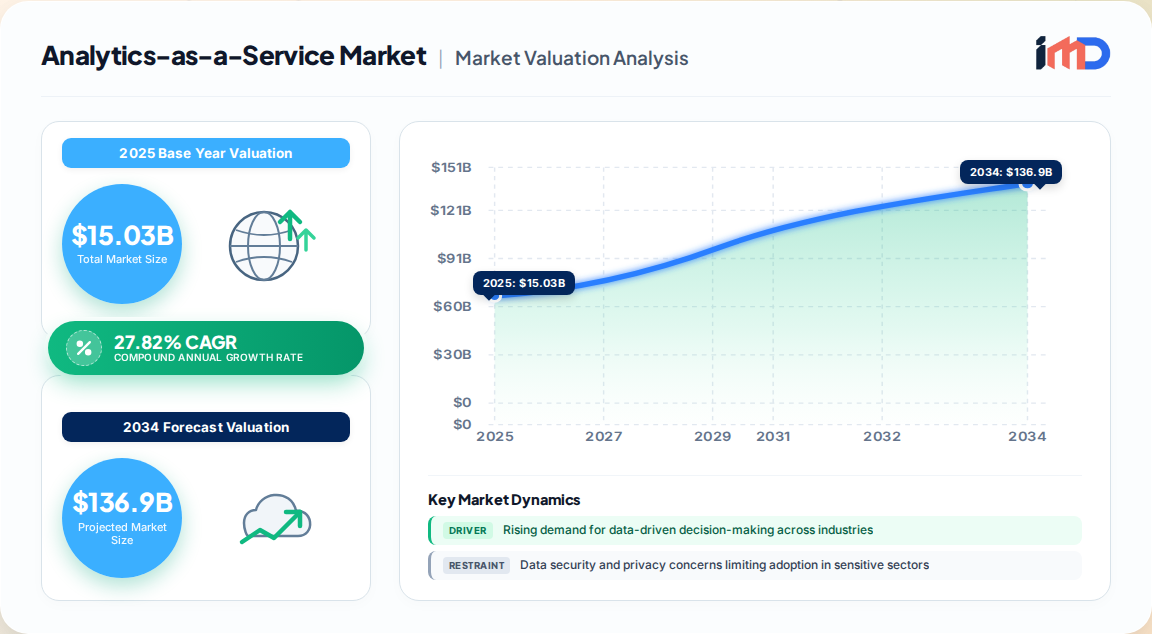
The Analytics-as-a-Service (AaaS) market represents a paradigm shift in how organizations consume analytical capabilities. Our proprietary primary research estimates the global market at USD 15.03 Billion in 2025, projected to reach USD 174.97 Billion by 2035, expanding at a CAGR of 27.82%. This growth is underpinned by the migration of analytics workloads from on-premise infrastructure to cloud-native, subscription-based models that lower total cost of ownership and accelerate time-to-insight.
AaaS delivers data management, advanced analytics, and AI-driven insight generation over the cloud, enabling enterprises to bypass capital-intensive infrastructure and specialized data science hiring. The market's trajectory reflects a structural shift in enterprise IT spending: analytics is no longer a support function but a core driver of competitive strategy, demand sensing, and operational resilience.
The analytics type landscape reflects a maturing buyer sophistication:
| Segment | Market Position | Key Demand Drivers |
|---|---|---|
| Descriptive | Largest share (~35%) in 2025 | Historical performance analysis, customer segmentation, operational reporting |
| Predictive | Dominant in forward-looking use cases (~28.3% share in 2023) | Demand forecasting, risk scoring, churn prediction, preventive maintenance |
| Prescriptive | Fastest-growing CAGR | Optimization engines, decision intelligence, automated recommendations |
| Diagnostic | Niche but essential | Root-cause analysis, anomaly detection, incident investigation |
The BFSI sector holds the largest end-use share at approximately 25.1–28% in 2025, reflecting the criticality of analytics for fraud detection, credit risk modeling, regulatory reporting, and customer personalization. Other high-growth verticals include retail (demand sensing, assortment optimization), healthcare (population health, clinical decision support), manufacturing (predictive maintenance, quality analytics), and the public sector (policy analytics, service optimization).
North America remains the largest regional market, commanding approximately 35–38.5% revenue share in 2025, supported by advanced cloud infrastructure, mature analytics vendor ecosystems, and early adoption of AI-driven platforms. The region's dominance is reinforced by strong venture funding for analytics startups and a concentration of hyperscale data centers.
Asia-Pacific is the fastest-growing region, propelled by rapid digital transformation, expanding cloud infrastructure, and government-led data modernization initiatives. The region is expected to deliver the highest CAGR over the forecast period, with China, India, Japan, and Southeast Asia as key growth engines.
Europe maintains a strong position, with growth shaped by GDPR compliance requirements and a focus on data sovereignty. The region's demand for governed analytics and privacy-enhancing technologies is creating differentiated opportunities for AaaS providers.
South America and the Middle East & Africa are emerging markets, with growth concentrated in BFSI, telecommunications, and public sector digitalization. Infrastructure gaps and currency volatility remain headwinds, but mobile-first analytics adoption is accelerating.
The AaaS market is characterized by a concentrated competitive structure, with hyperscale cloud providers and enterprise software incumbents controlling the majority of revenue. Key players include IBM, Microsoft, Google, Amazon, SAP, Oracle, Salesforce, SAS, Tableau, and Qlik.
Strategic positioning varies across the competitive spectrum:
Recent competitive activity reflects a focus on AI integration and cloud modernization. IBM has advanced analytics capabilities through its watsonx platform, enabling AI-driven insight generation and governance. Microsoft has enhanced Microsoft Fabric with agentic AI capabilities and expanded Copilot functionality to simplify enterprise data management. Google Cloud has invested heavily in data analytics capabilities, reinforcing its position as a leading platform provider.
Our analysis identifies several underserved opportunity areas for AaaS providers:
The AaaS value chain spans infrastructure, platform, and insight delivery layers:
Value chain dynamics are shifting toward embedded analytics, where AaaS capabilities are delivered within business applications, and toward data monetization, where analytics services themselves become revenue-generating products for end customers.
As a digital service, AaaS does not conform to traditional trade goods classifications, but cross-border data flows and digital service trade frameworks are materially shaping market dynamics. Key considerations include:
Organizations procuring AaaS must evaluate supplier resilience, data portability, and exit management capabilities alongside functional requirements to mitigate concentration risk.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 27.82% from 2020-2034 |
| Segmentation |
|
By Enterprise Size
By End-Use
| By Geography |
|
The global Analytics-as-a-Service market is estimated at USD 15.03 Billion in 2025 and is projected to reach USD 174.97 Billion by 2035, growing at a CAGR of 27.82%.
North America holds the largest regional share at approximately 35–38.5% of global revenue, supported by advanced cloud infrastructure and early AI adoption. Asia-Pacific is the fastest-growing region.
Key drivers include rising demand for data-driven decision-making, cloud adoption and scalability, AI/ML integration, real-time analytics imperatives, regulatory compliance requirements, and cost efficiency mandates.
The BFSI sector holds the largest end-use share at approximately 25.1–28% in 2025, driven by fraud detection, credit risk modeling, and regulatory reporting needs.
Key players include IBM, Microsoft, Google, Amazon, SAP, Oracle, Salesforce, SAS, Tableau, and Qlik. Hyperscale cloud providers collectively command an estimated 60–70% market share.
Prescriptive analytics is the fastest-growing segment, driven by optimization engines, decision intelligence, and automated recommendation capabilities across industries such as healthcare, finance, and manufacturing.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Data Officer / Chief Analytics Officer | 30% |
| VP of Data Engineering / Head of Business Intelligence | 25% |
| IT Procurement Director | 25% |
| Cloud Infrastructure & Platform Architect | 20% |
| Company Type | Representation (%) |
|---|---|
| Hyperscale Cloud & AaaS Platform Providers | 30% |
| Enterprise Software Incumbents | 20% |
| Managed Analytics Service Providers | 20% |
| Enterprise End-User Organizations | 20% |
| Industry Consultants & Systems Integrators | 10% |