Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Netherlands Solar Energy Market Size, CAGR & Forecast 2031
Netherlands Solar Energy Market
Energy & Power / MARKET REPORT
Netherlands Solar Energy Market | Insight Market Data
Netherlands Solar Energy Market by Technology (Solar Photovoltaic (PV), Concentrated Solar Power (CSP)), by Grid Type (On-Grid, Off-Grid), by End-User (Utility-Scale, Commercial and Industrial (C&I), Residential), by Component (Solar Modules, Inverters (String, Central, Micro), Mounting and Tracking Systems, Balance-of-System and Electricals, Energy Storage and Hybrid Integration), by Netherlands (Noord-Brabant, Limburg, Zuid-Holland, Noord-Holland, Gelderland, Overijssel, Friesland, Drenthe, Groningen, Flevoland) Forecast 2026-2034
India renewable energy market is projected to reach USD 159.81 Billion by 2035, growing at a CAGR of 7.36% from 2026 to 2035, driven by solar and wind.
The Semi-Submersible Drilling Rig Industry market was valued at USD 24.6 Billion in 2025 and is projected to reach USD 41.2 Billion by 2033, growing at a 6.7% CAGR.
Nov 2026|275 pages
$2900.00
West Africa refined petroleum products market to reach USD 78.62 billion by 2031 at 4.88% CAGR. Dangote, subsidy reform and LPG drive demand.
Nov 2026|251 pages
$2900.00
Marine solid state circuit breaker market to reach USD 1.24 Billion by 2035 at 9.2% CAGR, driven by vessel electrification and DC grid adoption.
Nov 2026|251 pages
$2900.00
Micro-Dramas Production market at $10.63B in 2025, growing 26.1% CAGR to $53.9B by 2032. Vertical-screen content, monetization and regional analysis.
Executive Overview: The Netherlands Solar Energy Market
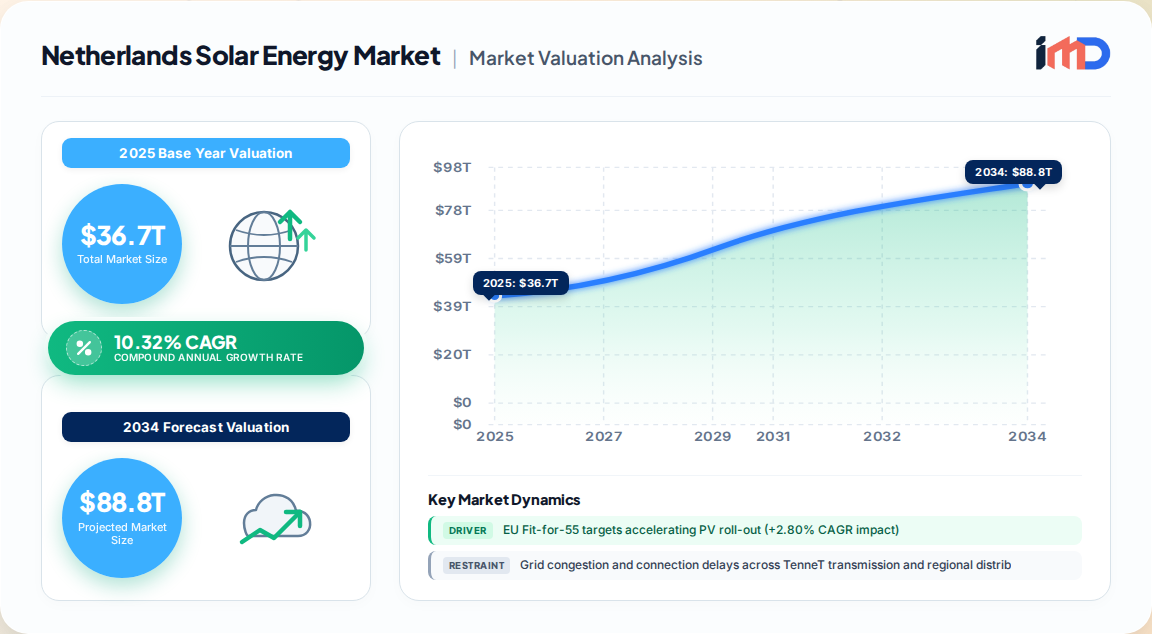
The Netherlands solar energy market stands at an inflection point. Our proprietary primary research estimates installed capacity at 36.7 gigawatt (GW) in 2026, rising from 33.27 GW in 2025, with a forecast trajectory reaching 59.95 GW by 2031 at a 10.32% CAGR. The Dutch market is no longer a policy-driven niche; it is a mature, subsidy-independent capacity engine where economics, corporate procurement and grid engineering determine outcomes.
Netherlands Solar Energy Market Market Size (In Million)
75.0M
60.0M
45.0M
30.0M
15.0M
0
37.00 M
2025
40.00 M
2026
45.00 M
2027
49.00 M
2028
54.00 M
2029
60.00 M
2030
66.00 M
2031
Three structural forces define the 2026–2031 window:
The 2027 phase-out of net metering (salderingsregeling) is pulling residential and small commercial demand forward into a short-term installation rush.
Corporate power purchase agreements (PPAs) from data-center operators and retail majors in the Amsterdam–Rotterdam corridor are shifting demand from rooftops to merchant-exposed utility-scale assets.
Grid congestion, not land or capital, has become the binding constraint, redirecting capital toward hybrid solar-plus-storage, agrivoltaics and curtailment-mitigation designs.
Market concentration is low; no single developer controls a dominant share of installed capacity, and the competitive field spans integrated utilities, independent power producers, cooperatives and rooftop aggregators.
Market Metric
Value
Base year capacity (2025)
33.27 GW
Estimated capacity (2026)
36.7 GW
Forecast capacity (2031)
59.95 GW
Growth rate (2026–2031)
10.32% CAGR
Market concentration
Low
Dominant technology
Solar PV (100% of capacity)
Demand Drivers and Structural Growth Catalysts
Our driver-impact modelling isolates four forces with quantified influence on the forecast CAGR:
Driver
Impact on CAGR
Relevant Horizon
EU Fit-for-55 targets accelerating PV roll-out
+2.80%
Long term (4+ years)
Pre-cutoff rush ahead of net-metering phase-out
+1.90%
Short term (≤2 years)
Corporate PPAs from data-center and retail giants
+2.30%
Medium term (2–4 years)
Levelized cost of electricity below EUR 0.04/kWh
+1.70%
Utility-scale, ongoing
Dutch solar economics have crossed the threshold where new build competes on cost alone. Sub-EUR 0.04/kWh utility LCoE makes PV the cheapest new-build generation in the country, insulating the market from subsidy withdrawal.
The data-center cluster in the Amsterdam and Rotterdam corridors provides a uniquely Dutch demand anchor. Hyperscaler and colocation operators require 24/7 clean power, and hybrid solar-plus-storage PPAs are becoming the preferred contracting structure to secure evening-hour supply and satisfy corporate decarbonization mandates.
Agrivoltaic incentives are unlocking dual-use land on Dutch farmland, partially offsetting land scarcity. Dual-use installations allow continued agricultural activity while generating electricity, improving project acceptance at municipal level.
Market Restraints, Challenges and Grid Constraints
The most significant restraint is grid capacity, not demand. Congestion in large parts of the TenneT transmission network and regional distribution grids is delaying connection dates and forcing developers into curtailment-exposed positions.
Land scarcity: The Netherlands is one of Europe's most densely populated countries; ground-mounted development competes with agriculture, housing and logistics.
Grid integration costs: Intermittency management requires storage co-location, adding capital expenditure per MW.
Permitting complexity: Municipal and provincial spatial planning rules create project-by-project uncertainty.
Negative price exposure: Rising midday solar penetration is compressing capture prices, pressuring merchant business cases.
Developer response is strategic: hybrid solar-plus-storage designs, grid-friendly inverter configurations and curtailment-mitigation investments are concentrated in grid-constrained zones through 2028.
Segmentation Analysis
Technology
Photovoltaic systems accounted for 100% of installed capacity in 2025. Concentrated solar power has no material footprint in Dutch conditions given diffuse irradiance; all forward capacity additions are PV-driven, spanning monofacial, bifacial and building-integrated formats.
Grid Type
Grid Type
Share of Capacity (2025)
Growth Outlook
On-grid
98.62%
Core of capacity base
Off-grid
1.38%
15.21% CAGR to 2031
Off-grid's rapid growth is small in absolute terms but strategically relevant for agricultural sites, infrastructure assets and remote industrial applications where connection queues are prohibitive.
End-User
Commercial and industrial (C&I) projects grew 13.78% year over year in 2025 and are set to outpace utility-scale additions through 2031. The segment benefits from large flat-roof logistics real estate, warehouse portfolios and corporate sustainability reporting obligations. Utility-scale remains the largest single capacity block but faces the steepest grid constraints; residential demand is front-loaded ahead of the 2027 metering change.
Regional Outlook: Provincial Capacity Distribution
Capacity is concentrated in the southern and western provinces. Noord-Brabant and Limburg together accounted for 34.78% of installed capacity in 2025, reflecting available industrial land, logistics rooftops and supportive provincial energy strategies.
Netherlands Solar Energy Market Regional Market Share
Loading chart...
Province Cluster
Positioning
Noord-Brabant and Limburg
Largest combined capacity base; continued C&I rooftop strength
Zuid-Holland and Noord-Holland
Urban rooftop density plus data-center PPA demand
Gelderland and Overijssel
Ground-mounted and agrivoltaic growth
Northern provinces
Lower capacity, emerging large-scale potential
Grid-constrained zones are forecast to register the highest curtailment-mitigation investment through 2028, creating a distinct sub-market for storage integration.
Competitive Landscape and Strategic Positioning
The market is fragmented. Integrated energy majors, independent solar developers, cooperatives and rooftop aggregators all hold meaningful positions, with no player approaching dominance.
Leading and notable participants include: Solarfields Nederland BV, DMEGC Solar Energy, Vattenfall AB, Orsted A/S, AB Solar Total, Shell plc (Renewables), Eneco Groep N.V., BayWa r.e. AG, Chint Solar Netherlands B.V., GroenLeven B.V., Sunrock Investment B.V., Statkraft (Netherlands), ENGIE Nederland N.V., TenneT Holding B.V., Canadian Solar Inc., First Solar Inc., Trina Solar Co. Ltd., JinkoSolar Holding Co. Ltd., LONGi Green Energy, Hanwha Q-Cells, GoodWe Europe GmbH, and SMA Solar Technology AG.
Winning strategies we observe:
Integrated utility developers (Vattenfall, Eneco, ENGIE, Orsted) leveraging balance-sheet strength to underwrite merchant and PPA-backed portfolios.
Specialist developers (Solarfields, GroenLeven, Sunrock) securing development pipelines and rooftop aggregation rights before grid capacity is allocated.
Module and inverter suppliers (DMEGC, Chint, Canadian Solar, Trina, JinkoSolar, LONGi, Hanwha Q-Cells, SMA, GoodWe) competing on efficiency, bifacial performance and hybrid inverter capability.
TenneT as the grid architect whose reinforcement schedule effectively governs project timelines across the country.
Value Chain and Supplier Dynamics
The Dutch PV value chain is heavily import-dependent for modules, cells and wafers, with domestic value concentrated in development, engineering, procurement and construction (EPC), mounting systems, installation and O&M services.
Upstream: Module supply is sourced predominantly from Asian manufacturing capacity; inventory cycles and trade policy affect project margins.
Midstream: Dutch EPC and installation firms hold strong localized capability, particularly in rooftop and building-integrated applications.
Downstream: Asset ownership is diversifying toward cooperatives, infrastructure funds and corporate self-consumption models.
Supply chain risk is concentrated in module price volatility and inverter lead times rather than raw material scarcity. Developers increasingly contract modules on frame agreements to protect project economics against spot-price swings.
Market Opportunities and Future Outlook
The 2026–2031 outlook supports a resilient growth story anchored by EU Fit-for-55 compliance and grid modernization.
Solar-plus-storage hybridisation offers the clearest revenue upside, capturing premium evening-hour prices and reducing curtailment losses.
Floating solar on inland waters addresses land scarcity and has strong municipal support in water-rich provinces.
Agrivoltaics converts land constraint into dual-use opportunity with policy incentives.
Grid reinforcement investment by TenneT will progressively release connection capacity, unblocking stalled utility pipelines toward 2030.
Our proprietary modelling indicates that annual additions must accelerate materially after the 2027 metering transition, with C&I and hybrid utility projects carrying the incremental volume required to reach 59.95 GW by 2031.
Netherlands Solar Energy Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Netherlands Solar Energy Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.32% from 2020-2034
Segmentation
By Technology
Solar Photovoltaic
PV
Concentrated Solar Power
CSP
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. EU Fit-for-55 targets accelerating PV roll-out (+2.80% CAGR impact)
3.1.2. Phase-out of net-metering after 2025 spurring pre-cutoff rush (+1.90% CAGR impact)
3.1.3. Corporate PPAs from data-center and retail giants (+2.30% CAGR impact)
3.5.1. Managing curtailment risk and negative price exposure at high solar penetration
3.5.2. Securing grid connection capacity in congested zones
3.5.3. Financing storage co-location to maintain project economics
3.5.4. Navigating permitting and municipal acceptance for large ground-mounted projects
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Technology
5.1.1. Solar Photovoltaic
5.1.1.1. PV
5.1.2. Concentrated Solar Power
5.1.2.1. CSP
5.2. Market Analysis, Insights and Forecast - by Grid Type
5.2.1. On-Grid
5.2.2. Off-Grid
5.3. Market Analysis, Insights and Forecast - by End-User
5.3.1. Utility-Scale
5.3.2. Commercial and Industrial
5.3.2.1. C&I
5.3.3. Residential
5.4. Market Analysis, Insights and Forecast - by Component
5.4.1. Solar Modules
5.4.2. Inverters
5.4.2.1. String
5.4.2.2. Central
5.4.2.3. Micro
5.4.3. Mounting and Tracking Systems
5.4.4. Balance-of-System and Electricals
5.4.5. Energy Storage and Hybrid Integration
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. Netherlands
6. Competitive Analysis
6.1. Company Profiles
6.1.1. Solarfields Nederland BV
6.1.1.1. Company Overview
6.1.1.2. Products
6.1.1.3. Company Financials
6.1.1.4. SWOT Analysis
6.1.2. DMEGC Solar Energy
6.1.2.1. Company Overview
6.1.2.2. Products
6.1.2.3. Company Financials
6.1.2.4. SWOT Analysis
6.1.3. Vattenfall AB
6.1.3.1. Company Overview
6.1.3.2. Products
6.1.3.3. Company Financials
6.1.3.4. SWOT Analysis
6.1.4. Orsted A/S
6.1.4.1. Company Overview
6.1.4.2. Products
6.1.4.3. Company Financials
6.1.4.4. SWOT Analysis
6.1.5. AB Solar Total
6.1.5.1. Company Overview
6.1.5.2. Products
6.1.5.3. Company Financials
6.1.5.4. SWOT Analysis
6.1.6. Shell plc (Renewables)
6.1.6.1. Company Overview
6.1.6.2. Products
6.1.6.3. Company Financials
6.1.6.4. SWOT Analysis
6.1.7. Eneco Groep N.V.
6.1.7.1. Company Overview
6.1.7.2. Products
6.1.7.3. Company Financials
6.1.7.4. SWOT Analysis
6.1.8. BayWa r.e. AG
6.1.8.1. Company Overview
6.1.8.2. Products
6.1.8.3. Company Financials
6.1.8.4. SWOT Analysis
6.1.9. Chint Solar Netherlands B.V.
6.1.9.1. Company Overview
6.1.9.2. Products
6.1.9.3. Company Financials
6.1.9.4. SWOT Analysis
6.1.10. GroenLeven B.V.
6.1.10.1. Company Overview
6.1.10.2. Products
6.1.10.3. Company Financials
6.1.10.4. SWOT Analysis
6.1.11. Sunrock Investment B.V.
6.1.11.1. Company Overview
6.1.11.2. Products
6.1.11.3. Company Financials
6.1.11.4. SWOT Analysis
6.1.12. Statkraft (Netherlands)
6.1.12.1. Company Overview
6.1.12.2. Products
6.1.12.3. Company Financials
6.1.12.4. SWOT Analysis
6.1.13. ENGIE Nederland N.V.
6.1.13.1. Company Overview
6.1.13.2. Products
6.1.13.3. Company Financials
6.1.13.4. SWOT Analysis
6.1.14. TenneT Holding B.V.
6.1.14.1. Company Overview
6.1.14.2. Products
6.1.14.3. Company Financials
6.1.14.4. SWOT Analysis
6.1.15. Canadian Solar Inc.
6.1.15.1. Company Overview
6.1.15.2. Products
6.1.15.3. Company Financials
6.1.15.4. SWOT Analysis
6.1.16. First Solar Inc.
6.1.16.1. Company Overview
6.1.16.2. Products
6.1.16.3. Company Financials
6.1.16.4. SWOT Analysis
6.1.17. Trina Solar Co. Ltd.
6.1.17.1. Company Overview
6.1.17.2. Products
6.1.17.3. Company Financials
6.1.17.4. SWOT Analysis
6.1.18. JinkoSolar Holding Co. Ltd.
6.1.18.1. Company Overview
6.1.18.2. Products
6.1.18.3. Company Financials
6.1.18.4. SWOT Analysis
6.1.19. LONGi Green Energy
6.1.19.1. Company Overview
6.1.19.2. Products
6.1.19.3. Company Financials
6.1.19.4. SWOT Analysis
6.1.20. Hanwha Q-Cells
6.1.20.1. Company Overview
6.1.20.2. Products
6.1.20.3. Company Financials
6.1.20.4. SWOT Analysis
6.1.21. GoodWe Europe GmbH
6.1.21.1. Company Overview
6.1.21.2. Products
6.1.21.3. Company Financials
6.1.21.4. SWOT Analysis
6.1.22. SMA Solar Technology AG
6.1.22.1. Company Overview
6.1.22.2. Products
6.1.22.3. Company Financials
6.1.22.4. SWOT Analysis
6.2. Market Entropy
6.2.1. Company's Key Areas Served
6.2.2. Recent Developments
6.3. Company Market Share Analysis, 2026
6.3.1. Top 5 Companies Market Share Analysis
6.3.2. Top 3 Companies Market Share Analysis
6.4. List of Potential Customers
List of Figures
Figure 1: Global Netherlands Solar Energy Market Revenue Breakdown (Gigawatt, %) by Region 2026 & 2034
Figure 2: Global Netherlands Solar Energy Market Volume Breakdown (Gigawatt, %) by Region 2026 & 2034
Figure 3: Netherlands Netherlands Solar Energy Market Revenue (Gigawatt), by Technology 2026 & 2034
Figure 4: Netherlands Netherlands Solar Energy Market Volume (Gigawatt), by Technology 2026 & 2034
Figure 5: Netherlands Netherlands Solar Energy Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: Netherlands Netherlands Solar Energy Market Volume Share (%), by Technology 2026 & 2034
Figure 7: Netherlands Netherlands Solar Energy Market Revenue (Gigawatt), by Grid Type 2026 & 2034
Figure 8: Netherlands Netherlands Solar Energy Market Volume (Gigawatt), by Grid Type 2026 & 2034
Figure 9: Netherlands Netherlands Solar Energy Market Revenue Share (%), by Grid Type 2026 & 2034
Figure 10: Netherlands Netherlands Solar Energy Market Volume Share (%), by Grid Type 2026 & 2034
Figure 11: Netherlands Netherlands Solar Energy Market Revenue (Gigawatt), by End-User 2026 & 2034
Figure 12: Netherlands Netherlands Solar Energy Market Volume (Gigawatt), by End-User 2026 & 2034
Figure 13: Netherlands Netherlands Solar Energy Market Revenue Share (%), by End-User 2026 & 2034
Figure 14: Netherlands Netherlands Solar Energy Market Volume Share (%), by End-User 2026 & 2034
Figure 15: Netherlands Netherlands Solar Energy Market Revenue (Gigawatt), by Component 2026 & 2034
Figure 16: Netherlands Netherlands Solar Energy Market Volume (Gigawatt), by Component 2026 & 2034
Figure 17: Netherlands Netherlands Solar Energy Market Revenue Share (%), by Component 2026 & 2034
Figure 18: Netherlands Netherlands Solar Energy Market Volume Share (%), by Component 2026 & 2034
Figure 19: Netherlands Netherlands Solar Energy Market Revenue (Gigawatt), by Country 2026 & 2034
Figure 20: Netherlands Netherlands Solar Energy Market Volume (Gigawatt), by Country 2026 & 2034
Figure 21: Netherlands Netherlands Solar Energy Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Netherlands Netherlands Solar Energy Market Volume Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Netherlands Solar Energy Market Revenue Gigawatt Forecast, by Technology 2020 & 2034
Table 2: Global Netherlands Solar Energy Market Volume Gigawatt Forecast, by Technology 2020 & 2034
Table 3: Global Netherlands Solar Energy Market Revenue Gigawatt Forecast, by Grid Type 2020 & 2034
Table 4: Global Netherlands Solar Energy Market Volume Gigawatt Forecast, by Grid Type 2020 & 2034
Table 5: Global Netherlands Solar Energy Market Revenue Gigawatt Forecast, by End-User 2020 & 2034
Table 6: Global Netherlands Solar Energy Market Volume Gigawatt Forecast, by End-User 2020 & 2034
Table 7: Global Netherlands Solar Energy Market Revenue Gigawatt Forecast, by Component 2020 & 2034
Table 8: Global Netherlands Solar Energy Market Volume Gigawatt Forecast, by Component 2020 & 2034
Table 9: Global Netherlands Solar Energy Market Revenue Gigawatt Forecast, by Region 2020 & 2034
Table 10: Global Netherlands Solar Energy Market Volume Gigawatt Forecast, by Region 2020 & 2034
Table 11: Netherlands Netherlands Solar Energy Market Revenue Gigawatt Forecast, by Technology 2020 & 2034
Table 12: Netherlands Netherlands Solar Energy Market Volume Gigawatt Forecast, by Technology 2020 & 2034
Table 13: Netherlands Netherlands Solar Energy Market Revenue Gigawatt Forecast, by Grid Type 2020 & 2034
Table 14: Netherlands Netherlands Solar Energy Market Volume Gigawatt Forecast, by Grid Type 2020 & 2034
Table 15: Netherlands Netherlands Solar Energy Market Revenue Gigawatt Forecast, by End-User 2020 & 2034
Table 16: Netherlands Netherlands Solar Energy Market Volume Gigawatt Forecast, by End-User 2020 & 2034
Table 17: Netherlands Netherlands Solar Energy Market Revenue Gigawatt Forecast, by Component 2020 & 2034
Table 18: Netherlands Netherlands Solar Energy Market Volume Gigawatt Forecast, by Component 2020 & 2034
Table 19: Netherlands Netherlands Solar Energy Market Revenue Gigawatt Forecast, by Country 2020 & 2034
Table 20: Netherlands Netherlands Solar Energy Market Volume Gigawatt Forecast, by Country 2020 & 2034
Table 21: Noord-Brabant Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 22: Noord-Brabant Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 23: Limburg Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 24: Limburg Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 25: Zuid-Holland Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 26: Zuid-Holland Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 27: Noord-Holland Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 28: Noord-Holland Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 29: Gelderland Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 30: Gelderland Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 31: Overijssel Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 32: Overijssel Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 33: Friesland Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 34: Friesland Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 35: Drenthe Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 36: Drenthe Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 37: Groningen Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 38: Groningen Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Table 39: Flevoland Netherlands Solar Energy Market Revenue (Gigawatt) Forecast, by Application 2020 & 2034
Table 40: Flevoland Netherlands Solar Energy Market Volume (Gigawatt) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size of the Netherlands solar energy market in 2026?
Our proprietary primary research estimates the Netherlands solar energy market at 36.7 GW of installed capacity in 2026, up from 33.27 GW in 2025. The market is forecast to reach 59.95 GW by 2031 at a 10.32% CAGR.
2Which technology dominates the Netherlands solar energy market?
Solar photovoltaic systems held 100% of installed capacity in 2025. Concentrated solar power has no material presence given the Netherlands' diffuse irradiance profile, so all forward capacity additions are PV-driven.
3What is driving growth in the Netherlands solar energy market?
Key drivers include EU Fit-for-55 targets (+2.80% CAGR impact), the pre-2027 net-metering phase-out rush (+1.90%), corporate PPAs from data-center and retail giants (+2.30%), and utility LCoE falling below EUR 0.04/kWh (+1.70%).
4Who are the major companies in the Netherlands solar energy market?
Leading participants include Solarfields Nederland BV, DMEGC Solar Energy, Vattenfall AB, Orsted A/S, AB Solar Total, Shell plc (Renewables), Eneco Groep N.V., BayWa r.e. AG, GroenLeven B.V. and Sunrock Investment B.V., alongside module suppliers such as Canadian Solar, Trina Solar and LONGi.
5Which region of the Netherlands holds the largest solar capacity?
Noord-Brabant and Limburg together accounted for 34.78% of installed capacity in 2025. However, grid-constrained zones are expected to attract the highest curtailment-mitigation investment through 2028.
6What is the outlook for off-grid solar in the Netherlands?
Off-grid installations are small in absolute terms at roughly 1.38% of capacity but are advancing at a 15.21% CAGR toward 2031, driven by agricultural sites, infrastructure assets and locations facing grid connection queues.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary research, generating first-party, interview-based evidence across the Dutch solar value chain.
We conduct structured interviews and expert consultations with developers and independent power producers, EPC and O&M contractors, module, inverter and mounting-system suppliers, corporate offtakers and PPA advisors, and grid operators and distribution system operators.
Typical interviewees include Head of Project Development, Chief Commercial Officer (Solar IPP), Procurement Director (Modules and Inverters), and Grid Connection and Regulatory Affairs Manager.
We validate findings against recognized industry and regulatory bodies, including SolarPower Europe, Holland Solar, TenneT TSO B.V., and RVO (Netherlands Enterprise Agency).
Bottom-up capacity build is computed from MW connected per province, average module wattage and project DC/AC ratio, and annual installation permits and SDE++ award volumes.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of Project Development
32%
Chief Commercial Officer / Solar IPP Executive
26%
Procurement Director
24%
Grid Connection & Regulatory Affairs Manager
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Solar Developers & IPPs
30%
EPC & O&M Contractors
22%
Module, Inverter & Mounting Suppliers
20%
Corporate Offtakers & PPA Advisors
16%
Grid Operators & Regulatory Bodies
12%
Secondary Research & Industry Benchmarking
20–30% of research effort draws on published statistics, filings and technical standards to triangulate primary findings.
Standard financial databases used for company and transaction analysis: Bloomberg, Factiva, Hoovers, and PitchBook.
Trade and capacity benchmarks are cross-checked against national grid statistics and renewable-energy trade association publications; no commercial market research firm data is used.
Every report is updated to the date of purchase to reflect the latest grid, policy and pricing developments.
Demand Modeling & Market Estimation
We run top-down and bottom-up methodologies simultaneously, reconciled through multi-level data triangulation.
Bottom-up modelling aggregates provincial project pipelines, rooftop C&I conversion rates and utility-scale connection queues into a national capacity estimate.
Top-down modelling applies EU and national renewable energy target decomposition against total electricity demand and solar penetration shares.
Scenario analysis applies low, base and high cases around grid release timing, net-metering transition effects and storage co-location adoption.
Outputs are expressed in installed capacity (GW) and revenue, with guaranteed estimated data accuracy of 85–90%.
Data Accuracy & Quality Check
All figures pass a multi-level triangulation process comparing primary interviews, official statistics and company disclosures.
Outlier detection and cross-validation are applied at provincial, segment and end-user levels; inconsistent inputs are re-verified with respondents.
Segment shares are reconciled to sum to the national total; regional shares are reconciled to the aggregate capacity base.
Final deliverables carry a guaranteed estimated data accuracy level of 85–90%, with methodology notes and confidence flags for each forecast series.