1What is the current size of the India renewable energy market?
The India renewable energy market was valued at USD 79.09 Billion in 2025 and is projected to reach USD 159.81 Billion by 2035, growing at a CAGR of 7.36%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 India Renewable Energy Market
 by Technology (Solar Energy, Wind Energy, Hydropower, Bioenergy, Geothermal, Ocean Energy), by End Use (Industrial, Commercial, Residential, Utilities), by Application (Solar Power Generation, Wind Power Generation), by North (India), by South (India), by East (India), by West (India), by Northeast (India) Forecast 2026-2034
Research Analyst


 Related Reports

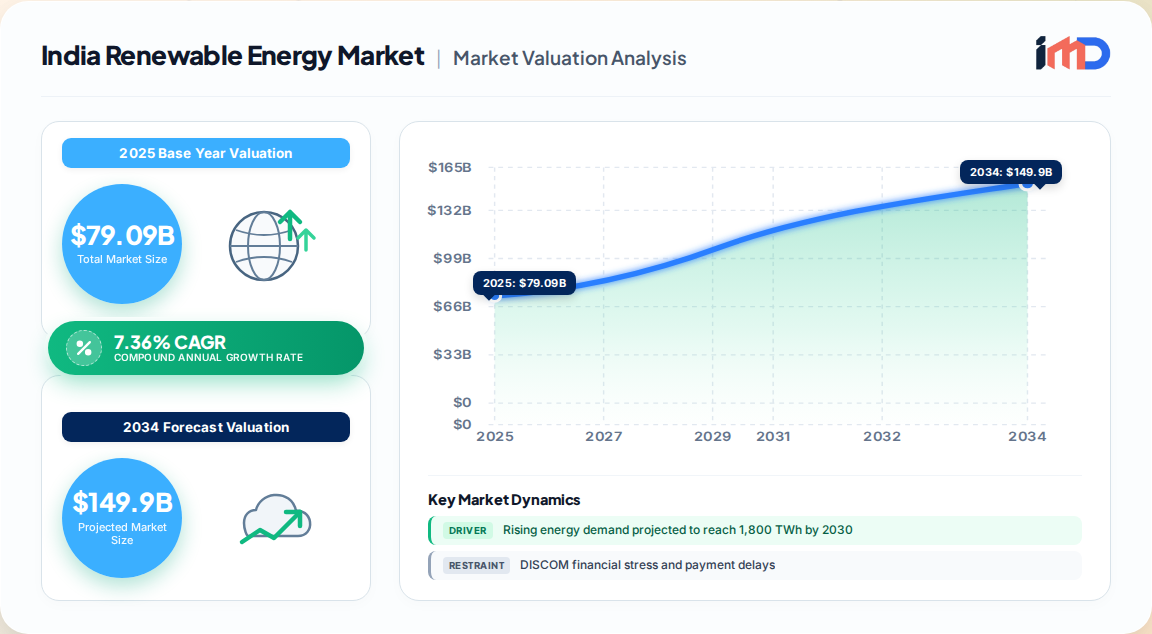
India's renewable energy market is undergoing a structural transformation, positioning itself as one of the most dynamic clean energy ecosystems globally. Our proprietary primary research estimates the market at USD 79.09 Billion in 2025, with a projected expansion to USD 159.81 Billion by 2035, reflecting a CAGR of 7.36% over the forecast period. This growth trajectory is underpinned by an installed base that has already crossed 230.78 GW (excluding large hydro) as of May 2026 and 282.75 GW including large hydro, according to in-house analysis of Ministry of New and Renewable Energy (MNRE) data.
India's renewable sector has evolved from a policy-driven niche to a mainstream investment destination. The country now ranks 3rd globally in renewable energy installed capacity, surpassing Japan to become the world's third-largest solar power producer with 108,494 GWh generated in 2025. This report synthesizes primary interviews with developers, EPC contractors, utility executives, and policymakers to deliver a granular, forward-looking assessment of the market through 2035.
The Indian renewable energy market is propelled by a confluence of demand-side, policy, and technological forces, yet remains constrained by persistent structural bottlenecks.
The market is segmented by technology, end-use sector, and application. Solar energy dominates, while wind and hybrid solutions are gaining momentum.
| Segment | Leading Category | Market Share (2025) | Fastest-Growing Category |
|---|---|---|---|
| By Technology | Solar Energy | 46.6% | Offshore Wind (CAGR 15.04% through 2030) |
| By End Use | Industrial | 47.09% | Commercial (CAGR 18.8% to 2030) |
| By Application | Solar Power Generation | Largest | Wind Power Generation |
| By Energy Source | Solar Energy | Largest | Wind Energy |
India's renewable capacity is geographically concentrated in high-resource states, with the western and southern regions leading deployment.
| Region | Share (% of Installed Capacity) | Key Drivers |
|---|---|---|
| South | 31% | Wind-rich Tamil Nadu, Karnataka solar parks, Andhra Pradesh hybrid tenders |
| West | 27% | Rajasthan solar and hybrid clusters, Gujarat manufacturing and port infrastructure |
| North | 22% | Uttar Pradesh and Punjab rooftop solar, Haryana industrial procurement |
| East | 12% | Emerging solar parks in Odisha, West Bengal bioenergy |
| Northeast | 8% | Small hydro and decentralized solutions |
Rajasthan and Gujarat collectively account for the majority of utility-scale solar and hybrid capacity, benefiting from high irradiance (5.5-6.0 kWh/m²/day) and land availability. Tamil Nadu leads wind with over 10 GW installed. Karnataka and Andhra Pradesh are emerging as storage-integration hubs, supported by state-level auctions for hybrid-plus-storage tenders.
The Indian renewable energy market is moderately concentrated, with large domestic conglomerates and independent power producers (IPPs) driving capacity expansion.
Intense competition in auctions has driven tariffs to record lows, accelerating cost reduction but squeezing developer margins. Strategic differentiation is shifting toward storage integration, hybrid configurations, and corporate PPAs.
India remains a net importer of solar modules, cells, and battery storage systems, though domestic manufacturing is scaling rapidly.
Our primary research identifies several underpenetrated segments with high growth potential:
The renewable energy value chain in India spans raw material supply to project development and O&M, with distinct competitive dynamics at each stage.
| Stage | Key Activities | Major Participants |
|---|---|---|
| Raw Materials | Polysilicon, steel, copper, rare earths | Import-dependent; China, Chile, Australia |
| Manufacturing | Solar modules, cells, wind turbines, batteries | Domestic OEMs (38 GW module capacity, 18 GW turbine capacity) |
| Project Development | Site acquisition, permitting, EPC | IPPs (Tata Power, Adani Green, ReNew, NTPC) |
| Transmission & Grid Integration | Substations, transmission lines, storage | State transmission utilities, SECI |
| Operations & Maintenance | Monitoring, cleaning, asset management | OEMs, third-party O&M providers |
| End Users | Utilities, C&I, residential | DISCOMs, industrial off-takers, households |
Critical mineral supply-chain exposure remains a strategic vulnerability, particularly for solar cells and battery storage. Domestic manufacturing under the PLI scheme is gradually reducing import reliance, but upstream polysilicon and lithium refining capacity remain negligible.
The India renewable energy market is poised for robust growth, with capacity additions expected to double in 2026 relative to the previous year. Key forecasts include:
Strategic priorities for stakeholders include accelerating domestic manufacturing, resolving DISCOM payment delays, streamlining land acquisition, and investing in storage and hybrid solutions to ensure grid reliability. The market's trajectory positions India as a linchpin of the global energy transition, with significant opportunities across the value chain.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.36% from 2020-2034 |
| Segmentation |
|
By End Use
By Application
| By Geography |
|
The India renewable energy market was valued at USD 79.09 Billion in 2025 and is projected to reach USD 159.81 Billion by 2035, growing at a CAGR of 7.36%.
Solar energy dominates with a 46.6% market share in 2024, driven by domestic module manufacturing capacity of 38 GW and record-low tariffs of INR 2.51/kWh.
Key drivers include rising energy demand projected to reach 1,800 TWh by 2030, government targets of 500 GW non-fossil capacity by 2030, and falling LCOE for solar and wind.
As of May 2026, India's installed renewable energy capacity stood at 230.78 GW (excluding large hydro) and 282.75 GW including large hydro, ranking third globally.
Major players include Tata Power, Adani Green Energy, ReNew Power, NTPC Limited, JSW Energy, Sterling and Wilson Solar, Azure Power, Mahindra Susten, and Greenko Energy Holdings.
India targets 500 GW of non-fossil-based electricity generation capacity by 2030, including 100 GW from wind and significant contributions from solar and hybrid projects.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Operating Officer (COO) | 30% |
| Head of Project Development | 30% |
| Procurement Director | 25% |
| Policy Advisor | 15% |
| Company Type | Representation (%) |
|---|---|
| Renewable Energy Project Developers | 35% |
| EPC Contractors | 25% |
| Module and Turbine Manufacturers | 20% |
| Utility Procurement Officers | 12% |
| Policy Regulators | 8% |