1What is the micro-dramas production market size in 2025?
The global micro-dramas production market was valued at US$ 10.63 billion in 2025 and is forecast to reach US$ 53.9 billion by 2032, expanding at a 26.1% CAGR over the 2026–2032 period.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Micro-Dramas Production Market
 by By Type (IAA, IAP(pay per episode, member subscription), Copyright Revenue Sharing, e-commerce Sales), by By Application (Short Video Platforms, Mini Programs, Long Video Platforms, Independent Short Drama Apps), by Asia Pacific (China, Japan, South Korea, Southeast Asia), by North America (United States, Canada, Mexico), by Europe (Germany, UK, France), by Latin America (Brazil, Mexico), by Middle East & Africa (UAE, Saudi Arabia) Forecast 2026-2034
Research Analyst


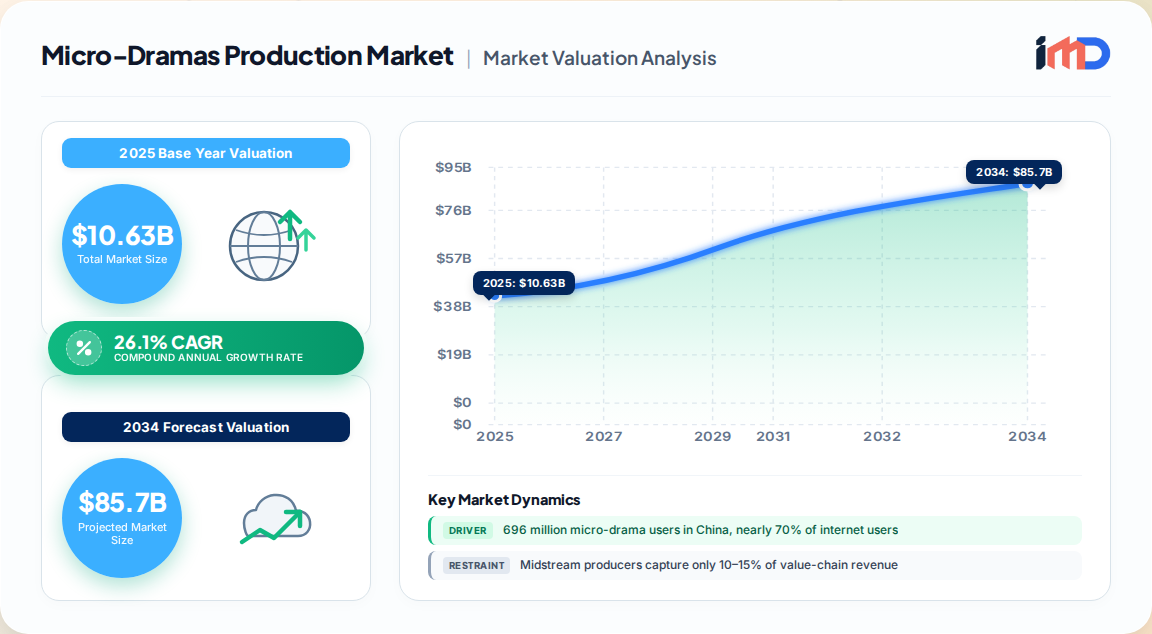
The global micro-dramas production market was valued at US$ 10.63 billion in 2025 and is projected to reach US$ 53.9 billion by 2032, expanding at a 26.1% CAGR across the 2026–2032 forecast horizon. Micro-dramas — vertical-screen scripted series with episodes under ten minutes and lean production budgets — have become the fourth officially recognized online film and television format, following web dramas, web movies, and web animations.
The commercial center of gravity is Asia Pacific, where a mature short-video ecosystem, deep online-literature IP reserves, and creator-driven production capacity have compressed the time from script to monetization to weeks rather than months. China alone hosts over 230 micro-drama-related companies, and engagement is near-universal among the connected population: as of June 2025, domestic micro-drama users reached 696 million, or nearly 70% of all internet users. Platform-level daily recharge consumption for paid micro-dramas in China stands at approximately RMB 60 million per day.
Our proprietary modeling indicates the market is transitioning from a volume-led land-grab into a two-track structure: low-cost, high-frequency content factories serving algorithmic distribution, and premium vertical productions targeting subscription and advertising-supported tiers. Production spend per episode currently ranges from US$ 120,000 to US$ 150,000 for higher-end vertical titles, while the broader independent output is estimated at approximately 40,000 vertically produced and launched dramas in 2025.
| Metric | 2025 Baseline | 2032 Projection |
|---|---|---|
| Global market value | US$ 10.63 Billion | US$ 53.9 Billion |
| Forecast CAGR (2026–2032) | — | 26.1% |
| China micro-drama users | 696 Million | — |
| Horizontal micro-dramas launched (Jan–Aug 2025) | 325 titles (+24.52% YoY) | — |
| Estimated independent vertical titles (2025) | ~40,000 | — |
Demand-side fundamentals remain unusually favorable for a content market of this size. Consumption is mobile-native, habit-forming, and monetizable at the episode level.
Restraints are structural rather than cyclical. Midstream production captures only 10–15% of total value-chain revenue, squeezing producer margins and incentivizing vertical integration. Content homogenization, rising user-acquisition costs, and tightening regulatory review of paid short-drama content across major markets raise the cost of failure per title.
The micro-drama value chain is a closed loop from IP to monetization, with markedly asymmetric profit pools.
| Chain Stage | Core Participants | Value Capture |
|---|---|---|
| Upstream — IP copyright | Online literature platforms, comic and game IP holders | Modest; online literature accounts for nearly half of IP supply |
| Midstream — Production | Film and TV companies, MCNs, information-flow firms, IP owners | 10–15% of chain revenue |
| Downstream — Distribution | Short video platforms, mini-programs, long video platforms, independent apps | 80–85% of revenue; ~60% gross margin |
Upstream IP supply is dominated by online literature institutions, whose serialized, fast-paced narrative libraries map almost perfectly onto micro-drama pacing. Midstream producers — many converted from information-flow advertising, traditional film and television, and MCN backgrounds — handle script adaptation, shooting, and post-production. Downstream distributors control traffic acquisition and payment rails, and therefore capture the majority of consumer spend.
A critical structural insight: revenue at the midstream layer flows primarily through guaranteed minimum payments and revenue-sharing arrangements, meaning producer cash flow is heavily contingent on distributor commissioning appetite.
Revenue architecture is diversifying away from pure paid-episode unlock models toward hybrid advertising and commerce structures.
By distribution channel, short video platforms remain the primary reach and monetization surface due to content compatibility and algorithmic amplification. Mini-programs and independent short-drama apps are growing faster off a smaller base, particularly in overseas markets where standalone apps are the primary consumer touchpoint.
Asia Pacific is the production and monetization engine, accounting for an estimated 46% of global market value. North America follows at roughly 24%, driven disproportionately by overseas app revenue rather than domestic production volume — nearly 30% of downloads of leading Chinese micro-drama apps originate in the United States. Europe (16%), Latin America (8%), and Middle East & Africa (6%) represent the next frontier, where payment infrastructure maturity and local-language content supply are the binding constraints.
Internationalization is currently an app-led model. Tier-one overseas platforms have established audience scale, with a second competitive tier building differentiated genre libraries. The strategic imperative for non-Chinese markets is local production, not merely localized dubbing; culturally specific romance, revenge, and rags-to-riches archetypes require re-shooting rather than translation.
The competitive field spans platform owners, traditional film and television studios, online literature IP holders, and digital-native producers. Platform-integrated players hold structural advantage in distribution and data feedback loops, while independent producers compete on genre specialization, production velocity, and cost discipline.
Strategic priorities we observe among market leaders:
Micro-dramas are a digital service export rather than a physical commodity, but trade flows are measurable and strategically meaningful. Content licensing, app distribution, and IP adaptation rights constitute the exportable units, with China functioning as the dominant net exporter of both finished micro-drama formats and production methodology.
The supplier ecosystem upstream of production includes IP licensors, vertical-video production service providers, post-production and localization vendors, and mobile payment and ad-tech intermediaries. Concentration risk is highest in distribution, where a small number of short-video platforms control traffic access across most markets — a single algorithmic policy change can materially reset producer economics.
The largest under-served opportunity lies in local-original production outside Asia Pacific. Demand signals are validated by overseas download concentration, but supply remains dominated by adapted Chinese formats. Local-language original production in Europe, Latin America, and the Middle East represents a defensible position with lower competitive intensity.
Secondary white space exists in production infrastructure: virtual production stages optimized for vertical framing, AI-assisted localization, and rights-management tooling. Finally, the midstream margin compression itself is an investment thesis — producers who secure IP ownership or distribution stakes can migrate from 10–15% value capture toward platform-level economics.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 26.1% from 2020-2034 |
| Segmentation |
|
By Application
| By Geography |
|
The global micro-dramas production market was valued at US$ 10.63 billion in 2025 and is forecast to reach US$ 53.9 billion by 2032, expanding at a 26.1% CAGR over the 2026–2032 period.
Growth is driven by vertical-native mobile consumption, low production barriers enabling rapid title iteration, and four concurrent monetization engines including in-app advertising, pay-per-episode, subscription, and e-commerce. In China alone, 696 million users — nearly 70% of internet users — engaged with micro-dramas as of June 2025.
Distributors and short-video platforms capture approximately 80–85% of industry-chain revenue at gross margins near 60%. Midstream production companies, despite bearing filming and post-production costs, retain only 10–15% of total chain revenue.
Asia Pacific leads with an estimated 46% share of global market value, anchored by China's mature short-video ecosystem and deep online-literature IP reserves. North America follows at roughly 24%, driven by overseas app revenue and strong US audience willingness to pay.
Higher-end vertical micro-drama production costs approximately US$ 120,000 to US$ 150,000 per episode. The broader independent segment operates at far lower budgets, with an estimated 40,000 vertically produced dramas launched in 2025.
As of December 2024, a total of 202 overseas short-drama applications had launched in the international market. Nearly 30% of downloads of leading Chinese micro-drama apps originate from the United States, reflecting strong North American demand.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Head of Content Acquisition | 28% |
| Micro-Drama Production Director | 32% |
| Platform Monetization and Revenue Operations Lead | 25% |
| Chief Strategy Officer | 15% |
| Company Type | Representation (%) |
|---|---|
| IP Copyright Holders and Online Literature Platforms | 22% |
| Vertical-Screen Production Studios and MCN Producers | 38% |
| Short Video and Independent App Distributors | 25% |
| Ad-Tech and Mobile Payment Intermediaries | 15% |
 Related Reports
