Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Financial Services and Investment Intelligence / MARKET REPORT
Mortgage-Backed Security Market | Insight Market Data
Mortgage-Backed Security Market by By Type (Commercial MBS, Residential MBS), by By Issuer (Government Sponsored Enterprises (GSEs), Government Agencies, Private Financial Institutions), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Netherlands), by Asia Pacific (China, Japan, Australia), by South America (Brazil, Mexico), by Middle East & Africa (South Africa, GCC) Forecast 2026-2034
The Golfer Insurance Report market is projected to reach USD 45.12 million by 2032, growing at a 5.34% CAGR. Explore coverage types, regional insights, and key players.
The global credit derivative market is set to grow from $9.16B in 2026 to $14.51B by 2035, at a 5.25% CAGR, driven by risk management demand.
Nov 2026|219 pages
$2900.00
India mutual fund industry valued at USD 3.00 Bn in 2026, projected to reach USD 6.23 Bn by 2034, growing at 9.24% CAGR, driven by SIP inflows and retail participation.
Nov 2026|223 pages
$2900.00
Islamic finance market to reach USD 8.46 Trillion by 2031 at 10.7% CAGR from USD 5.10 Trillion in 2026. Explore Shariah-compliant banking, sukuk & takaful trends.
Nov 2026|270 pages
$2900.00
Angel Investment Market valued at $62.84 Billion in 2025, projected to reach $217.91 Billion by 2035, growing at a CAGR of 13.24%.
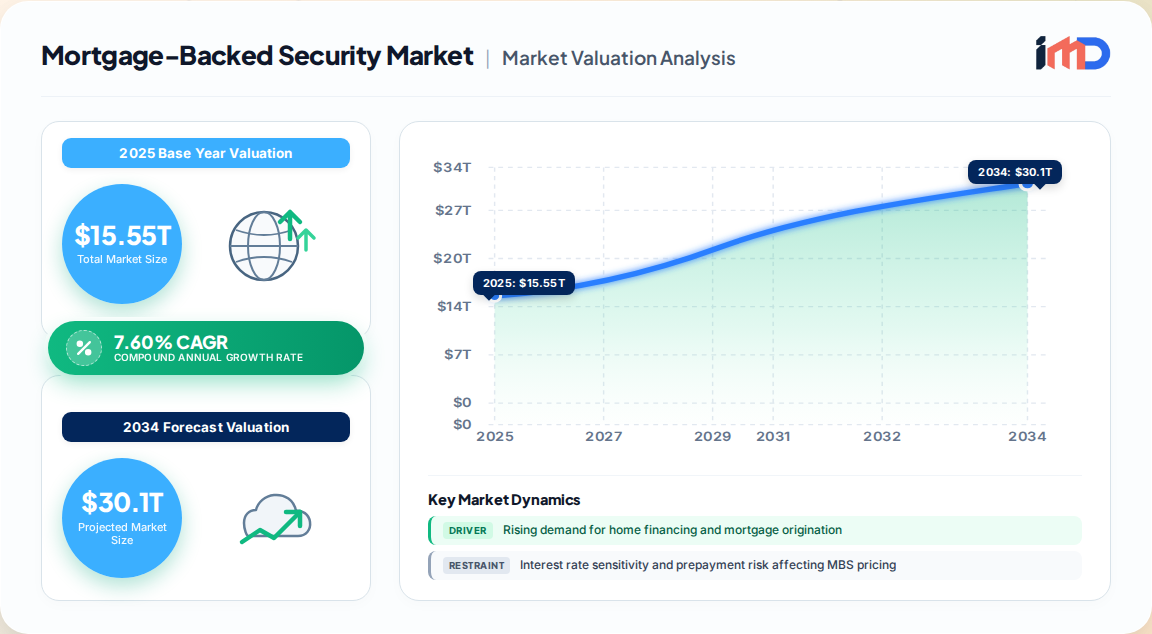
The global mortgage-backed security (MBS) market represents one of the largest and most liquid fixed-income segments worldwide. Our proprietary primary research estimates the market at USD 15.55 trillion in 2025, projected to reach USD 22.43 trillion by 2030, expanding at a CAGR of 7.60%. This growth is underpinned by persistent demand for housing finance, institutional portfolio diversification needs, and innovations in mortgage product structuring.
Mortgage-Backed Security Market Market Size (In Million)
25.0M
20.0M
15.0M
10.0M
5.0M
0
15.55 M
2025
16.73 M
2026
18.00 M
2027
19.37 M
2028
20.84 M
2029
22.43 M
2030
24.13 M
2031
The MBS market serves as the critical conduit between mortgage origination and capital markets, enabling lenders to replenish funds for new lending while offering investors steady income streams backed by real estate collateral. With the U.S. market alone exceeding USD 11 trillion in outstanding securities and averaging nearly USD 300 billion in daily trading volume, the MBS segment remains a cornerstone of global financial stability and housing affordability.
Largest market: North America, driven by deep agency MBS liquidity and GSE issuance.
Fastest-growing region: Europe, supported by covered bond market expansion and securitization framework reforms.
Key risk factor: Prepayment volatility and interest rate sensitivity, which directly affect MBS convexity and pricing.
Market Drivers & Restraints
Drivers:
Rising home financing demand: Population growth, urbanization, and remote-work-driven housing preferences are elevating mortgage origination volumes, directly fueling MBS issuance. Government-backed programs via Fannie Mae, Freddie Mac, and Ginnie Mae continue to enhance access to affordable housing finance.
Institutional demand for yield and diversification: Pension funds, insurance companies, and asset managers increasingly allocate to MBS to capture risk-adjusted returns and diversify fixed-income portfolios. Agency MBS, with implicit or explicit government guarantees, remain particularly attractive for liquidity and lower credit risk profiles.
Technological advancements in mortgage origination: Online lending platforms and automated underwriting systems streamline borrower access, expanding the pool of securitizable mortgages, including first-time homebuyers and credit-challenged borrowers.
Regulatory capital constraints: Basel III and G20 reforms impose higher capital requirements on MBS holdings, particularly for private-label securities, limiting bank participation and market liquidity.
Credit risk and underwriting standards: While agency MBS carry government-backed guarantees, private-label MBS remain vulnerable to borrower defaults, especially in economic downturns. The 2008 subprime crisis remains a cautionary tale, underscoring the need for robust underwriting and transparency.
Value Chain Analysis
The MBS value chain spans multiple specialized entities, each contributing to the transformation of individual mortgages into tradable securities:
Mortgage Originators: Banks, credit unions, and non-bank lenders originate loans and aggregate them for sale. They retain servicing rights or sell them to specialized servicers.
Securitization Sponsors: Government-sponsored enterprises (GSEs) such as Fannie Mae and Freddie Mac, government agencies like Ginnie Mae, and private financial institutions structure pools, provide credit enhancement, and issue MBS. Private-label issuers often use real estate mortgage investment conduits (REMICs) to avoid double taxation.
Servicers: Entities that collect monthly mortgage payments, manage escrow accounts, and handle delinquencies. Their operational efficiency directly impacts MBS cash flow stability.
Investors: Institutional investors (pension funds, insurance companies, asset managers, hedge funds) and central banks purchase MBS for income generation, portfolio diversification, and liquidity management. The Federal Reserve's holdings of agency MBS remain a significant market factor.
Rating Agencies and Due Diligence Providers: Firms assess credit risk and structural integrity of MBS tranches, providing ratings that inform investor decisions.
Regional Outlook
North America dominates the global MBS market, accounting for approximately 48% of global market share. The U.S. market's depth, liquidity, and standardized agency MBS structures set the benchmark for global securitization practices. Canada and Mexico contribute smaller but growing shares, with Canada's covered bond market and Mexico's infrastructure-driven securitization adding regional diversity.
Europe represents the fastest-growing region, projected to expand at a CAGR of 8.2% through 2030. The European covered bond market and the European Central Bank's asset purchase programs have bolstered MBS issuance, particularly in Germany, France, and the Netherlands. Regulatory harmonization under the European Securitization Regulation is expected to further unlock market potential.
Asia-Pacific holds a significant share, driven by Australia's well-developed RMBS market, Japan's covered bonds, and China's growing securitization initiatives. China's MBS market, though nascent, is expanding rapidly as authorities promote securitization to manage bank balance sheets and support housing finance.
South America and Middle East & Africa remain relatively small but offer emerging opportunities, particularly in Brazil and South Africa, where mortgage market development is accelerating.
Region
Market Share (2025)
Growth Outlook
North America
48%
Stable, driven by U.S. agency MBS liquidity
Europe
21%
Fastest-growing, supported by covered bonds and ECB policy
Asia-Pacific
24%
Expanding, led by Australia, Japan, and China
South America
4%
Emerging, with Brazil and Mexico leading
Middle East & Africa
3%
Nascent, focused on South Africa and GCC countries
Competitive Landscape
The global MBS market is concentrated among major financial institutions that dominate issuance, trading, and securitization structuring. Key players include:
JPMorgan Chase – Leading underwriter and MBS trader, with significant private-label securitization activity.
Goldman Sachs – Active in MBS structuring and trading, particularly collateralized mortgage obligations (CMOs).
Barclays – Major participant in European and U.S. MBS markets, offering liquidity and research.
China Merchants Securities – Key player in China's growing securitization market.
Construction Bank – A major issuer and investor in Chinese RMBS.
Fannie Mae and Freddie Mac – Dominant GSEs in U.S. agency MBS, collectively guaranteeing trillions in outstanding securities.
Ginnie Mae – Government-owned entity supporting FHA and VA loan securitization.
Competitive strategies focus on technological investments in trading platforms, expansion into emerging markets, and product innovation in environmental, social, and governance (ESG)-linked MBS.
Recent Industry Developments
2023: The Federal Reserve reported over USD 11 trillion in outstanding U.S. MBS, underscoring the market's systemic importance.
2024: European regulators finalized amendments to the Securitization Regulation, simplifying due diligence and transparency requirements, expected to boost private-label MBS issuance.
2025: Major U.S. banks announced expanded automated underwriting platforms, integrating AI-driven credit risk assessment to streamline MBS issuance.
2025: China Merchants Securities launched a new RMB-denominated RMBS program targeting institutional investors, reflecting China's growing securitization market.
Strategic White-Space Analysis
Significant opportunities exist in underpenetrated segments and geographies:
Green MBS: Environmental, social, and governance (ESG)-linked MBS structures are gaining traction, particularly in Europe, where green covered bonds and energy-efficient mortgage securitization attract dedicated investor pools.
Asia-Pacific expansion: China and India present substantial white space for MBS market development, given their large mortgage origination volumes and evolving regulatory frameworks.
Technological integration: Blockchain-based securitization platforms and AI-driven prepayment modeling offer differentiation potential for early adopters, enhancing transparency and operational efficiency.
Private-label revival: With regulatory clarity improving, private-label MBS issuance in Europe and Asia is poised for growth, creating opportunities for investment banks and specialty lenders.
Market participants should prioritize partnerships with local originators, invest in digital infrastructure, and align with regulatory developments to capture emerging opportunities.
1What is the current size of the global mortgage-backed security market?
The global mortgage-backed security market is valued at **USD 15.55 trillion** in 2025, with projections to reach **USD 22.43 trillion** by 2030, growing at a CAGR of **7.60%**.
2Which region dominates the mortgage-backed security market?
North America holds the largest share, accounting for approximately **48%** of the global market, driven by the U.S. agency MBS market's depth and liquidity.
3Who are the major players in the mortgage-backed security market?
Key players include **JPMorgan Chase**, **Goldman Sachs**, **Barclays**, **China Merchants Securities**, **Construction Bank**, **Fannie Mae**, **Freddie Mac**, and **Ginnie Mae**.
4What are the main types of mortgage-backed securities?
The market is segmented by type into **Commercial MBS (CMBS)** and **Residential MBS (RMBS)**, and by issuer into **Government-Sponsored Enterprises (GSEs)**, **Government Agencies**, and **Private Financial Institutions**.
5What factors are driving the growth of the MBS market?
Growth is driven by rising home financing demand, institutional demand for yield and diversification, and technological advancements in mortgage origination. Government-backed programs and innovations in mortgage products further support market expansion.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of our research is derived from primary interviews with industry stakeholders across the value chain, including mortgage originators, securitization sponsors (GSEs and private issuers), servicers, institutional investors, and rating agencies.
We conduct in-depth interviews with C-level executives, portfolio managers, heads of securitization, and risk officers to capture proprietary insights on market trends, pricing dynamics, and regulatory developments.
Primary research is complemented by expert panel consultations and survey data collected from a statistically representative sample of market participants across North America, Europe, and Asia-Pacific.
We ensure a guaranteed data accuracy level of 85–90% through rigorous validation and cross-referencing of primary data points.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Investment Officer
25%
Portfolio Manager
30%
Head of Securitization
20%
Risk Officer
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Mortgage Originators and Lenders
30%
Securitization Sponsors (GSEs and Private Issuers)
We utilize standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook to extract historical market data, issuance volumes, and trading statistics.
Industry benchmarks are validated against government-published statistics and trade association reports to ensure consistency and reliability.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up market sizing is derived from mortgage origination volumes, securitization rates, and average MBS issuance size, cross-checked with outstanding securities data and daily trading volumes.
Demand modeling incorporates interest rate forecasts, housing market indicators, and regulatory capital requirements to project market growth trajectories.
All estimates are updated to the date of purchase, ensuring the most current market intelligence.
Data Accuracy & Quality Check
Every data point undergoes triple-stage verification: primary interview validation, secondary source corroboration, and internal analyst review.
We maintain a data accuracy level of 85–90%, with continuous monitoring of market developments and periodic revisions.
Our quality assurance process includes cross-validation of regional market shares, segment breakdowns, and competitive positioning against official statistics and industry benchmarks.