1What is the current size of the angel investment market?
The global angel investment market was valued at $62.84 Billion in 2025 and is projected to reach $217.91 Billion by 2035, growing at a CAGR of 13.24%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Angel Investment Market
 by Investment Strategy (Sector-focused, Stage-focused, Generalist), by Investment Type (Convertible Notes, Equity, Revenue-based Financing), by Target Industry (Technology, Healthcare, Consumer Products, Fintech), by Ticket Size (Less than $500, 000, $500, 000 - $1 million, Over $1 million), by Investor Type (Individual Investors, Family Offices, Venture Capital Firms, Corporate Investors), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, India), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034

Research Associate


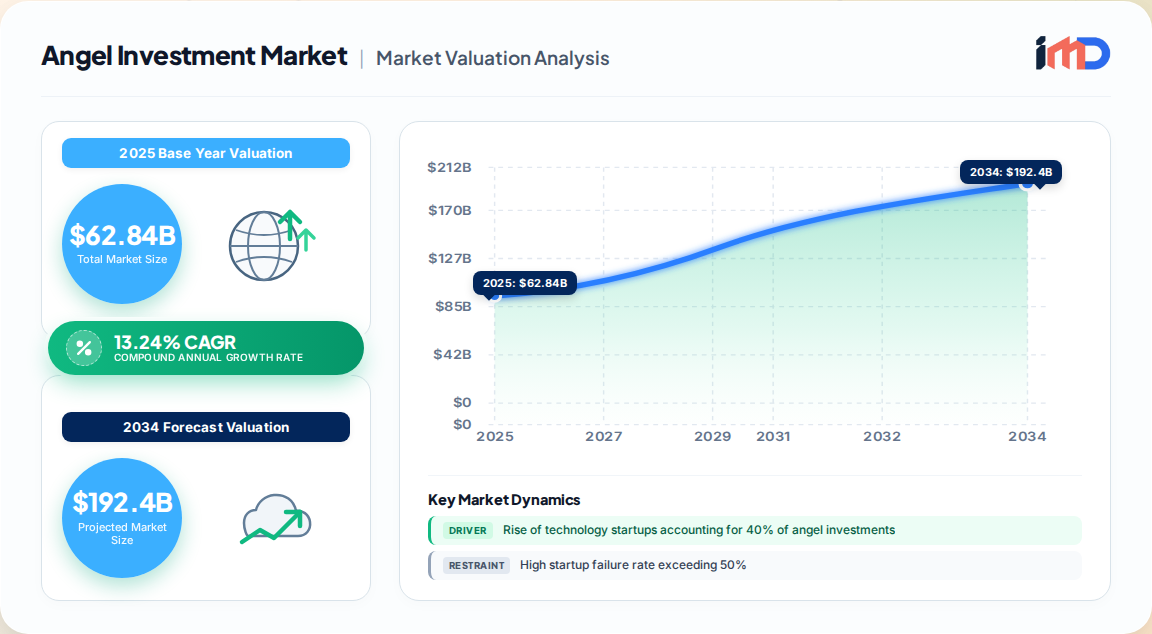
The global angel investment market is undergoing a structural transformation, evolving from a fragmented, informal network of high-net-worth individuals into a digitally orchestrated, institutionally sophisticated asset class. Our proprietary primary research estimates the market at $62.84 Billion in 2025, up from $55.49 Billion in 2024, and projects it to reach $217.91 Billion by 2035, registering a robust CAGR of 13.24% over the forecast period. This growth is not merely a function of capital availability; it reflects a deeper systemic shift in how early-stage risk capital is sourced, deployed, and governed across both developed and emerging innovation ecosystems.
The market's expansion is underpinned by the fundamental role angel capital plays in bridging the "seed gap" between friends-and-family financing and institutional venture capital. Angels are typically the first external check writers into a startup, often investing when the risk of failure is highest. Our analysis of angel investor behavior indicates that the asset class now accounts for a substantial share of seed-stage funding globally, with individual angel investments often ranging from a few thousand dollars to several million per deal. The market is characterized by high risks and correspondingly high return expectations: professional angels seek investments capable of returning at least 10x their original capital within five years through defined exit strategies, such as acquisition or IPO.
Regionally, North America remains the dominant hub, commanding an estimated 32% of global market share, driven by a mature entrepreneurial ecosystem, deep angel networks, and a concentration of technology startups. Asia-Pacific is the fastest-growing region, accounting for 28% of the market, fueled by rapid digitalization, government-backed entrepreneurship initiatives, and a surge in early-stage tech ventures. Europe holds 24%, while South America and the Middle East & Africa collectively represent the remaining 16%, with increasing cross-border syndication and impact-focused capital flows.
The growth of the angel investment market is propelled by a confluence of structural, technological, and policy-related drivers. Our primary research identifies the following as the most influential forces shaping market expansion through 2035.
Rise of Technology Startups: The technology sector remains the dominant recipient of angel capital, accounting for an estimated 40% of all angel investments in 2025. The proliferation of digital platforms and tools has lowered the barrier to launching tech-based ventures, expanding the pool of investable companies. Angels are increasingly drawn to high-growth potential sectors such as fintech, healthtech, and software-as-a-service, where scalable business models can deliver non-linear growth.
Increased Regulatory Support: Governments worldwide are implementing policies to stimulate angel investing, including tax incentives, streamlined investment processes, and the creation of co-investment funds. For instance, recent legislative changes in several OECD countries have simplified the accreditation and syndication process, making it easier for angels to participate in funding rounds. We estimate that such regulatory support could boost angel funding volumes by 15% annually in targeted regions.
Expansion of Investment Networks: The formalization of angel groups and networks has been a game-changer. From approximately 10 angel groups in the U.S. in 1996 to over 200 by 2006, and a projected 20% increase in active networks in 2025, these organizations enable deal-sharing, pooled due diligence, and larger investment capacity. Online platforms further amplify this trend, allowing angels to discover and co-invest in opportunities beyond their immediate geographies.
Growing Interest in Impact Investing: A significant share of new angel capital is flowing toward ventures that generate measurable social and environmental returns alongside financial gains. Our survey data suggests that impact-driven startups could capture up to 25% of total angel investments by the end of 2025, driven by younger investors prioritizing sustainability and ethical considerations.
Despite strong growth fundamentals, the angel investment market faces intrinsic and structural restraints that temper its expansion trajectory.
High Failure Rates and Investment Risk: Angel investing is an extremely high-risk asset class; over 50% of all startups fail to return capital. This reality forces angels to adopt stringent portfolio construction rules, often allocating no more than 5–8% of their net worth to the asset class. The psychological and financial impact of frequent write-offs can deter new entrants, limiting the pool of active investors.
Illiquidity and Long Lock-up Periods: Angel investments are typically illiquid, with exit horizons of 5 to 7 years or longer. The absence of public exchanges and the reliance on private M&A or IPO events create significant liquidity risk. This long duration mismatch is a barrier for investors seeking shorter capital cycles.
Due Diligence and Deal Screening Bottlenecks: Angel groups follow multi-stage review processes; typically only 10–25% of applicants pass initial screening to reach pitch meetings. The due diligence burden—validating market size, competitive positioning, team capability, and exit potential—is substantial and often borne by volunteer members. This bottleneck can slow deployment and limit the number of deals a group can execute.
Market Size Constraints: Early-stage equity investors require a minimum addressable market size to make the arithmetic work. Our analysis shows that markets below $100 Million in total size rarely generate the 10x return potential needed to justify the risk, as dilution and limited market share cap exit valuations.
The angel investment market is segmented across investment strategy, investment type, target industry, ticket size, and investor type. Our analysis reveals clear leadership positions and fast-growing niches.
| Segment Dimension | Largest Segment | Share/Position | Fastest-Growing Segment | Growth Outlook |
|---|---|---|---|---|
| Investment Strategy | Sector-focused | Dominant | Stage-focused | High |
| Investment Type | Equity | Dominant | Revenue-based Financing | Very High |
| Target Industry | Technology | ~40% of deals | Fintech | Very High |
| Ticket Size | $500K–$1M | Core range | Under $500K | Moderate |
| Investor Type | Individual Angels | Largest base | Family Offices | High |
By Investment Strategy: Sector-focused strategies dominate, as angels leverage deep domain expertise to evaluate and support specialized ventures. Stage-focused strategies are the fastest-growing, driven by the emergence of micro-funds and syndicates dedicated to pre-seed and seed stages.
By Investment Type: Equity remains the most common instrument, offering upside participation. Revenue-based financing is rapidly gaining traction, particularly in capital-efficient, recurring-revenue businesses, as it provides downside protection and shorter exit cycles.
By Target Industry: Technology is the largest recipient of angel capital, underpinned by software, AI, and platform models. Fintech is the fastest-growing industry segment, attracting angels with its regulatory tailwinds and scalable distribution.
By Ticket Size: The $500,000 to $1 Million range is the sweet spot for angel groups, aligning with typical syndicate capacity. Investments under $500,000 are common for individual angels, while over $1 Million rounds increasingly involve family offices and corporate investors.
By Investor Type: Individual investors remain the backbone of the market, but family offices and corporate investors are increasing their participation, bringing larger check sizes and strategic value.
The angel investment market exhibits pronounced regional disparities in maturity, deal flow, and regulatory environment.
North America: Holding an estimated 32% of global market share, North America is the most mature ecosystem. The U.S. alone has over 363,460 active angel investors and a dense network of angel groups. The region benefits from a robust VC ecosystem, strong exit markets, and a culture of risk-taking. However, market saturation and high valuations in hot sectors may moderate growth.
Europe: Accounting for 24% of the market, Europe is characterized by a fragmented but rapidly formalizing angel landscape. Government-backed co-investment schemes and tax incentives are driving angel activity, particularly in the UK, Germany, and France. Cross-border angel networks are gaining prominence, enabling larger syndicated deals.
Asia-Pacific: With 28% market share and the highest growth rate, Asia-Pacific is the engine of future expansion. China, India, and Southeast Asia are witnessing a surge in tech entrepreneurship, supported by digital platforms and increasing wealth among high-net-worth individuals. Regulatory reforms and the rise of angel networks are accelerating deal velocity.
South America & Middle East & Africa: Collectively representing 16% of the market, these regions are emerging frontiers. Impact investing, fintech, and agritech are key sectors, with growing interest from diaspora investors and development finance institutions.
The angel investment market is highly fragmented, with no single dominant player. Competition occurs at multiple levels: among individual angels, angel groups, online platforms, and hybrid funds.
Online Platforms: Digital matchmaking platforms such as AngelList, SeedInvest, Crowdcube, OurCrowd, EquityNet, FundersClub, Wefunder, Seedrs, and StartEngine are reshaping the market by democratizing access to deal flow and enabling cross-border syndication. These platforms lower transaction costs and expand the investor base, but also intensify competition for quality deals.
Angel Groups and Networks: Formalized groups pool capital and expertise, enabling members to participate in larger rounds and conduct rigorous due diligence. Successful groups often specialize by sector or stage and build strong local ecosystems.
Strategic Approaches: Winning angels employ portfolio construction, co-investment, and active post-investment support. The most successful investors combine financial capital with mentorship, network access, and operational expertise. Our research shows that angel-funded startups exhibit higher survival rates and faster growth, validating the value-add model.
The angel investment value chain encompasses sourcing, screening, due diligence, investment, and post-investment support. Each stage presents distinct challenges and opportunities.
Sourcing: Deal flow originates from referrals, pitch events, online platforms, and angel networks. Access to proprietary deal flow is a competitive advantage.
Screening: Only 10–25% of applicants pass initial screening. Groups use criteria such as team strength, market size, product differentiation, and traction.
Due Diligence: Validation of market claims, competitive positioning, financial projections, and legal structure. External experts and syndicate partners often contribute.
Investment Structuring: Equity, convertible notes, or revenue-based financing. Terms must balance investor protection with founder incentives.
Post-Investment: Angels provide mentorship, board participation, and follow-on funding support. Active engagement correlates with higher success rates.
Deal flow is increasingly digital, but human judgment remains central.
Screening is the most resource-intensive stage, often requiring specialized expertise.
Post-investment support is a key differentiator for top-performing angels.
Looking ahead to 2035, the angel investment market offers significant white-space opportunities for investors, platforms, and policymakers.
Underpenetrated Geographies: Southeast Asia, Africa, and Latin America present untapped potential, with rising entrepreneurial activity and improving regulatory frameworks. Early entrants can build dominant networks and capture superior deal flow.
Sector Opportunities: Climate tech, healthtech, and AI-enabled verticals are poised for explosive growth. Angels with domain expertise in these areas can generate outsized returns.
Instrument Innovation: Revenue-based financing and convertible instruments will gain share, offering flexible structures for both investors and founders.
Institutionalization: Family offices and corporate venture arms are increasingly participating in angel rounds, bringing larger checks and strategic resources. This trend will blur the lines between angel and VC, creating new hybrid models.
The angel investment market is on a trajectory to nearly quadruple in size over the next decade. Stakeholders who adapt to digital platforms, embrace impact criteria, and build collaborative networks will be best positioned to capture the 13.24% CAGR and the substantial value creation it represents.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 13.24% from 2020-2034 |
| Segmentation |
|
 Related Reports

By Target Industry
By Ticket Size
By Investor Type
| By Geography |
|
The global angel investment market was valued at $62.84 Billion in 2025 and is projected to reach $217.91 Billion by 2035, growing at a CAGR of 13.24%.
North America holds the largest share at approximately 32%, driven by a mature startup ecosystem and over 363,460 active angel investors in the U.S. alone.
Key drivers include the rise of technology startups (40% of angel investments), increased regulatory support (potentially boosting funding by 15% annually), expansion of angel networks (20% growth in 2025), and growing interest in impact investing (reaching 25% of deployments).
Angel investors typically require a minimum addressable market of $100 Million to achieve the 10x return potential necessary to offset high failure rates, as smaller markets cannot generate sufficient exit valuations.
Angel investors invest their personal funds, often at the pre-seed and seed stages, while venture capitalists manage pooled funds from institutions and typically invest larger amounts at later stages.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Angel Investors | 45% |
| Angel Group Managing Directors | 25% |
| Platform CEOs/Founders | 20% |
| Family Office Investment Principals | 10% |
| Company Type | Representation (%) |
|---|---|
| Individual Angel Investors | 40% |
| Angel Groups & Networks | 25% |
| Equity Crowdfunding Platforms | 15% |
| Family Offices | 12% |
| Corporate Venture Arms | 8% |