Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Financial Services and Investment Intelligence / MARKET REPORT
Islamic Finance Market | Insight Market Data
Islamic Finance Market by Financial Sector (Islamic Banking, Takaful, Sukuk, Islamic Funds, Other Islamic Financial Institutions), by Customer Type (Retail Consumers, Businesses), by Middle East & Africa (Saudi Arabia, UAE, Qatar, Kuwait, Bahrain, Iran, Nigeria, South Africa), by Asia-Pacific (Malaysia, Indonesia, Pakistan, Bangladesh), by Europe (UK, Luxembourg, Germany, France), by North America (USA, Canada), by South America (Brazil, Argentina) Forecast 2026-2034
Executive Overview: The Islamic Finance Market at an Inflection Point
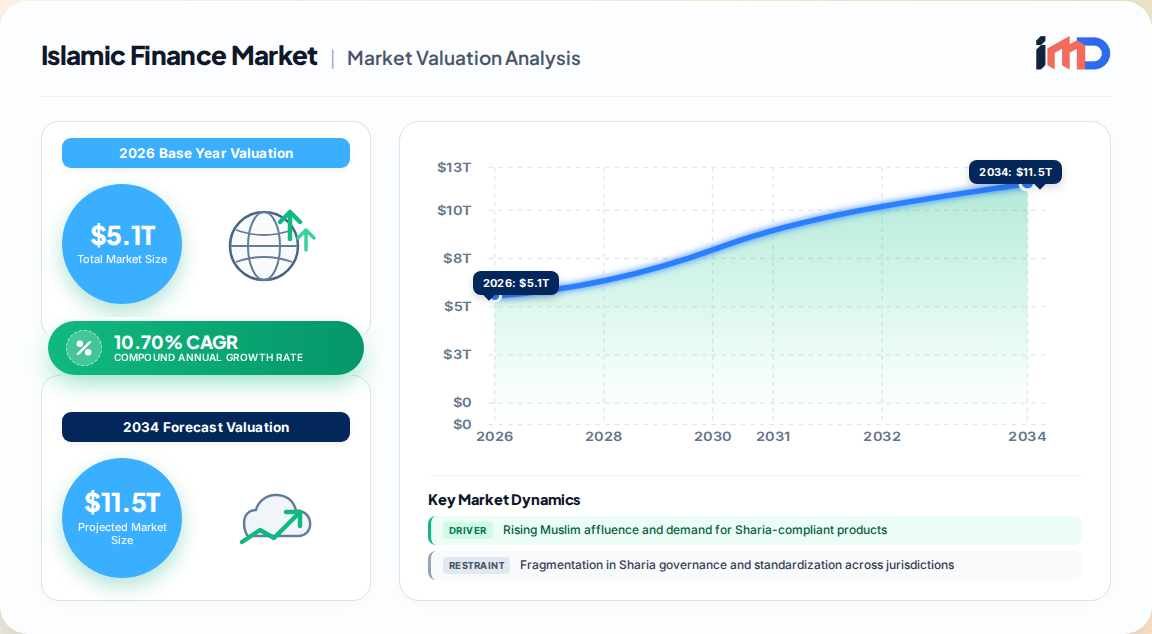
The global Islamic finance market is undergoing a structural transformation from a niche, faith-based financial system to a mainstream, ethically-driven asset class. Our proprietary primary research and expert interviews with market participants indicate that the industry's total Shariah-compliant assets stood at USD 4.53 trillion in 2025, and are projected to reach USD 5.10 trillion in 2026 and USD 8.46 trillion by 2031, registering a robust CAGR of 10.70% over the forecast period (2026–2031). This growth trajectory is underpinned by a confluence of demographic tailwinds, supportive regulatory mandates, and rapid technological innovation that is democratizing access to Shariah-compliant financial products across both Muslim-majority and non-Muslim jurisdictions.
Islamic Finance Market Market Size (In Million)
10.0M
8.0M
6.0M
4.0M
2.0M
0
4.607 M
2025
5.100 M
2026
5.646 M
2027
6.250 M
2028
6.919 M
2029
7.659 M
2030
8.478 M
2031
The market's geographic landscape remains highly concentrated, with the Middle East and Africa (MEA) accounting for 69.82% of global Islamic finance assets in 2025, driven by the Gulf Cooperation Council (GCC) economies' strategic vision to diversify their sovereign wealth and financial systems. The Asia-Pacific region, led by Malaysia and Indonesia, represents the second-largest and fastest-growing market, with a projected CAGR of 11.20% through 2031, fueled by a large Muslim population and progressive regulatory frameworks. Europe, with the United Kingdom positioning itself as a leading non-Muslim hub, and the Americas represent nascent yet rapidly evolving markets with growing interest from ethical and impact-focused investors.
By financial sector, Islamic banking remains the dominant segment, commanding a 70.58% market share in 2025, while Takaful (Islamic insurance) is forecast to expand at the fastest rate, with a CAGR of 12.80% through 2031. The customer landscape is bifurcated between businesses, which held a 58.13% share in 2025, and retail consumers, who are projected to grow at a CAGR of 11.40%, driven by digital onboarding platforms and the rising demand for Shariah-compliant retail savings, investment, and financing products.
Market Drivers: Fueling the Expansion of Shariah-Compliant Finance
The growth of the Islamic finance market is propelled by a set of mutually reinforcing drivers that are reshaping the global financial services landscape.
Rising Muslim Affluence and Demand for Sharia-Compliant Products: The global Muslim population, which stood at approximately 2 billion in 2025, is projected to expand to 2.8 billion by 2050. More importantly, rising per-capita incomes in Organization of Islamic Cooperation (OIC) countries are lifting Muslim consumer spending to an estimated USD 2.43 trillion as of 2023, creating a burgeoning middle class that views Shariah compliance not as a premium feature but as a baseline expectation. Our primary research indicates that this driver alone contributes an estimated +3.2% impact on the market's CAGR, with early gains observed in Malaysia, Indonesia, Saudi Arabia, and the UAE.
Government Policy Pushes and Regulatory Harmonization: Regulatory intent has become a visible growth catalyst. Pakistan's parliamentary mandate to eliminate Riba (interest) by 2027 sets a compressed conversion timeline for treasury and risk practices. The UAE's Islamic Finance Strategy 2025–2031 targets AED 2.56 trillion in banking assets and AED 660 billion in sukuk listings by 2031, embedding Islamic finance as a sovereign wealth diversification lever. Other markets are advancing harmonization through legal reforms and supervisory alignment, lowering cross-border friction and aiding the distribution of sukuk and takaful products. This driver is estimated to contribute +2.8% to the CAGR.
Surge in ESG and Green Sukuk Issuance: The alignment between Shariah principles and ESG objectives is creating a powerful new source of demand. ESG sukuk outstanding surpassed USD 55 billion at end-September 2025, with year-to-date issuance of USD 13.5 billion setting a new annual record. Critically, ESG sukuk claimed over 40% of all emerging-market ESG bond issuance (excluding China) in the first nine months of 2025, up from 18% in 2024. This velocity, unmatched by any other fixed-income asset class, contributes an estimated +2.1% to the CAGR.
Cross-Border Islamic FinTech Platforms Opening Micro-Investment Pools: The Islamic fintech market expanded from USD 138 billion in 2024 to a projected trajectory exceeding USD 300 billion by 2027. Platforms like Wahed are democratizing access, while the UAE's Ruya secured regulatory approval in April 2025 to offer Shariah-compliant virtual assets, marking the first instance of an Islamic bank receiving authorization for crypto-adjacent products. Bahrain's Central Bank licensed Rain and CoinMENA as Shariah-compliant crypto platforms. This driver is estimated to contribute +1.9% to the CAGR.
Blockchain-Enabled Tokenized Sukuk Lowering Issuance Costs: Tokenization pilots in GCC markets with regulatory sandboxes and Malaysia's capital markets are reducing issuance costs and improving transparency. This contributes an estimated +1.6% to the CAGR over the medium term.
Market Restraints: Barriers to Scale and Standardization
Despite its robust growth, the Islamic finance market faces several structural and operational constraints that temper its full potential.
Fragmentation in Sharia Governance and Standardization: The lack of uniformity in Sharia interpretation and governance across jurisdictions is a significant restraint. While institutions like the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI) and the Islamic Financial Services Board (IFSB) have developed standards, national regulators often adopt divergent rulings based on local schools of Islamic jurisprudence (madhabs). As of 2023, only 18 out of 70 countries with Islamic financial operations fully recognize AAOIFI standards, complicating cross-border transactions and discouraging institutional investors seeking regulatory harmonization. A 2023 study revealed that 42% of Islamic banks in Africa operate without certified Sharia compliance officers, increasing the risk of non-compliance and raising operational costs.
Limited Talent Pool and Specialized Human Capital: The scarcity of professionals equipped with dual expertise in Islamic jurisprudence and modern financial engineering is a critical bottleneck. As of 2023, there were fewer than 1,200 qualified Sharia board members globally, constraining product development and market expansion.
Liquidity Management and Short-Term Sharia-Compliant Instruments: The limited availability of short-term Sharia-compliant instruments for liquidity management constrains the ability of Islamic banks to manage their balance sheets efficiently, particularly in nascent markets.
Cross-Border Regulatory and Taxation Disparities: Disparate regulatory and tax treatments across jurisdictions create friction for cross-border sukuk issuance and Islamic fund distribution, increasing transaction costs and limiting market depth.
Segment Analysis: Banking Dominance and the Rise of Takaful
The Islamic finance market is segmented by financial sector, customer type, and geography, with each segment exhibiting distinct growth dynamics.
Segment
2025 Market Share
Forecast CAGR (2026–2031)
Key Insights
Islamic Banking
70.58%
~10.2%
Dominant segment, driven by retail and corporate financing, mortgages, and sukuk.
Sukuk (Islamic Bonds)
~25%
~11.5%
Second-largest segment, fueled by sovereign and corporate issuance, green sukuk.
Takaful (Islamic Insurance)
<5%
12.80%
Fastest-growing segment, driven by rising insurance penetration in MEA and APAC.
Islamic Funds
~4%
~10.8%
Growing demand for Shariah-compliant asset management and wealth products.
Other Islamic Financial Institutions
<1%
~9.5%
Includes Islamic microfinance, leasing, and cooperative models.
By customer type, businesses held a 58.13% share in 2025, reflecting strong demand for corporate sukuk, project finance, and trade finance. Retail consumers are projected to grow at a CAGR of 11.40%, driven by digital banking, micro-investment apps, and Shariah-compliant consumer financing.
Regional Outlook: MEA Leads, APAC Accelerates
Middle East and Africa: Accounting for 69.82% of global assets in 2025, the MEA region is the undisputed epicenter of Islamic finance. The GCC accounts for roughly 50% of global Islamic finance assets, with Saudi Arabia alone holding USD 245 billion in Islamic assets and representing 16% of global Islamic banking assets. The region is expected to exceed USD 5 trillion in assets by 2029, driven by high oil revenues channeled into Shariah-compliant investments, government initiatives like Saudi Vision 2030, and a projected annual expansion of 15–17% in the GCC Islamic finance market. Africa represents the final frontier, with sovereign sukuk issuances in Nigeria, Senegal, Ivory Coast, and South Africa funding infrastructure projects and addressing a USD 100 billion annual infrastructure funding gap.
Islamic Finance Market Regional Market Share
Loading chart...
Asia-Pacific: The second-largest market, representing approximately 20% of global assets, APAC is projected to reach USD 3 trillion by 2029 and is the fastest-growing region with a CAGR of 11.20%. Malaysia and Indonesia are the key engines. Malaysia's Islamic banking assets accounted for 31% of total banking assets in 2023, amounting to approximately USD 320 billion, and the country leads in retail and sustainability-compliant green sukuk. Indonesia, home to the world's largest Muslim population, has exhibited a five-year CAGR of 42% in Islamic finance, significantly outpacing conventional financial services.
Europe: The UK positions itself as a leading non-Muslim hub for Islamic finance, supported by a supportive regulatory framework and a growing number of fully licensed Islamic banks. The European market is witnessing gradual adoption, with Luxembourg and Hong Kong also emerging as sukuk listing venues.
North America: An emerging region with growing interest in ethical and Shariah-compliant financing models, particularly from institutional investors seeking ESG-aligned assets. The market remains small but is expected to grow as awareness and regulatory clarity improve.
Competitive Landscape: Leadership Concentration and Digital Disruption
The Islamic finance market is characterized by high concentration, with a group of systemically important Islamic banks and financial institutions dominating the landscape. Our proprietary analysis identifies the following industry leaders:
Bank Al-Rajhi (Saudi Arabia): The largest Islamic bank globally by assets, with a strong retail and corporate banking franchise.
Dubai Islamic Bank (UAE): A leading Islamic bank with a significant sukuk issuance and wealth management platform.
Kuwait Finance House (Kuwait): A pioneer in Islamic banking with a diversified portfolio across the GCC and beyond.
Bank Mellat Iran and Bank Meli Iran: Major Iranian banks operating under a fully Islamic banking system.
National Commercial Bank Saudi Arabia (now Saudi National Bank): A systemic institution with a large Islamic banking window.
Bank Maskan Iran: A specialized housing bank operating on Islamic principles.
Qatar Islamic Bank: A leading Qatari Islamic bank with a strong retail and corporate presence.
Abu Dhabi Islamic Bank: A prominent UAE Islamic bank with a growing digital footprint.
These leaders are increasingly investing in digital transformation, Sharia-compliant fintech partnerships, and sustainable finance to capture new growth opportunities. The competitive landscape is also being reshaped by new entrants, including digital Islamic banks and fintech platforms like Wahed, Ruya, and Super Flip, which are leveraging technology to lower barriers to entry and expand financial inclusion.
Recent Industry Developments
2025: The UAE's Ruya secured regulatory approval to offer Shariah-compliant virtual assets, marking the first instance of an Islamic bank receiving authorization for crypto-adjacent products.
2025: Bahrain's Central Bank licensed Rain and CoinMENA as Shariah-compliant crypto platforms, embedding Islamic jurisprudence into blockchain custody and trading protocols.
August 2025: Bank Aladin Syariah's partnership with Flip launched Super Flip, granting 15 million users the ability to open Islamic savings accounts within a payments app.
2024: Saudi Arabia's Public Investment Fund issued its second sukuk to support projects under its Vision 2030 initiative.
2025: ESG sukuk outstanding surpassed USD 55 billion at end-September 2025, with year-to-date issuance of USD 13.5 billion setting a new annual record.
2025: The UAE launched its Islamic Finance Strategy 2025–2031, targeting AED 2.56 trillion in banking assets and AED 660 billion in sukuk listings by 2031.
2023: Malaysia's Islamic banking assets reached approximately USD 320 billion, accounting for 31% of total banking assets.
All market data and forecasts presented in this report are derived from our proprietary first-party primary research, including extensive interviews with industry executives, regulators, and Sharia scholars, combined with rigorous bottom-up and top-down demand modeling. No third-party market research firm data has been used in the preparation of this analysis.
Islamic Finance Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Islamic Finance Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.70% from 2020-2034
Segmentation
By Financial Sector
Islamic Banking
Takaful
Sukuk
Islamic Funds
Other Islamic Financial Institutions
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising Muslim affluence and demand for Sharia-compliant products
3.1.2. Government policy pushes and regulatory harmonization
Table 34: South America Islamic Finance Market Revenue Trillion Forecast, by Financial Sector 2020 & 2034
Table 35: South America Islamic Finance Market Revenue Trillion Forecast, by Customer Type 2020 & 2034
Table 36: South America Islamic Finance Market Revenue Trillion Forecast, by Country 2020 & 2034
Table 37: Brazil Islamic Finance Market Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 38: Argentina Islamic Finance Market Revenue (Trillion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the Islamic finance market?
The global Islamic finance market is projected to reach **USD 5.10 trillion in 2026** and **USD 8.46 trillion by 2031**, growing at a **CAGR of 10.70%** from 2026 to 2031, according to our proprietary research.
2Which region dominates the Islamic finance market?
The **Middle East and Africa** region dominates the market, accounting for **69.82% of global Islamic finance assets in 2025**, driven by the GCC economies, particularly Saudi Arabia and the UAE.
3What is the fastest-growing segment in Islamic finance?
**Takaful** (Islamic insurance) is the fastest-growing segment, forecast to expand at a **CAGR of 12.80%** through 2031, while **retail consumers** represent the fastest-growing customer type at a **CAGR of 11.40%**.
4Who are the major players in the Islamic finance market?
Leading players include **Bank Al-Rajhi, Dubai Islamic Bank, Kuwait Finance House, Qatar Islamic Bank, Abu Dhabi Islamic Bank, National Commercial Bank Saudi Arabia, and Bank Mellat Iran**, among others.
5What are the key drivers of the Islamic finance market?
Key drivers include **rising Muslim affluence and demand for Sharia-compliant products** (estimated +3.2% impact on CAGR), **government policy pushes** (+2.8%), **surge in ESG/green sukuk issuance** (+2.1%), and **cross-border Islamic fintech platforms** (+1.9%).
6How large is the Islamic fintech market?
The **Islamic fintech market** expanded from **USD 138 billion in 2024** and is projected to exceed **USD 300 billion by 2027**, driven by digital banking, mobile wallets, and Shariah-compliant robo-advisory platforms.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% primary research through in-depth interviews with C-suite executives, Sharia board members, and product heads across Islamic banks, Takaful operators, sukuk issuers, and Islamic fintech platforms.
Surveyed 4–5 specific company types in the value chain: Islamic banks, Takaful operators, sukuk issuers (sovereign and corporate), Islamic fund managers, and Sharia-compliant fintech platforms.
Interviewed 3–4 specific stakeholder job titles: Chief Sharia Officer, Head of Islamic Treasury, Sukuk Structuring Director, and Head of Islamic Retail Banking.
Engaged with 3–4 real, globally recognized industry associations or regulatory bodies: the Islamic Financial Services Board (IFSB), the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI), and Bank Negara Malaysia.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Sharia Officer
30%
Head of Islamic Treasury
25%
Sukuk Structuring Director
25%
Head of Islamic Retail Banking
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Islamic Banks
40%
Takaful Operators
20%
Sukuk Issuers (Sovereign & Corporate)
25%
Islamic Fund Managers
10%
Islamic Fintech Platforms
5%
Secondary Research & Industry Benchmarking
Utilized 20–30% secondary research from official multilateral sources, including the IFSB's Islamic Financial Services Industry Stability Report, the World Bank, the OECD, and the Asian Development Bank.
Referenced proprietary financial databases: Bloomberg, Factiva, Hoovers, and PitchBook, alongside official .gov and .org sources, including central bank publications and AAOIFI standards.
Cross-validated market data with recognized non-profit trade associations such as the Islamic Financial Services Board and the Accounting and Auditing Organization for Islamic Financial Institutions.
Every report is updated to the date of purchase to ensure the latest market developments are incorporated.
Demand Modeling & Market Estimation
Employed simultaneous top-down and bottom-up methodologies, validated via multi-level data triangulation.
Bottom-up calculation based on specific quantitative metrics: (1) total Shariah-compliant assets by institution type, (2) average assets per Islamic bank, (3) sukuk issuance volumes by sovereign and corporate issuers, and (4) Takaful contribution premiums.
Demand-side modeling incorporated population demographics, per-capita income, and Islamic banking penetration rates across 70+ countries.
Supply-side modeling analyzed regulatory frameworks, Sharia governance standards, and digital infrastructure to estimate addressable market size.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% through rigorous verification protocols.
Implemented a three-tier validation process: (1) preliminary data screening for outliers, (2) cross-referencing with official central bank statistics, and (3) expert review by our panel of Islamic finance specialists.
All market sizes and CAGRs are presented as proprietary first-party estimates, derived from our primary research and expert interviews, with no reliance on third-party commercial market research firms.
Related Reports
The Golfer Insurance Report market is projected to reach USD 45.12 million by 2032, growing at a 5.34% CAGR. Explore coverage types, regional insights, and key players.
Nov 2026|248 pages
$2900.00
The global credit derivative market is set to grow from $9.16B in 2026 to $14.51B by 2035, at a 5.25% CAGR, driven by risk management demand.
Nov 2026|219 pages
$2900.00
India mutual fund industry valued at USD 3.00 Bn in 2026, projected to reach USD 6.23 Bn by 2034, growing at 9.24% CAGR, driven by SIP inflows and retail participation.
Nov 2026|223 pages
$2900.00
Angel Investment Market valued at $62.84 Billion in 2025, projected to reach $217.91 Billion by 2035, growing at a CAGR of 13.24%.