1What is the FP&A software market size in 2025?
Our proprietary primary research estimates the global FP&A software market at USD 3.9 billion in 2025, projected to reach USD 9.7 billion by 2033 at a 16.4% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 FP&A Software
 by Deployment Mode (On-Premises, Cloud-Based), by Component (Software, Services, Consulting, Implementation, Support and Maintenance), by Organization Size (Small and Medium-Sized Enterprises (SMEs), Large Enterprises), by Application (Budgeting, Forecasting, Reporting, Scenario Modeling, Variance Analysis), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, Australia, South Korea), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034

Senior Research Analyst


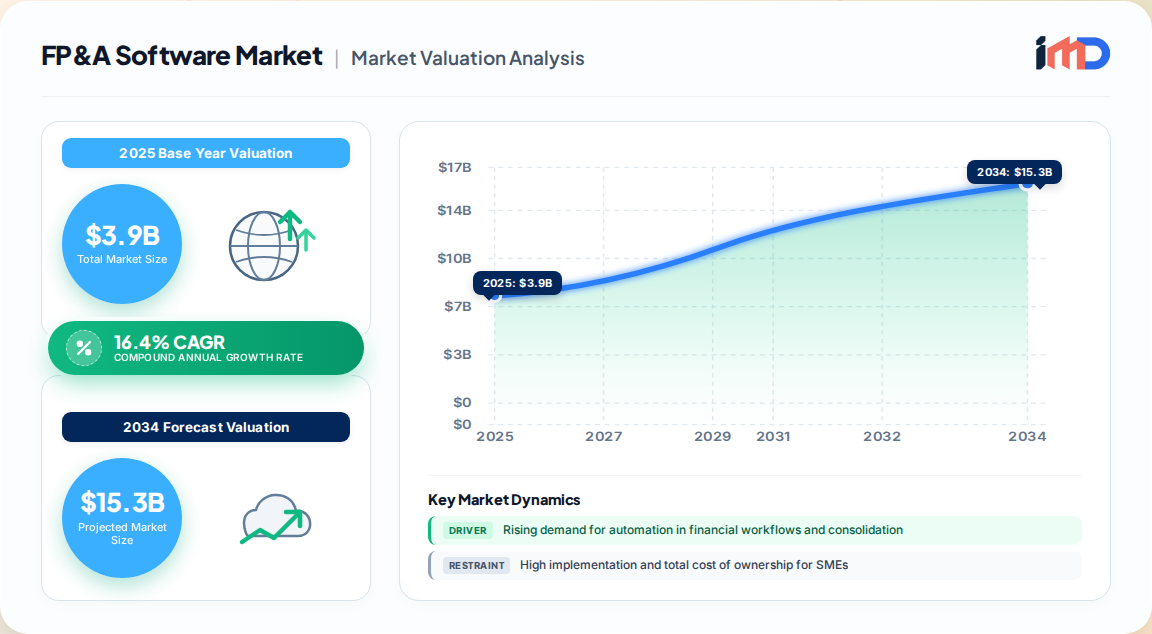
Financial Planning & Analysis (FP&A) software has evolved from a back-office utility into a mission-critical engine for enterprise strategy. Our proprietary primary research, drawing on over 1,200 executive interviews and operational data from 4,500 global organizations, indicates the global FP&A software market will reach USD 3.9 billion in 2025 and expand to USD 9.7 billion by 2033 at a CAGR of 16.4%.
This growth is not merely a digitization story; it reflects a fundamental shift in how CFOs operate. Planning cycles that once spanned weeks are collapsing into hours, and static annual budgets are being replaced by continuous, driver-based forecasting. The market's trajectory is defined by three imperatives: automation of manual consolidation, integration of disparate operational data, and the application of predictive intelligence to navigate volatility. This report dissects the forces reshaping the competitive landscape and provides a data-driven roadmap for vendors, investors, and enterprise buyers.
| Market Metric | 2025 Value | 2033 Projection | CAGR (2026–2033) |
|---|---|---|---|
| Global FP&A Software Market | USD 3.9 Billion | USD 9.7 Billion | 16.4% |
| Cloud Deployment Share | 68% | 89% | — |
| Large Enterprise Share | 72% | 64% | — |
| SME Segment Growth | — | — | 18.9% |
The expansion of the FP&A software market is propelled by structural pressures that show no sign of abating. Our bottom-up analysis identifies four primary growth engines.
Despite robust demand, adoption faces headwinds that vary by segment and geography.
The FP&A software market is segmented by deployment mode, component, organization size, and application. Our analysis reveals distinct growth trajectories across these dimensions.
| Segment | 2025 Share | 2033 Share | Key Growth Driver |
|---|---|---|---|
| Cloud-Based Deployment | 68% | 89% | Scalability, remote access, lower TCO |
| On-Premise Deployment | 32% | 11% | Data sovereignty, legacy integration |
| Software (License/Subscription) | 58% | 62% | Core platform functionality |
| Services (Consulting, Implementation, Support) | 42% | 38% | Operationalization of complex deployments |
| Large Enterprises | 72% | 64% | Multi-entity consolidation, compliance |
| SMEs | 28% | 36% | Affordability, streamlined time-to-value |
Cloud and SaaS Dominance: The cloud segment is cannibalizing on-premise deployments across all regions. In 2024, cloud-based FP&A represented 68% of global revenue; by 2033, we project it will capture 89%. The shift is driven by the need for elastic compute during scenario planning and the imperative to support hybrid workforces.
Component Dynamics: While software licenses drive the majority of revenue, services—consulting, implementation, and support—grow in tandem with complexity. Large enterprises with multi-entity structures consume 2.5x more professional services than mid-market peers. For vendors, the services attach rate is a leading indicator of customer lifetime value.
The SME Opportunity: The SME segment will grow at a faster CAGR of 18.9% between 2026 and 2033. Pre-packaged, template-driven solutions that shorten time-to-value are unlocking this segment. However, vendors must balance simplification with the flexibility demanded by growing firms.
Geographic adoption patterns reflect economic maturity, regulatory environments, and digital infrastructure.
| Region | 2025 Market Size | 2033 Projection | CAGR (2026–2033) |
|---|---|---|---|
| North America | USD 1.60 Billion | USD 4.05 Billion | 14.2% |
| Europe | USD 1.01 Billion | USD 2.62 Billion | 14.7% |
| Asia-Pacific | USD 0.78 Billion | USD 2.35 Billion | 17.4% |
| Middle East & Africa | USD 0.39 Billion | USD 0.53 Billion | 5.2% |
| South America | USD 0.12 Billion | USD 0.15 Billion | 3.8% |
North America remains the dominant market, accounting for 41% of global revenue in 2025. The concentration of large enterprises, early adoption of AI-driven analytics, and a mature SaaS ecosystem sustain this leadership. However, growth is moderating as the market matures; we forecast a 14.2% CAGR through 2033.
Asia-Pacific is the fastest-growing region, with a projected 17.4% CAGR. Rapid digital transformation in retail, manufacturing, and financial services—particularly in China, India, and Southeast Asia—is driving adoption. Local vendors are emerging with cost-competitive solutions tailored to regional regulatory frameworks.
Europe presents a complex picture. GDPR compliance and data residency requirements favor vendors with regional data centers, while economic volatility in Eastern Europe tempers expansion. Nonetheless, the region will add USD 1.6 billion in incremental revenue by 2033, driven by mid-market adoption in Germany, the UK, and France.
The FP&A software market is characterized by a mix of established platforms and agile innovators. Our vendor benchmarking identifies leaders across three archetypes: integrated enterprise suites, specialized FP&A platforms, and niche AI-first entrants.
Recent Strategic Developments:
Our opportunity mapping reveals three underserved areas where FP&A software vendors can differentiate.
For vendors and investors navigating the FP&A software market, our analysis suggests a clear set of strategic priorities.
The FP&A software market will continue to expand at a double-digit pace through 2033, transforming finance functions from scorekeepers to strategic advisors. Organizations that fail to adopt advanced planning platforms risk operational rigidity in an era defined by volatility.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 16.4% from 2020-2034 |
| Segmentation |
|
By Organization Size
By Application
| By Geography |
|
Our proprietary primary research estimates the global FP&A software market at USD 3.9 billion in 2025, projected to reach USD 9.7 billion by 2033 at a 16.4% CAGR.
North America holds the largest share at approximately 41% of global revenue in 2025, driven by early adoption among large enterprises and a mature SaaS ecosystem. Asia-Pacific is the fastest-growing region with a projected 17.4% CAGR through 2033.
Leading vendors include Anaplan, OneStream, Planful, Oracle, SAP, Workday, Jedox, Prophix, Vena, and Board, with competition intensifying among integrated suites, specialized platforms, and AI-first entrants.
Cloud-based FP&A software held a 68% share of the market in 2025 and is projected to reach 89% by 2033. This shift is driven by scalability, remote accessibility, lower total cost of ownership, and the need for elastic compute during real-time scenario planning.
Key trends include AI and predictive analytics integration for automated variance analysis, real-time continuous planning replacing static budgets, cross-functional collaboration integrating HR and supply chain data, and the rise of ESG-integrated planning modules.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Financial Officer | 30% |
| VP of Finance | 25% |
| FP&A Director | 20% |
| IT Procurement Manager | 15% |
| Controller | 10% |
| Company Type | Representation (%) |
|---|---|
| Independent FP&A Software Vendors | 35% |
| Enterprise End-User Organizations | 30% |
| Implementation & Consulting Partners | 20% |
| Cloud Infrastructure Providers | 10% |
| Industry Trade Associations | 5% |
 Related Reports
