1What is the current size of the liquor liability insurance market?
The global liquor liability insurance market was valued at **USD 4.11 Billion in 2025** and is projected to reach **USD 7.49 Billion by 2034**, growing at a **6.9% CAGR**.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Liquor Liability Insurance Market
 by Coverage Type (General Liability, Excess Liability, Assault & Battery, Property Damage, Others), by Application (Bars & Taverns, Restaurants, Nightclubs, Liquor Stores, Event Venues, Others), by Distribution Channel (Direct Sales, Brokers/Agents, Online Platforms, Others), by End-User (Small Businesses, Large Enterprises, Individuals), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, South Korea, India, ASEAN, Oceania), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Turkey, GCC, South Africa) Forecast 2026-2034

Research Associate


 Related Reports

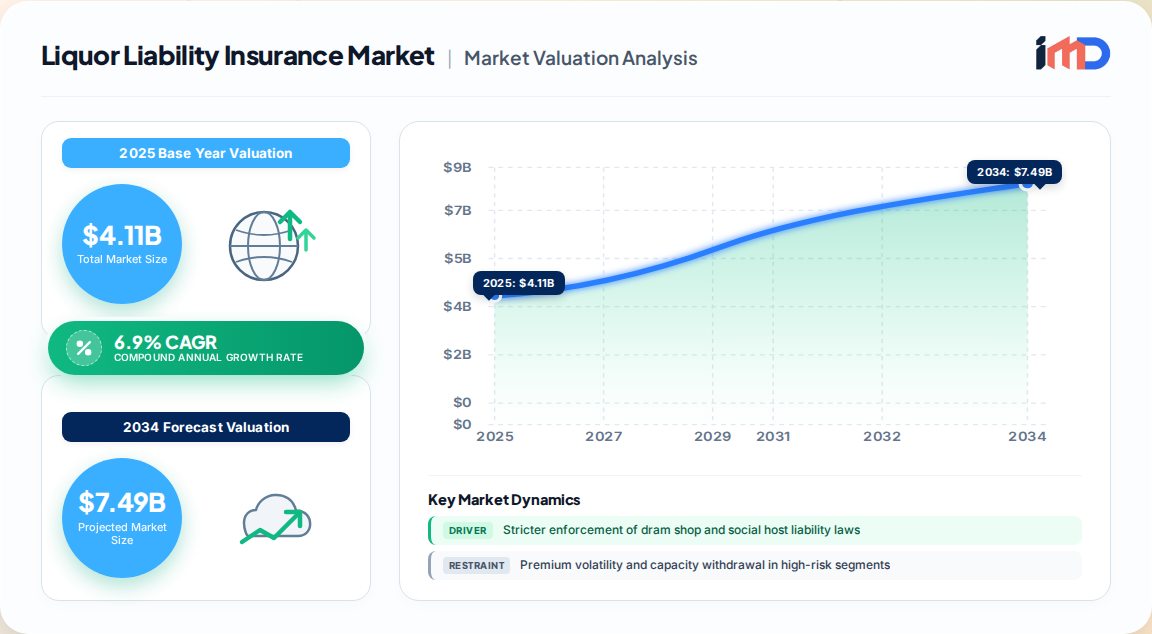
The global Liquor Liability Insurance market reached USD 4.11 Billion in 2025 and is forecast to expand at a 6.9% CAGR through 2034, propelling total market value to approximately USD 7.49 Billion. This growth is anchored in escalating regulatory enforcement of dram shop statutes and social host liability laws, a rising frequency of high-severity alcohol-related claims, and the rapid expansion of the global hospitality and nightlife economy. North America retains the dominant share at 42.5% of global revenue, while Asia-Pacific emerges as the fastest-growing corridor. Insurers are responding with data-driven underwriting, flexible policy structures, and digital distribution models that broaden access for small and mid-sized venues.
Demand-side momentum is reinforced by the post-2022 recovery of the hospitality sector, with new bar, restaurant, and event venue openings accelerating the addressable insured base. Litigation severity—particularly third-party auto and bodily injury claims involving intoxicated patrons—continues to push premium rates upward and compel operators to purchase higher limits.
The liquor liability value chain spans specialized underwriting units within multi-line carriers, wholesale brokers and managing general agents (MGAs) that aggregate niche risks, and digital insurtech platforms providing real-time quoting for small businesses. Claims handling involves specialized defense counsel and forensic investigation of service records, patron age verification, and server training compliance.
| Value Chain Stage | Core Activity | Strategic Implication |
|---|---|---|
| Product Design & Underwriting | Actuarial modeling of alcohol sales mix and claims history | Carriers increasingly price on pour-rate and server-training data |
| Distribution | Direct sales, brokers/agents, online platforms | Online channels lower acquisition costs for small venues |
| Risk Management Services | Server training certification, incident documentation | Value-added services reduce claims frequency and improve retention |
| Claims & Litigation | Defense, settlement, subrogation | Severity trends drive reserve strengthening and rate increases |
The market is segmented by coverage type, application, distribution channel, and end-user. General liability coverage remains the cornerstone, often incorporating liquor liability as an endorsement or sub-limit, while standalone liquor liability policies serve high-risk entities such as nightclubs, distilleries, and large event organizers. Among applications, bars and taverns account for the largest revenue share, given their high alcohol-sales concentration and elevated claims exposure. Online platforms represent the fastest-growing distribution channel, reflecting broader digitalization of commercial insurance procurement.
North America's dominance is supported by a mature insurance infrastructure and stringent dram shop enforcement, with the United States alone representing the largest single-country market. Europe maintains steady growth underpinned by well-established legal frameworks and rising awareness among hospitality operators. Asia-Pacific is the fastest-growing region, driven by urbanization, rising disposable incomes, and expansion of modern hospitality infrastructure in China, India, and Southeast Asia.
Cross-border supply dynamics for this line are shaped less by physical trade and more by regulatory harmonization and reinsurance capacity flows. Official trade data from Eurostat and UN Comtrade inform our assessment of hospitality-sector growth as a leading indicator of insurance demand across EU member states and key Asia-Pacific markets.
The market features intense competition among global multi-line insurers and specialized underwriters. Leading carriers—including Axa SA, Allianz SE, Chubb Limited, Zurich Insurance Group, and The Travelers Companies Inc.—leverage deep underwriting expertise and extensive broker networks. Strategic priorities include portfolio de-risking in high-severity segments, investment in insurtech partnerships for small-business quoting, and expansion of risk-management services such as server-training certification and incident documentation.
Underserved opportunities exist in emerging Asia-Pacific hospitality markets, where mandatory liquor liability requirements are still maturing. Insurtech-enabled micro-policies for pop-up events and private-party hosts represent a nascent but rapidly growing niche. Additionally, integrating liquor liability with broader hospitality liability programs—covering food service, event cancellation, and property—creates cross-sell potential for carriers seeking to deepen customer relationships and improve retention.
While liquor liability insurance is not a physical traded commodity, its demand is closely tied to the import and distribution of alcoholic beverages. Regulatory changes affecting alcohol import licensing, labeling, and excise duties directly influence the number of licensed premises and, consequently, the insured base. EU import procedures governed by Access2Markets and national licensing regimes shape the operating environment for liquor retailers and hospitality venues. Insurers monitoring these trade flows gain early visibility into emerging demand pockets and regulatory compliance risks.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.9% from 2020-2034 |
| Segmentation |
|
By Application
By Distribution Channel
By End-User
| By Geography |
|
The global liquor liability insurance market was valued at **USD 4.11 Billion in 2025** and is projected to reach **USD 7.49 Billion by 2034**, growing at a **6.9% CAGR**.
North America holds the largest share at approximately **42.5% of global revenue in 2025**, driven by stringent dram shop laws, a high concentration of licensed hospitality businesses, and a mature insurance infrastructure.
Key drivers include stricter enforcement of dram shop and social host liability laws, rising frequency and severity of alcohol-related claims, expansion of the hospitality and nightlife sector, and growing awareness among small-business owners of personal asset exposure.
Leading insurers include **Axa SA, Allianz SE, Chubb Limited, Zurich Insurance Group, and The Travelers Companies Inc.**, alongside specialized underwriters such as The Hartford, Nationwide, CNA Financial Corporation, and Markel Corporation.
The **business segment**, particularly bars, taverns, and nightclubs, represents the largest revenue opportunity due to high alcohol-sales concentration and elevated claims exposure. Online distribution platforms are the fastest-growing channel.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Underwriting Officer | 30% |
| Hospitality Risk Manager | 25% |
| Insurance Broker/Agent | 25% |
| Compliance Director | 20% |
| Company Type | Representation (%) |
|---|---|
| Multi-line commercial insurers | 35% |
| Specialty MGAs and underwriters | 20% |
| Wholesale brokers and agents | 25% |
| Insurtech quoting platforms | 10% |
| Third-party claims administrators | 10% |