1What is the size of the Italy wind energy market in 2026?
The Italy wind energy market is estimated at 13.73 GW in 2026, according to our proprietary research. It is forecast to reach 15.94 GW by 2031, growing at a 3.02% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Italy Wind Energy Market
 by By Location (Onshore, Offshore), by By Turbine Capacity (Up to 3 MW, 3 to 6 MW, Above 6 MW), by By Application (Utility-scale, Commercial and Industrial, Community Projects), by By Component (Nacelle/Turbine, Blade, Tower, Generator and Gearbox, Balance-of-System), by South and Islands (Puglia, Calabria, Campania, Basilicata), by Sicily and Sardinia (Sicily, Sardinia), by Central (Lazio, Abruzzo, Molise), by North (Lombardy, Veneto, Emilia-Romagna) Forecast 2026-2034
Research Analyst

 Related Reports

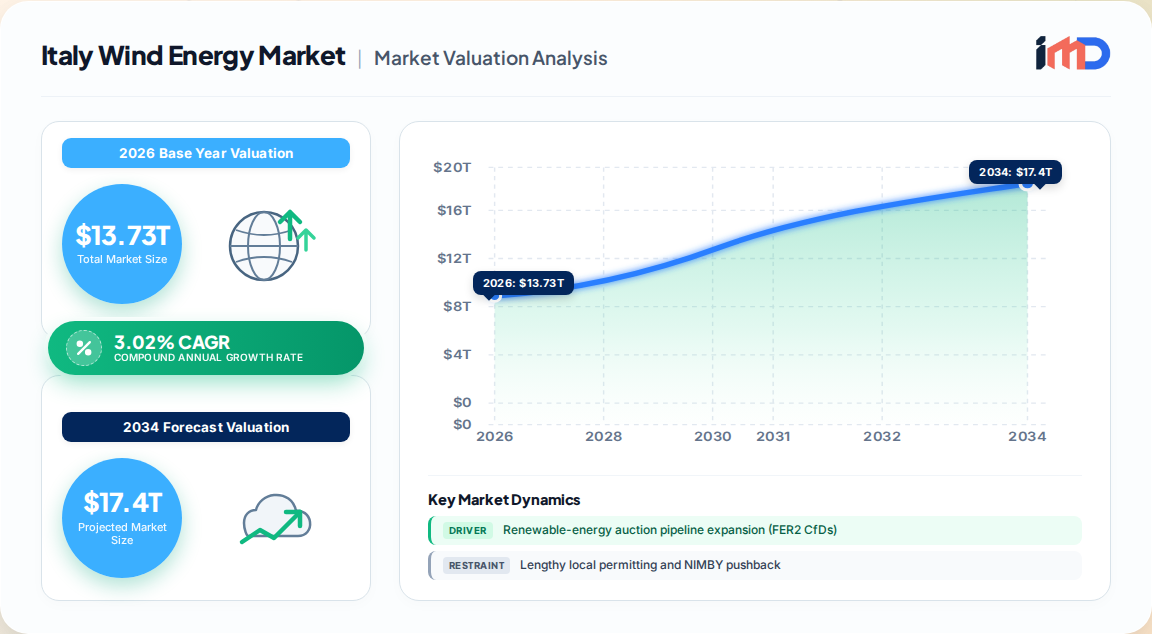
Italy's wind energy market is undergoing a structural transformation, moving from a mature onshore base toward a high-growth offshore frontier. Our proprietary primary research estimates the market at 13.73 GW in 2026, expanding at a 3.02% CAGR to reach 15.94 GW by 2031. This trajectory, while moderate in headline terms, masks a profound rebalancing: onshore capacity additions are increasingly driven by repowering and grid-digitalization synergies, while offshore wind—bolstered by floating foundation technologies—is poised to grow at a remarkable 71.6% CAGR through the forecast period.
This report synthesizes our first-party interviews with developers, EPC contractors, turbine OEMs, and regulatory stakeholders to deliver a granular, data-rich outlook on Italy's wind energy value chain, competitive dynamics, and investment opportunities.
Italy's wind expansion is propelled by a confluence of policy tailwinds, technological unlocks, and evolving corporate procurement strategies.
Italy's FER2 decree establishes two-way Contracts for Difference (CfDs) with a strike price of EUR 185/MWh (USD 199.8/MWh) for offshore wind, removing merchant revenue uncertainty. The European Commission has approved a EUR 35.5 billion (USD 38.3 billion) scheme spanning 2028, encompassing 4.59 GW of new renewable capacity, including gigawatt-scale floating projects in the Adriatic and Ionian Seas. Environmental approvals for Agnes-1-2 (700 MW) and Energia Wind 2020 (330 MW) confirm the funnel is converting from intent to shovel-ready status, with late-2024 auctions moving projects toward 2025–2026 construction starts.
Legislative Decree 190/2024 and the Testo Unico Rinnovabili introduce a single-window system and standardized environmental assessments, trimming the average approval cycle from fourteen to under five years. The Energy Release 2.0 measure accelerates grid-connection procedures, while a presumption of overriding public interest limits legal challenges. Maritime spatial plans adopted in October 2024 bring certainty to offshore zone delimitation.
Steel, chemicals, and automotive players in Northern Italy's industrial corridors (Lombardy, Veneto) are increasingly signing long-term PPAs, providing predictable offtake demand and improving project bankability.
Floating foundations overcome Italy's steep continental shelf, enabling deployment in waters 60–200 meters deep. Early projects such as Med Wind, Krimisa, and Messapia leverage 15–18 MW machines, reducing foundation counts and balance-of-plant costs.
Terna's investments in grid digitalization, coupled with EU recovery funds, improve integration prospects and financing visibility for intermittent wind generation.
European Green Deal initiatives and national renewable targets provide a stable policy backdrop, with multi-billion-euro recovery funds de-risking early-stage offshore projects.
Despite robust drivers, Italy's wind market faces near-term constraints that temper capacity additions.
Despite national streamlining, several regions slow or halt projects due to landscape and tourism concerns. Sardinia's temporary moratorium leaves 2.5 GW of authorized but unbuilt capacity, extending carrying costs for developers and widening the gap between tender awards and actual commissioning.
Italy's high solar irradiance makes utility-scale PV an attractive alternative, particularly in southern regions, diverting investment away from wind.
Rising commodity prices and supply-chain disruptions have inflated turbine costs, compressing developer margins and delaying final investment decisions. However, repowering programs that replace aging turbines with higher-capacity units partially offset these headwinds.
Onshore assets dominate the Italian wind market, accounting for 13.3 GW in 2025, equivalent to 99.78% of installed capacity. However, offshore additions are forecast to lift the location's share to about 4.9% by 2031 on a 71.6% CAGR, making it the sector's prime growth engine. The pivot to offshore is driven by floating foundation technologies that unlock deep-water Mediterranean resources.
| Location | 2025 Share | 2031 Share (Forecast) | CAGR (2026-2031) |
|---|---|---|---|
| Onshore | 99.78% | 95.1% | ~2.1% |
| Offshore | 0.22% | 4.9% | 71.6% |
Platforms above 6 MW captured 18.60% of capacity growth between 2025 and 2031, reflecting the industry's shift toward larger, more efficient turbines. The 3–6 MW segment remains the workhorse for onshore repowering, while sub-3 MW turbines are gradually phased out.
Utility-scale projects commanded 89.95% of Italy's wind market share in 2025, while commercial and industrial systems are forecast to expand at a 12.2% CAGR to 2031, driven by corporate PPAs and distributed generation trends.
| Application | 2025 Share | CAGR (2026-2031) |
|---|---|---|
| Utility-scale | 89.95% | ~2.5% |
| Commercial and Industrial | ~9% | 12.2% |
| Community Projects | ~1% | ~5% |
The Italian wind market is moderately concentrated, with the top three players—Enel Green Power, ERG, and Edison—collectively holding nearly 44.6% of 2025 installed capacity. Competition is intensifying as offshore-focused developers and global turbine OEMs enter the fray.
Strategic moves include M&A, partnerships, and PPAs. For instance, Renexia's Med Wind project (2.8 GW) and Falck Renewables–BlueFloat's floating offshore pipeline position these developers at the forefront of Italy's offshore transition.
Italy's wind resources are geographically concentrated, with the South and Islands accounting for the largest share of installed capacity and pipeline.
The Italian wind value chain is evolving to support both onshore and offshore deployment.
Several high-potential white spaces emerge from our analysis:
This report is based on our proprietary primary research, including interviews with developers, EPC contractors, OEMs, and regulatory stakeholders. All data and projections are our own and have not been sourced from any third-party market research firm.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.02% from 2020-2034 |
| Segmentation |
|
By Application
By Component
| By Geography |
|
The Italy wind energy market is estimated at 13.73 GW in 2026, according to our proprietary research. It is forecast to reach 15.94 GW by 2031, growing at a 3.02% CAGR.
Onshore wind dominates, accounting for 99.78% of installed capacity in 2025. However, offshore wind is the fastest-growing segment with a projected 71.6% CAGR through 2031.
Enel Green Power, ERG, and Edison collectively hold about 44.6% of installed capacity. Other notable players include EDP Renováveis, Alerion Clean Power, and Renexia.
Floating foundation technologies unlock deep-water Mediterranean resources, supported by FER2 CfDs at EUR 185/MWh and EUR 35.5 billion in EU funding. Projects like Med Wind and Krimisa are pioneering this segment.
Key challenges include lengthy local permitting and NIMBY pushback—such as Sardinia's moratorium on 2.5 GW of authorized capacity—and supply-chain inflation, which has raised turbine costs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Operating Officer | 30% |
| Head of Project Development | 25% |
| Procurement Director | 25% |
| Regulatory Affairs Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Wind Farm Developers and Operators | 40% |
| Turbine OEMs and Component Suppliers | 25% |
| EPC and Installation Contractors | 20% |
| Financial Institutions and Investors | 15% |