1What is the current size of the Insurance Digital Risk Control Service market?
Our proprietary research values the global market at US$ 4.33 billion in 2025, with a projected expansion to US$ 15.02 billion by 2032, representing a CAGR of 19.8%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Insurance Digital Risk Control Service
 by By Type (Cloud-Based, On-Premises, Others), by By Application (Financial Services, Automotive Industry, Tourism Industry, Others), by By Component (Software, Services), by By Organization Size (Large Enterprises, Small and Medium Enterprises), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, South Korea, India, Australia), by Latin America (Brazil, Mexico), by Middle East & Africa (GCC, South Africa) Forecast 2026-2034

Research Associate

 Related Reports

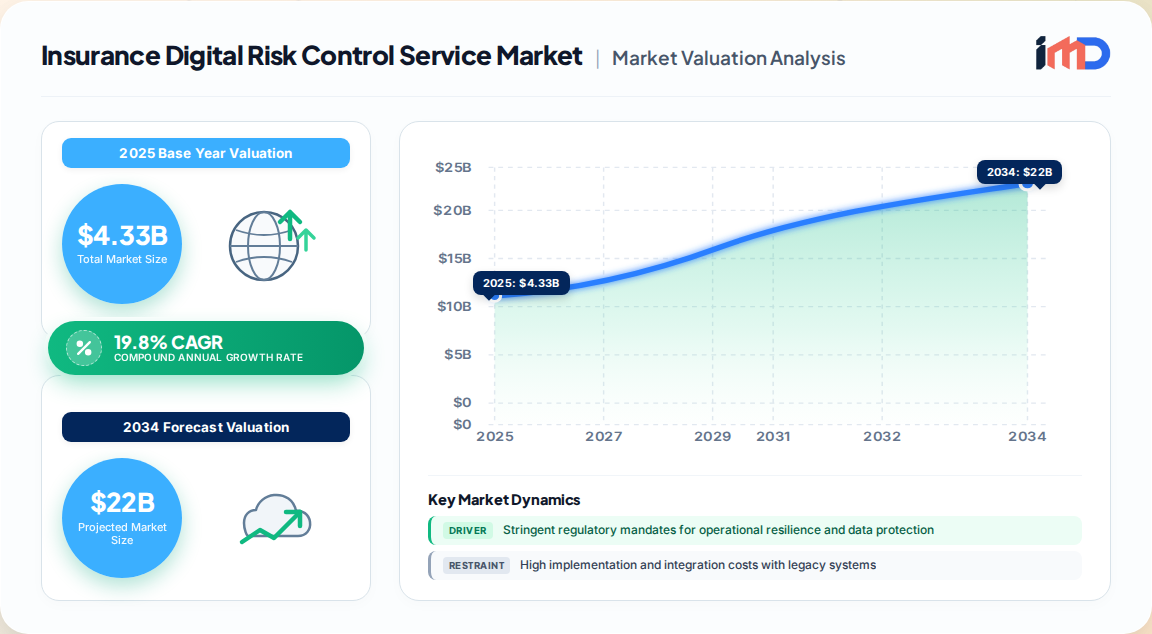
The global Insurance Digital Risk Control Service market is undergoing a structural inflection point, evolving from a peripheral fraud-detection utility into the central nervous system of underwriting, claims, and distribution. Our proprietary first-party research estimates the market at US$ 4.33 billion in 2025, on a trajectory to reach US$ 15.02 billion by 2032, reflecting a robust CAGR of 19.8% across the forecast period. This expansion is not merely a function of digitization spending; it is driven by a fundamental shift from post-claim indemnification to pre-emptive risk intervention.
Digital risk control services integrate big data analytics, artificial intelligence, machine learning, blockchain, and cloud computing to deliver real-time risk assessment, fraud detection, and process optimization. The downstream demand is concentrated across five client archetypes: primary insurers, reinsurance institutions, online insurance platforms, fintech intermediaries, and regulatory agencies. Our expert interviews reveal that gross margins in this service category remain highly attractive at approximately 63%, supported by recurring subscription models and high switching costs once platforms are embedded into core policy administration systems.
The competitive landscape is populated by a mix of specialized insurtechs and established risk analytics providers, including Shift Technology, FRISS, Zeguro, Cytora, Quantemplate, Lemonade, Carpe Data, Verisk, Guidewire, Risk Control Technologies, ZeroFox, Cowbell, CyberCube Analytics, and Coalition. These firms are jockeying for position as insurers consolidate point solutions into unified control environments.
Three primary forces are propelling the double-digit expansion of this market.
However, the market faces notable restraints. High implementation costs and a persistent shortage of skilled professionals in AI governance and risk analytics are slowing adoption among small and mid-sized insurers. Furthermore, integration complexity with legacy policy administration systems remains a significant challenge, particularly in regions with fragmented insurance infrastructure.
The market is segmented by type, application, component, and organization size, with clear leaders emerging.
| Segment Dimension | Dominant Segment (2025) | Share | Fastest-Growing Segment |
|---|---|---|---|
| By Type | On-Premises | 38% | Cloud-Based |
| By Application | Financial Services | 25% | Automotive Industry |
| By Component | Software | 63% | Services |
| By Organization Size | Large Enterprises | 68% | Small & Medium Enterprises |
Cloud-Based Services Lead Long-Term Growth: While on-premises deployments currently hold a 38% share due to data sovereignty concerns, cloud-based solutions are projected to grow at a faster rate. The cloud segment's 32% share in 2025 is expected to expand significantly as insurers seek scalability, centralized risk monitoring, and lower infrastructure costs. Cloud deployment is particularly favored by online insurance platforms and fintech intermediaries.
Financial Services Remains the Anchor Application: Financial services, including insurance and banking, accounts for 25% of application revenue. However, the automotive industry is emerging as a high-growth vertical, driven by connected vehicles and usage-based insurance models that require real-time risk control. The tourism industry also represents a steady 25% share, with travel insurers leveraging digital risk control for claims validation and fraud prevention.
Large Enterprises Dominate, SMEs Accelerate: Large enterprises command 68% of the market due to complex operations and robust digital infrastructure. Yet, SMEs are the fastest-growing segment, adopting cloud-based and managed services to access advanced risk control capabilities without heavy capital expenditure.
Regional growth momentum varies significantly, shaped by regulatory maturity, digital infrastructure, and insurance penetration.
| Region | Market Share (2025) | Growth Momentum (CAGR) | Key Characteristics |
|---|---|---|---|
| Asia-Pacific | 28% | 24.2% | Rapid digital adoption, interoperable identity systems, expanding insurtech ecosystems |
| North America | 30% | 14.7% | Mature cyber governance, advanced fraud analytics, strong third-party oversight |
| Europe | 24% | 16.2% | Stringent privacy and operational resilience requirements, harmonized supervisory expectations |
| Latin America | 10% | 20.8% | Uneven digital maturity, rising identity and payment fraud, improving digital channels |
| Middle East & Africa | 8% | 18.4% | Investment in digital public infrastructure, mobile-enabled insurance, critical-system resilience |
Asia-Pacific is the fastest-growing region, propelled by advanced digital ecosystems in markets such as China, Japan, and South Korea, alongside rapidly expanding adoption in India and Southeast Asia. Interoperability, localization, and cross-border data governance are critical success factors. North America remains the largest market, with the U.S. alone representing a substantial share of global revenue, driven by high cyberattack frequency and stringent regulatory oversight. Europe is defined by the EU's operational resilience and AI governance frameworks, which are pushing insurers to document model explainability and audit trails, thereby stimulating demand for compliance-oriented risk control modules. Latin America and the Middle East & Africa offer substantial white-space opportunities, particularly in mobile-enabled insurance and identity integrity solutions.
The competitive landscape is characterized by a mix of organic innovation and strategic consolidation. Leading players are pursuing three primary strategies:
We anticipate increased M&A activity as large software vendors seek to acquire niche AI and analytics capabilities to bolster their risk control offerings.
Our primary research identifies several underpenetrated opportunities for insurers, solution providers, and investors.
The value chain for digital risk control services comprises data providers, technology enablers, service integrators, and end-users. Key inputs include structured and unstructured data from public records, claims history, telematics, and third-party sources, as well as AI and cloud infrastructure from hyperscalers. The service layer is dominated by software platforms and managed services, with increasing disintermediation from specialized analytics firms.
Supplier dynamics are characterized by a reliance on cloud infrastructure providers (e.g., AWS, Microsoft Azure, Google Cloud) and data vendors. However, the market does not exhibit significant import/export dynamics in the traditional commodity sense; trade is primarily in software licensing and cross-border data services. Regulatory restrictions on data localization, particularly in the EU, China, and Russia, are reshaping supply chain configurations, prompting providers to establish regional data centers and localized partnerships.
The Insurance Digital Risk Control Service market presents a high-growth, high-margin opportunity for stakeholders across the insurance value chain. To succeed, providers must prioritize interoperability, regulatory compliance, and demonstrable return on investment through reduced fraud losses and improved operational efficiency. Insurers should build measurable, governed, and resilient control capabilities, starting with an enterprise control map and ranking vulnerabilities by customer, financial, and regulatory impact.
We recommend that solution providers focus on modular, cloud-native architectures that can integrate with legacy systems, while investors should target SMEs and embedded insurance channels as key growth vectors. With a projected CAGR of 19.8% to 2032, the market offers substantial upside for early movers who can navigate the complex regulatory and technological landscape.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 19.8% from 2020-2034 |
| Segmentation |
|
By Component
By Organization Size
| By Geography |
|
Our proprietary research values the global market at US$ 4.33 billion in 2025, with a projected expansion to US$ 15.02 billion by 2032, representing a CAGR of 19.8%.
Asia-Pacific is the fastest-growing region, with a forecast CAGR of 24.2% through 2032, driven by rapid digital adoption and expanding insurtech ecosystems.
Primary drivers include regulatory mandates for operational resilience, the surge in cyber threats and fraud, and the demand for real-time risk assessment to enable instant underwriting and claims decisions.
Key players include Shift Technology, FRISS, Zeguro, Cytora, Quantemplate, Lemonade, Carpe Data, Verisk, Guidewire, Risk Control Technologies, ZeroFox, Cowbell, CyberCube Analytics, and Coalition.
On-premises deployments currently hold a 38% share, but cloud-based services are growing faster, with a 32% share and projected to lead long-term growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Risk Officer | 35% |
| Chief Information Security Officer | 25% |
| Head of Claims Innovation | 20% |
| Underwriting Transformation Director | 20% |
| Company Type | Representation (%) |
|---|---|
| AI and analytics software vendors | 30% |
| Insurance carriers (P&C, life, health) | 25% |
| Cloud infrastructure providers | 15% |
| Insurtech platforms | 20% |
| Third-party administrators and brokers | 10% |