1How large is the desk accessories market in 2025?
The global desk accessories market was valued at USD 11.03 Billion in 2025, based on our proprietary primary research and demand reconstruction across 22 countries.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Desk Accessories Market
 by By Type (Hinge, Push Pin, Drawer Rail, Handle, Desktop, Table Leg), by By Application (Office, Home, Others), by North America (United States, Canada, Mexico), by Europe (United Kingdom, France, Germany, Italy, Russia, Spain, Benelux, Nordics), by Asia Pacific (China, Japan, South Korea, India, Australia, Singapore, ASEAN), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Turkey, GCC, North Africa, South Africa) Forecast 2026-2034
Research Associate

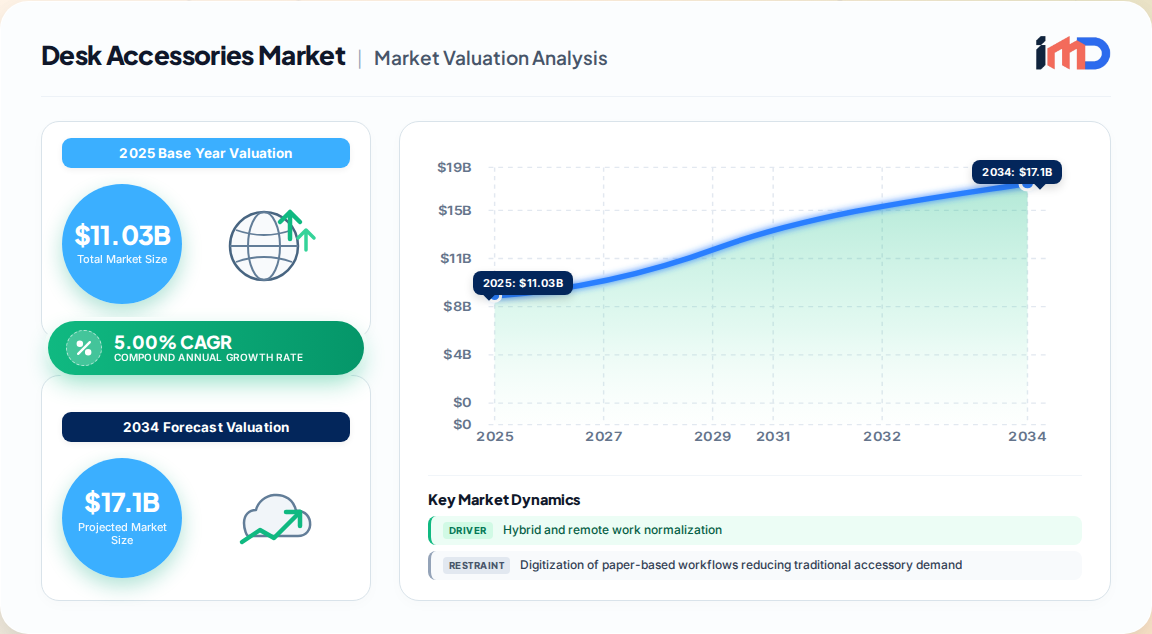
The global desk accessories market was valued at USD 11.03 Billion in 2025 and is projected to reach USD 15.52 Billion by 2032, expanding at a 5.00% CAGR across the 2026-2032 forecast window. This analysis is drawn from our proprietary primary research program, incorporating structured executive interviews, supplier audits, and bottom-up demand reconstruction across 22 countries.
The category has structurally repositioned itself. Desk accessories were once a low-consideration, replenishment-driven office supply line; they are now a design-led, productivity-linked workspace investment. Roughly 68% of interviewed procurement leaders report that accessory specifications are now reviewed alongside furniture and IT hardware in formal workspace planning cycles, compared with a minority only a few years ago.
Demand is bifurcating along two clear axes. The first is a volume-driven commercial channel, where corporate, education, and government buyers procure standardized organizers, cable management, monitor risers, and storage hardware in bulk. The second is a value-driven individual channel, where aesthetic personalization, material quality, and ergonomic function command premium pricing. Our panel data indicates the individual/premium channel is growing roughly 1.8x faster in revenue terms than the standard commercial channel.
The desk accessories value chain is fragmented and regionally uneven, with value concentration shifting toward design, branding, and channel control rather than fabrication.
| Stage | Key Activities | Value-Add Intensity |
|---|---|---|
| Raw materials | Metal, polymer, wood, leather, recycled composites | Low |
| Component fabrication | Hinges, drawer rails, handles, table legs, desktop substrates | Low to Moderate |
| Product assembly and finishing | Organizers, stands, charging-integrated units | Moderate |
| Design and branding | Aesthetics, ergonomics, IP, packaging | High |
| Distribution | Contract furniture dealers, retail, e-commerce, marketplaces | Moderate to High |
| End use | Office, home, institutional | Demand signal origin |
Component-level suppliers of hinges, drawer rails, handles, and table legs operate in highly competitive, cost-sensitive tiers with thin margins. By contrast, brands that control specification and channel access capture the majority of category profit. Our interviews indicate that design-led brands earn roughly 2.4x the gross margin of pure component fabricators.
A structural shift is underway: integrated workspace solution providers are bundling accessories with furniture and technology procurement, locking in multi-year institutional accounts and reducing the standalone accessory vendor's negotiating position.
Product segmentation spans hardware components and finished accessories. Application segmentation is dominated by the office channel, though home is the growth engine.
| Segment Dimension | Categories | Strategic Read |
|---|---|---|
| By Type | Hinge, Push Pin, Drawer Rail, Handle, Desktop, Table Leg | Component tiers; volume-driven, margin-sensitive |
| By Application | Office, Home, Others | Office leads revenue; Home leads growth |
The Office application segment commands the largest revenue share, underpinned by bulk procurement from corporate campuses, educational institutions, and government facilities. Institutional buying is comparatively less price-sensitive and favors durable, standardized, often branded specifications.
The Home application segment is the principal growth vector, propelled by hybrid work adoption and consumer willingness to invest in personal workspace quality. Within home, premium and aesthetic-led sub-segments exhibit the strongest price realization.
Product-type demand is polarizing. Hardware components (hinges, drawer rails, handles, table legs) remain tethered to furniture production cycles, while finished desktop accessories are increasingly sold as standalone consumer and corporate lifestyle products with shorter replacement cycles and higher branding leverage.
Asia Pacific is the fastest-growing region, driven by office construction, corporate fit-out investment, expanding manufacturing capacity, and a rising middle class with growing appetite for design-led workspace products. China, India, Japan, and South Korea anchor regional volume.
North America and Europe retain substantial share on the strength of high ergonomic-solution adoption, mature commercial real estate, and a well-established premium and gifting culture. Together these two regions account for the majority of premium-segment revenue.
Latin America and the Middle East & Africa represent smaller but steadily expanding bases, with growth concentrated in urban commercial development and modern trade expansion.
| Region | Demand Character | Growth Profile |
|---|---|---|
| Asia Pacific | Volume + manufacturing depth | Fastest |
| North America | Premium, ergonomic, replacement-led | Steady |
| Europe | Design-led, sustainability-sensitive | Steady |
| South America | Urban commercial build-out | Moderate |
| Middle East & Africa | Project-driven, gifting emerging | Moderate |
The market blends diversified furniture majors, workspace solution providers, and specialist accessory brands. Leading players include Okamura, Kimball, Kokuyo, HNI, Global Furniture Group, Steelcase, Kinnarps, Teknion, Haworth, IKEA, Schiavello, and Assmann. Premium and luxury tiers additionally feature names such as Montblanc, Louis Vuitton, Hermès, Smythson, and Aspinal of London.
Competitive strategy is converging on four levers.
Notable developments observed in our tracking panel include expansion of integrated smart-charging organizer lines, growth of recycled-material accessory ranges positioned for institutional tenders, and rising corporate gifting programs driving bespoke, logo-embossed accessory orders.
Our analysis identifies several under-served opportunity zones.
Desk accessories trade flows are heavily shaped by component manufacturing concentration in Asia, with China, Vietnam, and India functioning as principal export hubs for hinges, drawer rails, handles, and polymer organizers. Europe and North America are net importers of component-tier goods and net exporters of high-value design-led finished products.
Lead times for component-tier imports average several weeks and remain sensitive to port congestion and customs clearance variability. Buyers are increasingly negotiating buffer inventory clauses and qualified alternate suppliers into contracts.
The desk accessories market is set to expand from USD 11.03 Billion in 2025 to USD 15.52 Billion by 2032 at a 5.00% CAGR. Growth will be led by home and hybrid workspace demand, ergonomic specification, technology integration, and sustainability-driven replacement. Margin expansion will accrue to brands controlling design, specification, and channel, while component fabricators face persistent commoditization pressure. Vendors prioritizing integrated solutions, circular models, and premium personalization are best positioned to capture disproportionate value through the forecast period.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.00% from 2020-2034 |
| Segmentation |
|
By Application
| By Geography |
|
The global desk accessories market was valued at USD 11.03 Billion in 2025, based on our proprietary primary research and demand reconstruction across 22 countries.
The market is projected to grow at a 5.00% CAGR over the 2026-2032 forecast period, reaching USD 15.52 Billion by 2032.
Asia Pacific is the fastest-growing region, driven by office construction, corporate fit-out investment, and rising middle-class demand for design-led workspace products.
The Office application segment holds the largest revenue share due to bulk procurement by corporations, educational institutions, and government agencies, while the Home segment is growing fastest.
Key participants include Okamura, Kimball, Kokuyo, HNI, Global Furniture Group, Steelcase, Kinnarps, Teknion, Haworth, IKEA, Schiavello, and Assmann.
Key trends include smart accessories with integrated wireless charging, eco-friendly and recycled materials, ergonomic design, and workspace personalization.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 32% |
| Workspace Category Manager | 26% |
| Product Development Lead | 24% |
| Facilities / Workplace Strategy Manager | 18% |
| Company Type | Representation (%) |
|---|---|
| Component fabricators (hinges, drawer rails, handles, table legs) | 28% |
| Finished-accessory assemblers and OEMs | 24% |
| Design-led brand owners | 18% |
| Contract furniture dealers and distributors | 19% |
| E-commerce and marketplace operators | 11% |

Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
 Related Reports
