Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
India Office Furniture Market Size, Growth & Forecast 2026-2031
Independent Intelligence for decisions that move markets
India - Office Furniture Market | Insight Market Data
India - Office Furniture Market by Product (Seating, Tables, Storage units and files, Overhead bins, Systems), by Material (Wood, Metal, Plastic, Engineered wood), by End-user (Commercial office furniture, Home office furniture, Hospitality and retail back-office), by Distribution Channel (Offline, Online, B2B direct-from-manufacturer, B2C retail), by Price Range (Economy, Mid-range, Premium), by North (Delhi NCR, Haryana, Punjab), by West (Maharashtra, Gujarat, Rajasthan), by South (Karnataka, Telangana, Tamil Nadu, Kerala), by East (West Bengal, Odisha, Bihar) Forecast 2026-2034
The global Oriented Strand Board (OSB) for Furniture market is projected to grow at a CAGR of 6.8% from 2026 to 2033, driven by sustainable furniture demand.
The global workshop furniture market is valued at $1.59 billion in 2025 and is set to reach $2.15 billion by 2032, growing at a 4.5% CAGR.
Nov 2026|254 pages
$2900.00
Consumer shifts in the home and garden products market drive a 4.3% CAGR toward $29.5 billion by 2030, led by sustainability, smart tools and e-commerce.
Nov 2026|196 pages
$2900.00
Camping furniture market size is $289.3M in 2026, projected to reach $406.5M by 2033 at a 5.0% CAGR. Explore product, channel, and regional insights.
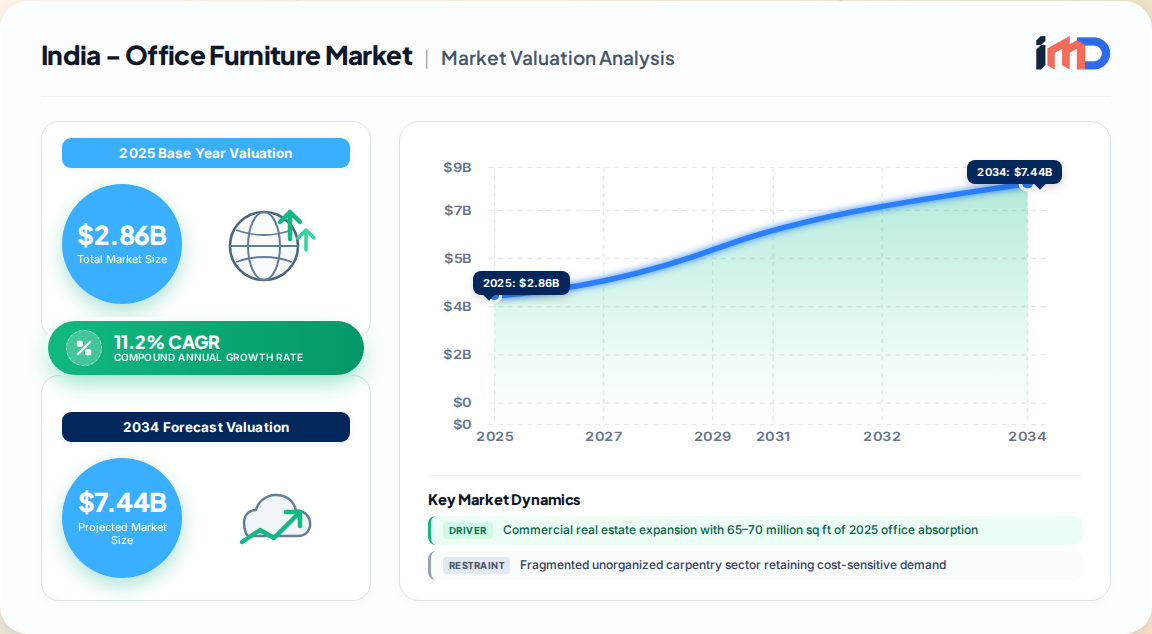
The India office furniture market is in a structurally elevated growth phase, expanding at a CAGR of 11.2% across the current forecast window and adding approximately USD 3.09 Billion in incremental revenue. India already accounts for roughly 15% of global office furniture consumption, placing it among the three most consequential demand centres worldwide alongside China and the United States.
India - Office Furniture Market Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
2.860 B
2025
3.180 B
2026
3.537 B
2027
3.933 B
2028
4.373 B
2029
4.863 B
2030
5.407 B
2031
Growth is no longer a simple derivative of headcount addition. It is being driven by a qualitative upgrade in specification: buyers are shifting from ad-hoc, carpenter-built fit-outs toward branded, ergonomic, and modular systems procured through organized channels. This shift is expanding both the value per square foot of fitted office space and the addressable share of the organized sector.
Metric
Value
Base Year
2025
Forecast CAGR (2024-2029)
11.2%
Incremental Market Opportunity
USD 3.09 Billion
India Share of Global Market
~15%
Commercial Office Furniture Share
>50% of domestic demand
Fastest-Growing Channel
Online / B2C retail
Demand Drivers Reshaping Specification
India's growth profile is unusually broad-based relative to other Asia-Pacific markets, with multiple drivers operating simultaneously rather than in sequence.
Commercial real estate fit-out pipeline: Approximately 65–70 million sq ft of new office space absorption was recorded in the 2025 cycle, concentrated in Bengaluru, Hyderabad, Pune, Chennai, and the National Capital Region. Each square foot of Grade A delivery translates directly into task seating, workstations, storage, and collaborative furniture orders ranging across a 12–24 month lag.
Employment and GCC expansion: Global capability centres across technology, banking, and pharma verticals are leasing larger floorplates with higher density and wellness specifications, pulling average furniture spend per seat upward.
Hybrid work and collaboration hubs: Employers are reconfiguring floorplates into collaboration-heavy layouts, favouring modular desking, acoustic pods, mobile tables, and stackable seating that can be reconfigured without new capex.
Ergonomics and employee wellness mandates: Adjustable-height desks, lumbar-support task chairs, and posture-support seating have moved from premium to baseline specification in corporate tenders.
Co-working operator expansion: Flexible-space operators continue adding capacity in tier-one and tier-two cities, generating repeat refresh cycles at shorter intervals than traditional occupiers.
Digital procurement and B2C expansion: Online channels and dealer e-commerce portals are unlocking small and midsize business demand in tier-two and tier-three cities.
Constraints and Structural Frictions
The market's growth trajectory is real but not frictionless. Four constraints consistently temper the pace of organized-sector capture.
Raw material cost volatility: Timber, steel, aluminium, engineered board, and foam inputs are subject to import dependence, domestic forestry regulation, and commodity cycles. Margin pressure is acute in economy-tier tenders where price sensitivity is highest.
Fragmented unorganized competition: Local carpentry clusters and unbranded fabricators retain strong positions in cost-sensitive and customization-led segments, capping premium pricing power for organized brands in smaller cities.
Logistics and installation complexity: Bulky, damage-prone product categories demand specialized freight, last-mile handling, and on-site assembly capability — a capability gap outside major metros.
Compliance and traceability readiness: Sustainability and origin documentation requirements in export-facing supply chains and large enterprise tenders are pushing investment into material passports and product declarations, raising the fixed cost of qualifying for premium bids.
Segmentation Analysis
Product mix in India is led by seating, which commands the largest value share on the strength of per-seat replacement cycles and ergonomic upgrades. Tables and desking systems follow, with storage and filing systems growing more slowly as digitalization reduces physical filing requirements.
Segment Dimension
Dominant Category
Growth Outlook
Product
Seating (largest share)
Task and ergonomic seating fastest
Product
Tables & desking systems
Height-adjustable and modular desks
Product
Storage, filing & overhead bins
Slower, digitization-constrained
End-user
Commercial offices (>50%)
Sustained leadership
End-user
Home office
Volatile post-pandemic normalization
Channel
Offline dealers and showrooms
Largest revenue share
Channel
Online / e-commerce
Fastest growth, tier-two penetration
Material
Engineered wood and metal
Metal fastest-growing
Material substitution is a notable undercurrent. Engineered wood and metal composites are displacing solid timber in cost-sensitive workstation applications, driven by dimensional consistency, moisture resistance, and flat-pack logistics economics.
Import/Export and Supplier Dynamics
India operates as a net importer of high-end office furniture and a growing exporter of mid-tier and contract-grade product. Official trade statistics reveal a clear specialization pattern by material class.
Wooden office furniture exports reached USD 54.24 Million in 2023, with the United States as the single largest destination at USD 24.08 Million — roughly 44% of the total. The Netherlands (USD 8.73 Million), Germany (USD 3.71 Million), France (USD 3.29 Million), and the UAE (USD 1.65 Million) round out the top five.
Metal office furniture exports reached USD 20.59 Million in 2024, equivalent to 4.59 million kg, implying an average realization of approximately USD 4.49 per kg. The United States (USD 3.88 Million), Australia (USD 2.83 Million), Saudi Arabia (USD 2.07 Million), the UAE (USD 2.03 Million), and Nepal (USD 1.20 Million) lead the destination mix.
The destination profile is strategically instructive. Developed Western markets absorb India's wooden, design-led, and hospitality-grade output — a segment where European buyers increasingly demand traceability documentation. Gulf and South Asian markets absorb metal and contract-grade product for institutional, government, and education projects, where durability and standards compliance outrank aesthetics.
Supplier-side concentration is moderate. Tier-one contract manufacturing clusters in Maharashtra, Gujarat, Haryana, and Karnataka serve both export and domestic demand, while component supply — gas lifts, chair mechanisms, castors, laminates, and hardware — remains partially import-dependent, exposing cost structures to currency and freight cycles.
Procurement and Strategic White-Space Analysis
Three white-space corridors stand out for suppliers evaluating India's opportunity.
Modular workplace packages for Grade A fit-outs: Buyers increasingly prefer single-source suppliers capable of delivering seating, desking, storage, acoustic, and collaborative lines with consistent lead times — few Indian manufacturers offer this breadth credibly.
SME and tier-two digital demand: Standardized, flat-pack, warranty-backed product sold through online and dealer-hybrid channels remains under-served relative to demand growth.
Export-oriented sustainable lines: Wooden office furniture export growth is concentrated in developed markets where documentation readiness commands a price premium; few domestic suppliers have invested in environmental declarations at scale.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated at the branded end and highly fragmented overall. Multinational incumbents compete on design pedigree, global account relationships, and ergonomic credentials; domestic leaders compete on price-value, service footprint, customization, and installation depth.
Consolidation is an active strategic lever globally, with scale-focused acquisitions aimed at procurement synergy and distribution breadth. In India, the competitive priority is different: local showroom density, dealer network depth, and after-sales service responsiveness determine wallet share more than global brand equity.
Global players target multinational GCCs and premium corporate accounts.
Domestic organized brands dominate mid-market commercial tenders and public-sector contracts.
Regional fabricators hold cost-sensitive and bespoke segments.
Co-working operators increasingly act as volume anchor buyers with standardized specifications.
Outlook and Investment Assessment
The India office furniture market is well positioned for sustained double-digit expansion through the forecast period. The central assumption underpinning this outlook is continuation of Grade A commercial absorption above 55 million sq ft annually, supported by GCC expansion and services-sector employment.
Downside risks are concentrated in commodity input inflation and equipment-cost pass-through on imported components. Upside potential lies in faster-than-expected organized-sector penetration in tier-two cities and in export growth to Gulf and Western markets.
Investors and suppliers should prioritize three capability investments: modular product breadth, dealer and digital channel presence in tier-two geographies, and documented sustainability compliance for enterprise and export tenders.
India - Office Furniture Market Regional Market Share
Loading chart...
India - Office Furniture Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
India - Office Furniture Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.2% from 2020-2034
Segmentation
By Product
Seating
Tables
Storage units and files
Overhead bins
Systems
By Material
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Commercial real estate expansion with 65–70 million sq ft of 2025 office absorption
3.1.2. GCC and employment growth expanding higher-specification floorplates
3.4.2. Raw material price volatility across timber, steel, foam, and laminates
3.4.3. Limited logistics and on-site installation capability outside major metros
3.4.4. Rising compliance and traceability documentation burden for premium tenders
3.5. Market Challenges
3.5.1. Managing input cost pass-through in economy-tier price-sensitive tenders
3.5.2. Building dealer and service depth beyond tier-one metropolitan clusters
3.5.3. Qualifying for enterprise and export tenders with full documentation readiness
3.5.4. Balancing customization demand against standardized manufacturing economics
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Seating
5.1.2. Tables
5.1.3. Storage units and files
5.1.4. Overhead bins
5.1.5. Systems
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Wood
5.2.2. Metal
5.2.3. Plastic
5.2.4. Engineered wood
5.3. Market Analysis, Insights and Forecast - by End-user
5.3.1. Commercial office furniture
5.3.2. Home office furniture
5.3.3. Hospitality and retail back-office
5.4. Market Analysis, Insights and Forecast - by Distribution Channel
5.4.1. Offline
5.4.2. Online
5.4.3. B2B direct-from-manufacturer
5.4.4. B2C retail
5.5. Market Analysis, Insights and Forecast - by Price Range
5.5.1. Economy
5.5.2. Mid-range
5.5.3. Premium
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North
5.6.2. West
5.6.3. South
5.6.4. East
6. North Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Seating
6.1.2. Tables
6.1.3. Storage units and files
6.1.4. Overhead bins
6.1.5. Systems
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Wood
6.2.2. Metal
6.2.3. Plastic
6.2.4. Engineered wood
6.3. Market Analysis, Insights and Forecast - by End-user
6.3.1. Commercial office furniture
6.3.2. Home office furniture
6.3.3. Hospitality and retail back-office
6.4. Market Analysis, Insights and Forecast - by Distribution Channel
6.4.1. Offline
6.4.2. Online
6.4.3. B2B direct-from-manufacturer
6.4.4. B2C retail
6.5. Market Analysis, Insights and Forecast - by Price Range
6.5.1. Economy
6.5.2. Mid-range
6.5.3. Premium
7. West Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Seating
7.1.2. Tables
7.1.3. Storage units and files
7.1.4. Overhead bins
7.1.5. Systems
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Wood
7.2.2. Metal
7.2.3. Plastic
7.2.4. Engineered wood
7.3. Market Analysis, Insights and Forecast - by End-user
7.3.1. Commercial office furniture
7.3.2. Home office furniture
7.3.3. Hospitality and retail back-office
7.4. Market Analysis, Insights and Forecast - by Distribution Channel
7.4.1. Offline
7.4.2. Online
7.4.3. B2B direct-from-manufacturer
7.4.4. B2C retail
7.5. Market Analysis, Insights and Forecast - by Price Range
7.5.1. Economy
7.5.2. Mid-range
7.5.3. Premium
8. South Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Seating
8.1.2. Tables
8.1.3. Storage units and files
8.1.4. Overhead bins
8.1.5. Systems
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Wood
8.2.2. Metal
8.2.3. Plastic
8.2.4. Engineered wood
8.3. Market Analysis, Insights and Forecast - by End-user
8.3.1. Commercial office furniture
8.3.2. Home office furniture
8.3.3. Hospitality and retail back-office
8.4. Market Analysis, Insights and Forecast - by Distribution Channel
8.4.1. Offline
8.4.2. Online
8.4.3. B2B direct-from-manufacturer
8.4.4. B2C retail
8.5. Market Analysis, Insights and Forecast - by Price Range
8.5.1. Economy
8.5.2. Mid-range
8.5.3. Premium
9. East Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Seating
9.1.2. Tables
9.1.3. Storage units and files
9.1.4. Overhead bins
9.1.5. Systems
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Wood
9.2.2. Metal
9.2.3. Plastic
9.2.4. Engineered wood
9.3. Market Analysis, Insights and Forecast - by End-user
9.3.1. Commercial office furniture
9.3.2. Home office furniture
9.3.3. Hospitality and retail back-office
9.4. Market Analysis, Insights and Forecast - by Distribution Channel
9.4.1. Offline
9.4.2. Online
9.4.3. B2B direct-from-manufacturer
9.4.4. B2C retail
9.5. Market Analysis, Insights and Forecast - by Price Range
9.5.1. Economy
9.5.2. Mid-range
9.5.3. Premium
10. Competitive Analysis
10.1. Company Profiles
10.1.1. Godrej Interio
10.1.1.1. Company Overview
10.1.1.2. Products
10.1.1.3. Company Financials
10.1.1.4. SWOT Analysis
10.1.2. Featherlite
10.1.2.1. Company Overview
10.1.2.2. Products
10.1.2.3. Company Financials
10.1.2.4. SWOT Analysis
10.1.3. Nilkamal
10.1.3.1. Company Overview
10.1.3.2. Products
10.1.3.3. Company Financials
10.1.3.4. SWOT Analysis
10.1.4. Wipro Furniture
10.1.4.1. Company Overview
10.1.4.2. Products
10.1.4.3. Company Financials
10.1.4.4. SWOT Analysis
10.1.5. Chairwale
10.1.5.1. Company Overview
10.1.5.2. Products
10.1.5.3. Company Financials
10.1.5.4. SWOT Analysis
10.1.6. HNI Corporation
10.1.6.1. Company Overview
10.1.6.2. Products
10.1.6.3. Company Financials
10.1.6.4. SWOT Analysis
10.1.7. Steelcase
10.1.7.1. Company Overview
10.1.7.2. Products
10.1.7.3. Company Financials
10.1.7.4. SWOT Analysis
10.1.8. Haworth
10.1.8.1. Company Overview
10.1.8.2. Products
10.1.8.3. Company Financials
10.1.8.4. SWOT Analysis
10.1.9. MillerKnoll
10.1.9.1. Company Overview
10.1.9.2. Products
10.1.9.3. Company Financials
10.1.9.4. SWOT Analysis
10.1.10. Okamura
10.1.10.1. Company Overview
10.1.10.2. Products
10.1.10.3. Company Financials
10.1.10.4. SWOT Analysis
10.1.11. Boss Design
10.1.11.1. Company Overview
10.1.11.2. Products
10.1.11.3. Company Financials
10.1.11.4. SWOT Analysis
10.1.12. Global Industries
10.1.12.1. Company Overview
10.1.12.2. Products
10.1.12.3. Company Financials
10.1.12.4. SWOT Analysis
10.2. Market Entropy
10.2.1. Company's Key Areas Served
10.2.2. Recent Developments
10.3. Company Market Share Analysis, 2026
10.3.1. Top 5 Companies Market Share Analysis
10.3.2. Top 3 Companies Market Share Analysis
10.4. List of Potential Customers
List of Figures
Figure 1: Global India - Office Furniture Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North India - Office Furniture Market Revenue (Billion), by Product 2026 & 2034
Figure 3: North India - Office Furniture Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North India - Office Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 5: North India - Office Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 6: North India - Office Furniture Market Revenue (Billion), by End-user 2026 & 2034
Figure 7: North India - Office Furniture Market Revenue Share (%), by End-user 2026 & 2034
Figure 8: North India - Office Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 9: North India - Office Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 10: North India - Office Furniture Market Revenue (Billion), by Price Range 2026 & 2034
Figure 11: North India - Office Furniture Market Revenue Share (%), by Price Range 2026 & 2034
Figure 12: North India - Office Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North India - Office Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 14: West India - Office Furniture Market Revenue (Billion), by Product 2026 & 2034
Figure 15: West India - Office Furniture Market Revenue Share (%), by Product 2026 & 2034
Figure 16: West India - Office Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 17: West India - Office Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 18: West India - Office Furniture Market Revenue (Billion), by End-user 2026 & 2034
Figure 19: West India - Office Furniture Market Revenue Share (%), by End-user 2026 & 2034
Figure 20: West India - Office Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 21: West India - Office Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 22: West India - Office Furniture Market Revenue (Billion), by Price Range 2026 & 2034
Figure 23: West India - Office Furniture Market Revenue Share (%), by Price Range 2026 & 2034
Figure 24: West India - Office Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 25: West India - Office Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 26: South India - Office Furniture Market Revenue (Billion), by Product 2026 & 2034
Figure 27: South India - Office Furniture Market Revenue Share (%), by Product 2026 & 2034
Figure 28: South India - Office Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 29: South India - Office Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 30: South India - Office Furniture Market Revenue (Billion), by End-user 2026 & 2034
Figure 31: South India - Office Furniture Market Revenue Share (%), by End-user 2026 & 2034
Figure 32: South India - Office Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 33: South India - Office Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 34: South India - Office Furniture Market Revenue (Billion), by Price Range 2026 & 2034
Figure 35: South India - Office Furniture Market Revenue Share (%), by Price Range 2026 & 2034
Figure 36: South India - Office Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 37: South India - Office Furniture Market Revenue Share (%), by Country 2026 & 2034
Figure 38: East India - Office Furniture Market Revenue (Billion), by Product 2026 & 2034
Figure 39: East India - Office Furniture Market Revenue Share (%), by Product 2026 & 2034
Figure 40: East India - Office Furniture Market Revenue (Billion), by Material 2026 & 2034
Figure 41: East India - Office Furniture Market Revenue Share (%), by Material 2026 & 2034
Figure 42: East India - Office Furniture Market Revenue (Billion), by End-user 2026 & 2034
Figure 43: East India - Office Furniture Market Revenue Share (%), by End-user 2026 & 2034
Figure 44: East India - Office Furniture Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 45: East India - Office Furniture Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 46: East India - Office Furniture Market Revenue (Billion), by Price Range 2026 & 2034
Figure 47: East India - Office Furniture Market Revenue Share (%), by Price Range 2026 & 2034
Figure 48: East India - Office Furniture Market Revenue (Billion), by Country 2026 & 2034
Figure 49: East India - Office Furniture Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global India - Office Furniture Market Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Global India - Office Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 3: Global India - Office Furniture Market Revenue Billion Forecast, by End-user 2020 & 2034
Table 4: Global India - Office Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 5: Global India - Office Furniture Market Revenue Billion Forecast, by Price Range 2020 & 2034
Table 6: Global India - Office Furniture Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North India - Office Furniture Market Revenue Billion Forecast, by Product 2020 & 2034
Table 8: North India - Office Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 9: North India - Office Furniture Market Revenue Billion Forecast, by End-user 2020 & 2034
Table 10: North India - Office Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 11: North India - Office Furniture Market Revenue Billion Forecast, by Price Range 2020 & 2034
Table 12: North India - Office Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Delhi NCR India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Haryana India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Punjab India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: West India - Office Furniture Market Revenue Billion Forecast, by Product 2020 & 2034
Table 17: West India - Office Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 18: West India - Office Furniture Market Revenue Billion Forecast, by End-user 2020 & 2034
Table 19: West India - Office Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 20: West India - Office Furniture Market Revenue Billion Forecast, by Price Range 2020 & 2034
Table 21: West India - Office Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Maharashtra India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Gujarat India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Rajasthan India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: South India - Office Furniture Market Revenue Billion Forecast, by Product 2020 & 2034
Table 26: South India - Office Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 27: South India - Office Furniture Market Revenue Billion Forecast, by End-user 2020 & 2034
Table 28: South India - Office Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 29: South India - Office Furniture Market Revenue Billion Forecast, by Price Range 2020 & 2034
Table 30: South India - Office Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 31: Karnataka India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Telangana India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Tamil Nadu India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Kerala India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: East India - Office Furniture Market Revenue Billion Forecast, by Product 2020 & 2034
Table 36: East India - Office Furniture Market Revenue Billion Forecast, by Material 2020 & 2034
Table 37: East India - Office Furniture Market Revenue Billion Forecast, by End-user 2020 & 2034
Table 38: East India - Office Furniture Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 39: East India - Office Furniture Market Revenue Billion Forecast, by Price Range 2020 & 2034
Table 40: East India - Office Furniture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 41: West Bengal India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Odisha India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Bihar India - Office Furniture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size and growth rate of the India office furniture market?
The India office furniture market is forecast to add USD 3.09 Billion in incremental value between 2024 and 2029, growing at a CAGR of 11.2%. India currently represents approximately 15% of global office furniture consumption.
2Which segment dominates the India office furniture market?
Commercial office furniture accounts for more than 50% of domestic market value, supported by Grade A office fit-outs approaching 65–70 million sq ft of annual absorption. Seating remains the largest product category by value share.
3Which are India's largest export destinations for office furniture?
The United States is the leading destination for both wooden office furniture exports (USD 24.08 Million in 2023) and metal office furniture exports (USD 3.88 Million in 2024). The Netherlands, Germany, France, UAE, Australia, and Saudi Arabia are also significant buyers.
4Why is metal office furniture growing faster than wood in India?
Metal offers durability, lighter weight, lower maintenance, dimensional consistency, and better flat-pack logistics economics, making it preferred for institutional, co-working, and contract-grade applications. It is the fastest-growing material segment.
5What is driving office furniture demand in India?
Key drivers include commercial real estate expansion, GCC and employment growth, hybrid workplace reconfiguration into collaboration hubs, ergonomic wellness mandates, co-working operator expansion, and digital procurement reaching tier-two and tier-three cities.
6What challenges constrain the India office furniture market?
Volatile raw material costs for timber, steel, and foam; fragmented unorganized competition from local carpenters; logistics and installation limitations outside major metros; and rising compliance documentation requirements for enterprise and export tenders.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70–80% of the research input base is derived from primary fieldwork, including structured CATI and in-depth interviews with contract furniture manufacturers, office furniture dealers and resellers, corporate facilities and procurement heads, and co-working space operators across Bengaluru, Hyderabad, Mumbai, Pune, Chennai, and NCR.
Stakeholder interviews target Procurement Directors, Workplace Strategy and Facilities Managers, Real Estate and Fit-Out Heads, and Channel/Dealer Principals to validate specification trends, tender pricing, and replacement cycles.
Manufacturer and dealer channel checks quantify order books, lead times, capacity utilization, and category-level price realization, with localized triangulation across North, South, East, and West zones.
Project-level verification of commercial fit-out activity is cross-referenced against tracked office absorption volumes, leasing data, and installation schedules to validate bottom-up demand.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Facilities & Workplace Strategy Manager
26%
Real Estate & Fit-Out Head
24%
Channel & Dealer Principal
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Contract Office Furniture Manufacturers
32%
Office Furniture Dealers & Resellers
24%
Corporate Facilities & Procurement Teams
21%
Co-Working Space Operators
13%
Component & Raw Material Suppliers
10%
Secondary Research & Industry Benchmarking
Company filings, annual reports, and investor disclosures from listed furniture manufacturers and workplace solution providers are reviewed alongside financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Official trade statistics from UN Comtrade and World Bank WITS are used to benchmark wooden (HS 940330) and metal (HS 940310) office furniture export flows, destination concentration, and unit realizations.
All estimates are subsequently validated against recognized non-profit trade association data and official government statistical releases; no commercial report portal is used as a primary source.
Demand Modeling & Market Estimation
Simultaneous top-down and bottom-up methodologies are applied: top-down sizing anchors India's share of Asia-Pacific and global office furniture value, while bottom-up build-up is constructed from specific quantitative metrics including new Grade A office space absorption (sq ft), average furniture spend per workstation, seating replacement cycle frequency, and dealer-level revenue aggregation.
Segment-level models are run independently for product, material, end-user, and channel, then reconciled via multi-level data triangulation to ensure internal consistency.
Procurement pipeline modeling converts tracked commercial real estate deliveries into forward furniture demand with a 12–24 month lag assumption, adjusted for hybrid density ratios.
Export potential is modeled from destination-level trade data, applying realized unit values and projected demand growth in the US, Gulf, and European markets.
Data Accuracy & Quality Check
The research process targets a guaranteed data accuracy level of 85–90%, achieved through cross-validation of primary interview responses against trade statistics and company disclosures.
Multi-level triangulation requires convergence of top-down, bottom-up, and channel-check estimates before any figure is published; outliers are re-interviewed or excluded.
Every report is updated to the date of purchase, with the latest available data incorporated into the final dataset and forecast assumptions re-validated at delivery.
Sensitivity analysis is performed on raw material price volatility and commercial absorption assumptions to bound the forecast range.