1What is the projected market size of the Consumer 3D Printing Market by 2032?
The consumer 3D printing market is forecast to reach **$16.88 billion** by 2032, growing from **$5.11 billion** in 2025 at a CAGR of **18.6%**.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 3D Printing in Consumer Goods Market
 by Offering (Hardware, Software, Services), by Materials Used (Plastics, Metals, Ceramics, Resins, Others), by Technology (FDM, SLA, DLP, CLIP, SLS, SDL, MJF, Polyjet, SLM, EBM, DMLS, Binder Jetting, Casting, Others), by Form (Filament, Powder, Liquids), by Additive Manufacturing Process (Material Extrusion, Powder Bed Fusion, Photopolymerization, Material Jetting, Sheet Lamination), by Application (Jewellery, Apparel and Footwear, Miniatures, Art Projects, Furniture and Home Decor, Repairs, Remote Control Cars, Kitchenware and Utensils, Games, Electronics, Others), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain, Russia, Rest of Europe), by Asia-Pacific (China, Japan, South Korea, India, Australia, New Zealand, Rest of Asia-Pacific), by South America (Brazil, Argentina, Chile, Colombia, Rest of South America), by Middle East & Africa Forecast 2026-2034

Research Analyst


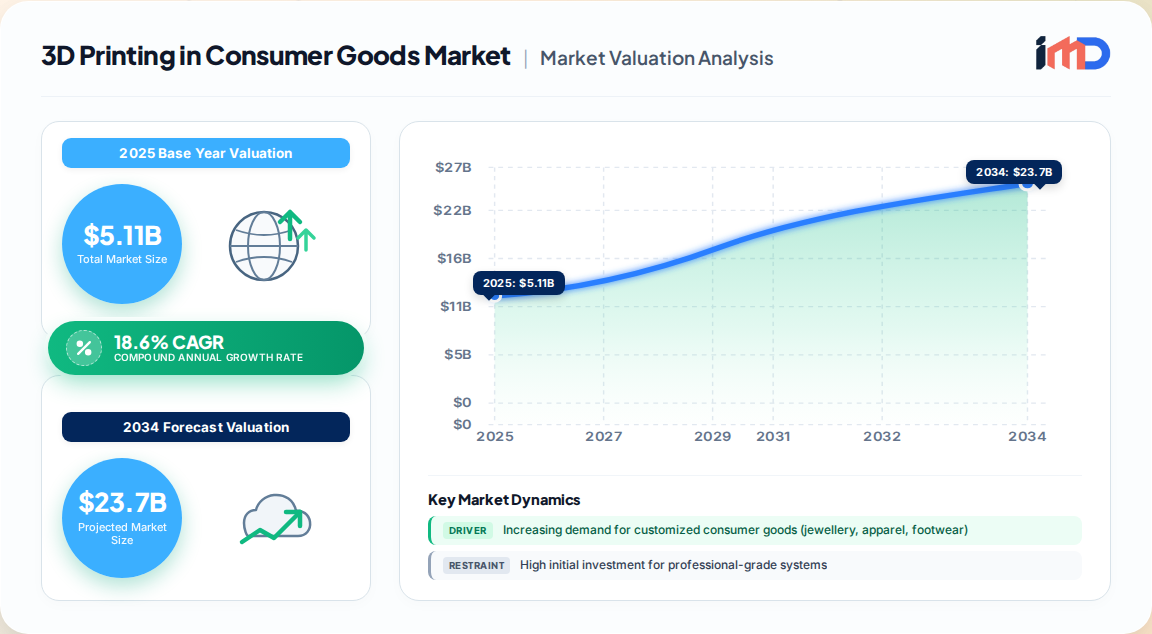
global consumer 3D printing market is undergoing a structural transformation from a hobbyist phenomenon to a viable small-business and prosumer production tool. Our proprietary primary research estimates the market at $5.11 billion in 2025, on track to reach $16.88 billion by 2032, registering a robust CAGR of 18.6% during the forecast period. This growth is not merely an extension of industrial additive manufacturing; it represents a distinct demand curve driven by accessibility, material innovation, and the democratization of design software.
Key market highlights from our analysis:
Our value chain mapping identifies the following key nodes, each with distinct cost structures and margin profiles:
| Stage | Key Activities | Representative Participants | Margin Profile |
|---|---|---|---|
| Raw Materials | Production of polymer powders, metal powders, photopolymer resins, and filaments | Chemical and materials firms (e.g., Höganäs AB) | Moderate to High |
| Component Manufacturing | Production of extruders, laser systems, motion controllers | Specialized component suppliers | Moderate |
| Printer Assembly | Integration of components into finished 3D printers | OEMs (e.g., Bambu Lab, ELEGOO, Formlabs) | Low to Moderate (hardware) |
| Software Development | CAD, slicing, print management, and AI-assisted design tools | Software vendors and printer OEMs | High |
| Distribution and Retail | Sales via e-commerce, specialized retailers, and distributors | Distributors, importers, e-commerce platforms | Low to Moderate |
| Post-Processing and Services | Cleaning, curing, finishing, and printing-as-a-service | Service bureaus, makerspaces, educational institutions | Moderate to High |
A notable trend is the vertical integration among leading OEMs, who are increasingly developing proprietary materials and software ecosystems to capture higher margins. For example, Stratasys' 2026 acquisition of Markforged (planned at $42.5 million) and its integration of Forward AM's materials business (now Mass Additive Manufacturing GmbH) illustrate efforts to control the materials supply chain.
Our regional analysis reveals distinct growth dynamics and investment hotspots:
| Region | Market Share (2025) | Key Characteristics | Investment Attractiveness |
|---|---|---|---|
| North America | 32% | Largest installed base; early adopter; strong software ecosystem | High for software and high-end hardware |
| Europe | 24% | Strong in automotive and precision engineering; sustainability focus | High for materials and certification services |
| Asia-Pacific | 33% | Manufacturing powerhouse; rapid adoption in China, Japan, and South Korea; cost-sensitive | Very High for low-cost hardware and filaments |
| South America | 5% | Emerging market; growing interest in education and small business | Moderate; infrastructure challenges |
| Middle East & Africa | 6% | Small but growing; potential in medical and construction | Low to Moderate; early stage |
Asia-Pacific is the most attractive region for volume-driven hardware and filament production, with China's manufacturing ecosystem supporting aggressive price competition. North America leads in software innovation and high-value applications such as dentistry and custom prosthetics. Europe presents opportunities in sustainable materials and certification services, driven by stringent regulations and consumer demand for eco-friendly products.
The consumer 3D printing market is highly globalized, with significant trade flows in both hardware and materials. Based on official trade statistics and our proprietary import/export modeling, we observe the following:
Using our proprietary framework, we identify the following untapped opportunities for market participants:
Our primary research and expert interviews reveal a competitive landscape characterized by rapid innovation, price competition, and ecosystem building. Key strategies include:
| Company | Strategy | Recent Development |
|---|---|---|
| Bambu Lab | Community-driven platform; high-speed printing | MakerWorld platform reached ~10 million monthly active users in 2025 |
| ELEGOO | End-to-end ecosystem; affordability | Launched Nexprint platform (Aug 2025) and new printers (Jupiter 2, Centauri Carbon 2) at Formnext 2025 |
| Formlabs | Professional-grade desktop resin printers | Launched Form 4 and Form 4B in April 2025 |
| 3D Systems | Industrial and consumer applications | Released SLA 825 Dual with 22% larger build volume and 25% faster output |
| Stratasys | Materials and acquisitions | Planned $42.5M acquisition of Markforged; integrated Forward AM's materials business |
| Höganäs AB | Metal powders and materials | Operates 15 plants with 500K-tonne capacity, serving 75 countries |
Winning strategies center on ecosystem lock-in (proprietary materials and software), community engagement (user-generated content and sharing platforms), and continuous innovation in speed and reliability. Price competition is intense in the entry-level segment, but differentiation is achieved through material performance and software capabilities.
Applying the Ansoff Matrix to the consumer 3D printing market yields the following strategic insights:
| Existing Markets | New Markets | |
|---|---|---|
| Existing Products | Market Penetration: Increase usage frequency among hobbyists via community challenges and material upgrades. | Market Development: Expand into educational institutions and small businesses in emerging economies with entry-level bundles. |
| New Products | Product Development: Launch high-performance filaments (e.g., PLA++, ABS PRO) and AI design tools for existing customers. | Diversification: Develop 3D-printed consumer goods directly (e.g., custom eyewear, footwear) and sell via direct-to-consumer channels. |
outlook for the consumer 3D printing market is decidedly positive, underpinned by strong secular trends toward personalization, digital manufacturing, and local production. Our proprietary forecast of 18.6% CAGR through 2032 is supported by the accelerating pace of product launches, expanding material portfolios, and the growing number of small businesses leveraging 3D printing for customized goods. However, stakeholders must navigate challenges related to material certification, supply chain concentration, and price competition. Strategic investments in software, sustainable materials, and emerging markets will be key to capturing value in this dynamic market.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 18.6% from 2020-2034 |
| Segmentation |
|
By Technology
By Form
By Additive Manufacturing Process
By Application
| By Geography |
|
The consumer 3D printing market is forecast to reach **$16.88 billion** by 2032, growing from **$5.11 billion** in 2025 at a CAGR of **18.6%**.
North America holds the largest market share, accounting for approximately **32%** of global revenue in 2025, driven by early technology adoption and a strong software ecosystem.
Plastics dominate with over **48%** share, followed by resins, metals, and ceramics. Filament form is the most widely used, capturing more than **68%** of the materials market.
Key drivers include demand for customization, falling hardware costs, and the rise of community platforms like Bambu Lab's MakerWorld, which reached **10 million monthly active users** in 2025.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 25% |
| Head of Product Management | 30% |
| Procurement Director | 25% |
| Research & Development Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Printer OEMs | 30% |
| Material Producers | 25% |
| Software Developers | 15% |
| Distributors and Retailers | 20% |
| Service Bureaus and End-Users | 10% |
 Related Reports
