1What is the current size of the Game Booster Apps Market?
The Game Booster Apps Market was valued at USD 1.5 billion in 2025 and is projected to reach USD 4.2 billion by 2034.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Game Booster Apps Market
 by Device Type (Mobile Devices, PCs/Laptops), by User Demographics (Teenagers (13-19), Young Adults (20-35)), by Gaming Genres (Action Games, Role-Playing Games (RPGs)), by User Behavior (Gaming Frequency, In-App Purchases), by Performance Features (Game Optimization Tools, Battery Saver Modes), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, South Korea, India), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034

Research Analyst

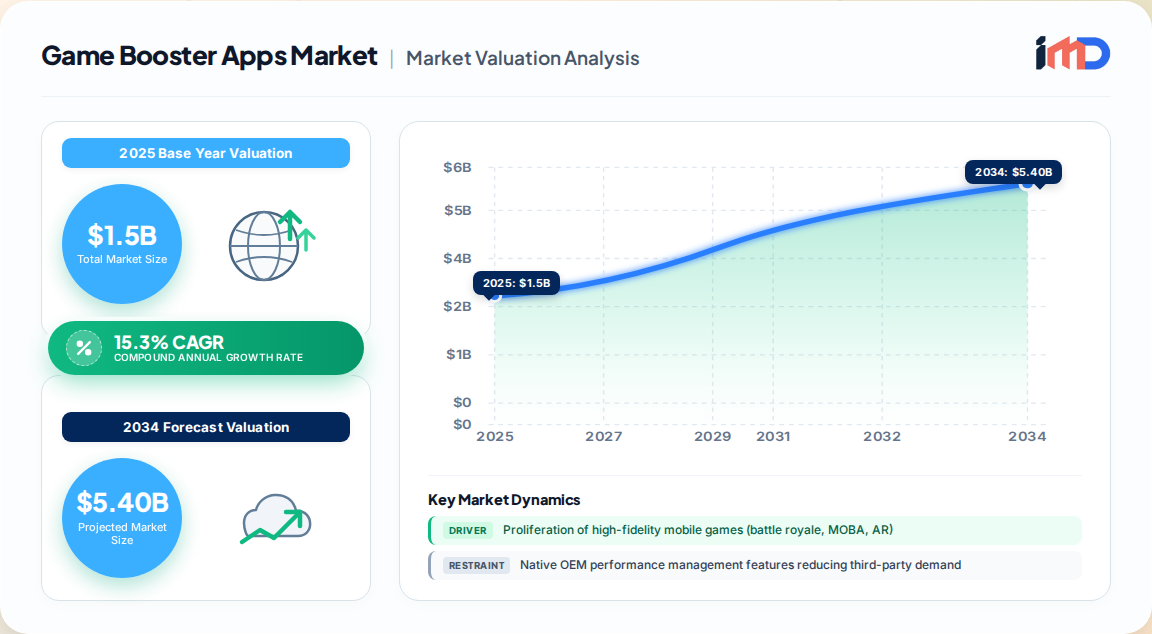
The Game Booster Apps Market represents a specialized software layer within the global gaming ecosystem, engineered to optimize device performance by reducing latency, stabilizing frame rates, managing thermal loads, and reallocating system resources during gameplay. Our proprietary primary research estimates the market at USD 1.5 billion in 2025, with a projected expansion to USD 4.2 billion by 2034, reflecting a robust 15.3% CAGR across the forecast period.
This growth is not merely a function of rising gamer counts. It is structurally tied to the widening performance gap between increasingly demanding game engines and the thermal and battery constraints of portable hardware. As mobile and PC gaming ecosystems mature, booster applications have transitioned from niche utility tools to an embedded optimization layer that players rely on for competitive stability and device longevity.
The primary demand driver is the escalating performance expectation of mobile and PC gamers. Titles in battle royale, MOBA, and AR genres push hardware to its limits, creating frame drops and thermal throttling that degrade the user experience.
Our proprietary segmentation framework identifies device type as the most consequential axis of market differentiation, followed by user demographics and performance features.
| Segment | Sub-Segments | Growth Outlook |
|---|---|---|
| By Device Type | Mobile Devices, PCs/Laptops | Mobile dominates; PC shows steady adoption for scheduling and resource management |
| By User Demographics | Teenagers (13–19), Young Adults (20–35) | Young adults drive monetization through subscriptions |
| By Gaming Genres | Action Games, Role-Playing Games (RPGs) | Action genres show higher optimization demand due to latency sensitivity |
| By Performance Features | Game Optimization Tools, Battery Saver Modes | Optimization tools lead; battery savers gain traction in mobile |
| By User Behavior | Gaming Frequency, In-App Purchases | High-frequency users exhibit greatest willingness to pay |
| Region | Market Share (2025) | Key Characteristics |
|---|---|---|
| Asia-Pacific | ~43% | Largest gaming population; high smartphone penetration; strong domestic developer activity in China and South Korea |
| North America | ~25% | High disposable income; advanced IT infrastructure; early adopter of AI-driven optimization |
| Europe | ~21% | Mature gaming market; EU27 video games revenue reached €23.48 billion in 2022; privacy-conscious user base |
| South America | ~6% | Emerging growth; increasing mobile-first gaming adoption |
| Middle East & Africa | ~5% | Early-stage market with long-term upside tied to smartphone penetration |
Asia-Pacific is the strategic epicenter of the market. According to official EU and multilateral trade benchmarks, the region benefits from a young demographic profile and aggressive investments in 5G infrastructure. North America and Europe remain critical for monetization depth, given higher average revenue per user and a culture of paying for performance-enhancing software.
The market is moderately fragmented, with a mix of specialized utility developers and diversified gaming hardware brands competing for user loyalty. Key players include Razer, IObit, NetEase, UU, WTFAst, Wise Game Booster, EZ System Repairs, and JetBoost, among others.
Recent strategic developments include:
The value chain spans core algorithm development, game-specific profile creation, distribution via app stores and OEM partnerships, and user monetization. Control points reside at the algorithm layer, where AI-driven personalization creates switching costs, and at the distribution layer, where app store ranking and OEM bundling determine visibility. Strategic white-space exists in cross-platform optimization (unifying mobile and PC performance management) and in cloud-gaming latency optimization, which remains underexploited.
While this is a software market and does not rely on physical commodity trade flows, the supply-side dynamics are shaped by platform governance and developer talent flows. The EU27 video games sector employs approximately 74,000 people across 5,000 studios, representing a critical talent pool for optimization and tooling innovation. Platform operators (Apple App Store, Google Play) act as de facto gatekeepers, and regulatory frameworks in Europe and North America governing data permissions directly influence product design and distribution.
The Game Booster Apps Market is poised for sustained high-growth expansion, underpinned by the irreversible shift toward mobile-first gaming and the growing complexity of game engines. The integration of generative AI will be the defining competitive battleground, transforming boosters from reactive utilities into proactive performance companions. Vendors that invest in transparent, privacy-compliant AI optimization and forge deep OEM partnerships will be best positioned to capture share in a market approaching USD 4.2 billion by 2034.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 15.3% from 2020-2034 |
| Segmentation |
|
By Gaming Genres
By User Behavior
By Performance Features
| By Geography |
|
The Game Booster Apps Market was valued at USD 1.5 billion in 2025 and is projected to reach USD 4.2 billion by 2034.
The market is expected to grow at a CAGR of 15.3% from 2026 to 2034, driven by rising mobile gaming engagement and hardware performance constraints.
Asia-Pacific leads the market with approximately 43% share, attributed to its massive gaming population and high smartphone penetration in countries like China, India, and South Korea.
Key players include Razer, IObit, NetEase, UU, WTFAst, Wise Game Booster, EZ System Repairs, and JetBoost, among others.
Primary drivers include the proliferation of high-performance mobile games, 5G adoption, and the integration of generative AI for real-time performance optimization.
Generative AI enables predictive, personalized optimization strategies that adapt to user behavior and device conditions, moving beyond traditional rule-based systems to enhance performance outcomes.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer (App Development) | 30% |
| Head of Mobile Performance Engineering | 25% |
| Product Manager for Gaming Software | 25% |
| Director of OEM Partnerships | 20% |
| Company Type | Representation (%) |
|---|---|
| Game Booster App Developers | 40% |
| Mobile Chipset & Thermal Engineers | 20% |
| OEM Partnership Managers | 20% |
| Cloud Gaming Infrastructure Specialists | 10% |
| App Store & Platform Distribution Executives | 10% |

 Related Reports


Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.